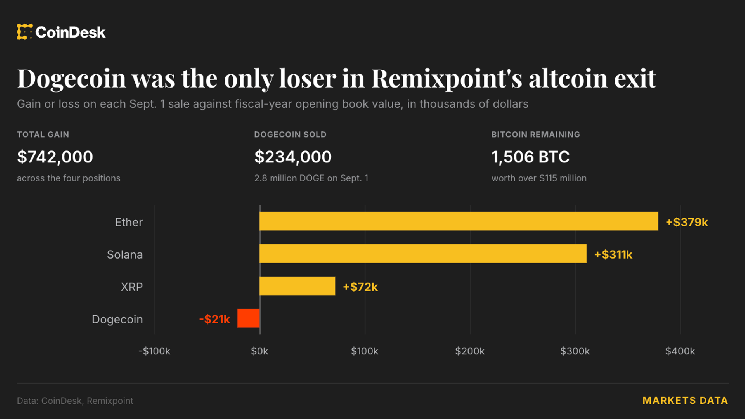
Japan-listed Remixpoint made money when it reported selling ether ETH$2,404.40, solana (SOL) and $XRP on Wednesday. Dogecoin $DOGE$0.08115 was the exception.
The company sold 2.8 million $DOGE on Sept. 1 for about $234,000, roughly $21,000 below its fiscal-year opening book value. Ether produced a $379,000 gain, solana $311,000 and $XRP about $72,000, leaving Remixpoint with a roughly $742,000 gain across the four positions.
The $DOGE loss is measured against the value Remixpoint carried the position at when its current fiscal year began, rather than its original purchase cost. The company sold all four altcoins on the same day.
The loss stands out because dogecoin is no fringe token in Japan. $DOGE has been traded by registered Japanese crypto exchanges since 2022, and the Japan Virtual and Crypto Assets Exchange Association, the industry’s recognized self-regulatory body, began publishing an official $DOGE/JPY reference price this year alongside bitcoin, ether, $XRP and solana.
Remixpoint said it sold the four tokens after reviewing market conditions and their risk-return characteristics, and will now concentrate its crypto holdings in bitcoin.
The company still owns about 1,506 BTC, worth over $115 million at Thursday prices, making bitcoin its only remaining cryptocurrency.
The U.S. Commodity Futures Trading Commission asked a federal court on Sept. 2 to dismiss CME Group’s lawsuit challenging the regulator’s treatment of cryptocurrency perpetual contracts as futures.
The CFTC argued that CME lacks legal standing because the exchange could list perpetual futures under the same regulatory policy it is challenging. The agency characterized part of CME’s claimed competitive disadvantage as resulting from its own decision not to offer comparable products.
CME filed the case in the U.S. District Court for the District of Columbia on June 18. It seeks to overturn the CFTC’s approval of Kalshi’s Bitcoin perpetual contract and a related agency policy statement.
The dismissal request represents the regulator’s position. The court has not ruled on the motion or decided whether cryptocurrency perpetual contracts should legally be treated as futures or swaps.
The CFTC moved to dismiss CME Group’s lawsuit challenging its approval of Kalshi’s Bitcoin perpetual futures, arguing CME failed to show competitive injury and lacks standing to challenge the decision.https://t.co/zu5JwAqVBM
— Gambity (@gambitycom) September 3, 2026
CFTC says CME created its alleged disadvantage
To establish standing in federal court, a plaintiff generally must show a concrete injury linked to the defendant’s conduct. It must also demonstrate that a favorable court ruling would likely address that injury.
CME claims the CFTC’s decision gave newer exchanges an unfair competitive advantage by allowing them to offer perpetual contracts under the futures framework. The exchange says those products should instead face the rules applying to swaps.
The CFTC disputes the claimed injury. It argued that CME is also a designated contract market and can seek permission to list perpetual futures under the same process available to Kalshi.
According to the regulator, any disadvantage arising from CME’s decision not to list the contracts is therefore “self-inflicted.” The agency said a party cannot establish standing by declining to use the same regulatory opportunity available to its competitors.
The CFTC also pointed to CME’s own trading figures. It said the exchange’s Bitcoin and Ether futures volumes in June and August exceeded their May levels, when the Kalshi approval was issued.
Those figures form part of the regulator’s argument that CME has not shown a concrete competitive loss caused by the approval. CME may challenge that interpretation when it responds to the motion.
Reclassification may not resolve CME’s alleged harm
The CFTC raised a second standing argument involving redressability. Even if the court classified perpetual contracts as swaps, the regulator said competing venues could still offer economically similar products.
A ruling in CME’s favor would therefore change the regulatory category without necessarily removing the competition CME claims is harming its business.
The CFTC said CME is not challenging the agency’s general authority to approve the product. Instead, the lawsuit focuses on whether the Kalshi contract fits the legal definition of futures or swaps.
The regulator also argued that CME’s competitive interests do not fall within the “zone of interests” protected by the Commodity Exchange Act provisions cited in the lawsuit. This test asks whether the interests a plaintiff seeks to protect relate to the purposes of the statute allegedly violated.
CME has presented the dispute as an issue involving regulatory consistency and investor protection. The CFTC’s motion frames it as a competitor attempting to use litigation against products it could offer itself.
CME says perpetual contracts are swaps
Perpetual contracts give traders continuing price exposure without a predetermined expiration date. They commonly use recurring funding payments to keep contract prices aligned with the referenced asset.
Traditional futures usually have fixed expiration and settlement dates. CME argues that the lack of an expiration date places perpetuals within the swap definition established under the Dodd-Frank Act.
The CFTC disagrees. It maintains that a futures contract does not require a fixed expiration date under the Commodity Exchange Act or existing regulatory interpretations.
The dispute began after the regulator approved Kalshi’s BTCPERP contract on May 29. The Bitcoin-linked product trades through KalshiEX, a CFTC-registered designated contract market.
As previously reported, the CFTC’s decision opened a regulated U.S. venue to Bitcoin perpetual futures after the products had largely remained on offshore cryptocurrency exchanges.
CME sued the regulator several weeks later. Its complaint seeks to vacate the Kalshi approval and the broader policy statement supporting the treatment of perpetual contracts as futures.
The central dispute concerns whether perpetual contracts legally qualify as futures or swaps. Each classification carries different registration, trading and oversight requirements.
CFTC defends its review of Kalshi’s contract
The CFTC reviewed Kalshi’s application under Regulation 40.3, which allows a designated contract market to request formal approval before listing a new product.
The agency concluded that the contract complied with the Commodity Exchange Act and CFTC rules. It also said perpetual designs may not be suitable for every asset and could require individual review.
CFTC Chair Michael Selig later rejected several criticisms directed at the decision. He said regulated perpetual contracts remain subject to domestic leverage, margin and customer protection requirements.
In related coverage, Selig argued that U.S. law does not require futures to carry fixed expiration dates. That interpretation now forms part of the broader legal dispute.
CME CEO Terry Duffy has criticized the approval process and warned that perpetual products could encourage excessive speculation. Kalshi has rejected that criticism and described the lawsuit as an effort to limit competition.
The companies’ statements represent opposing positions in active litigation. The court has not determined whether the CFTC followed the correct process or adopted the correct interpretation of the law.
CME response is due October 2
CME must file its opposition to the dismissal motion by Oct. 2. The CFTC has also requested an oral hearing, although the court will decide whether one is necessary.
The judge can dismiss the case on standing or other procedural grounds without resolving whether perpetual contracts are futures or swaps. Such a decision would leave the CFTC’s existing policy and Kalshi approval in place.
If the court finds that CME has standing, it could proceed to examine the substantive legal claims. Those claims include allegations that the agency misread the Commodity Exchange Act and acted arbitrarily under federal administrative law.
The case may also influence future applications from exchanges seeking to list perpetual contracts tied to cryptocurrencies, equities or commodities. Kalshi is reportedly preparing additional products, including a perpetual contract linked to WTI crude oil.
For now, Kalshi’s Bitcoin perpetual remains available under the futures framework. The CFTC’s dismissal motion begins the next stage of the case but does not settle the classification dispute.
Former Trump campaign chair Rob Arlett tells Al Jazeera’s ‘This is America’ that US President Trump is focused on protecting both the Republican Party and himself. Arlett argues Trump’s personal brand and ability to motivate voters remains central to the GOP’s midterm strategy.
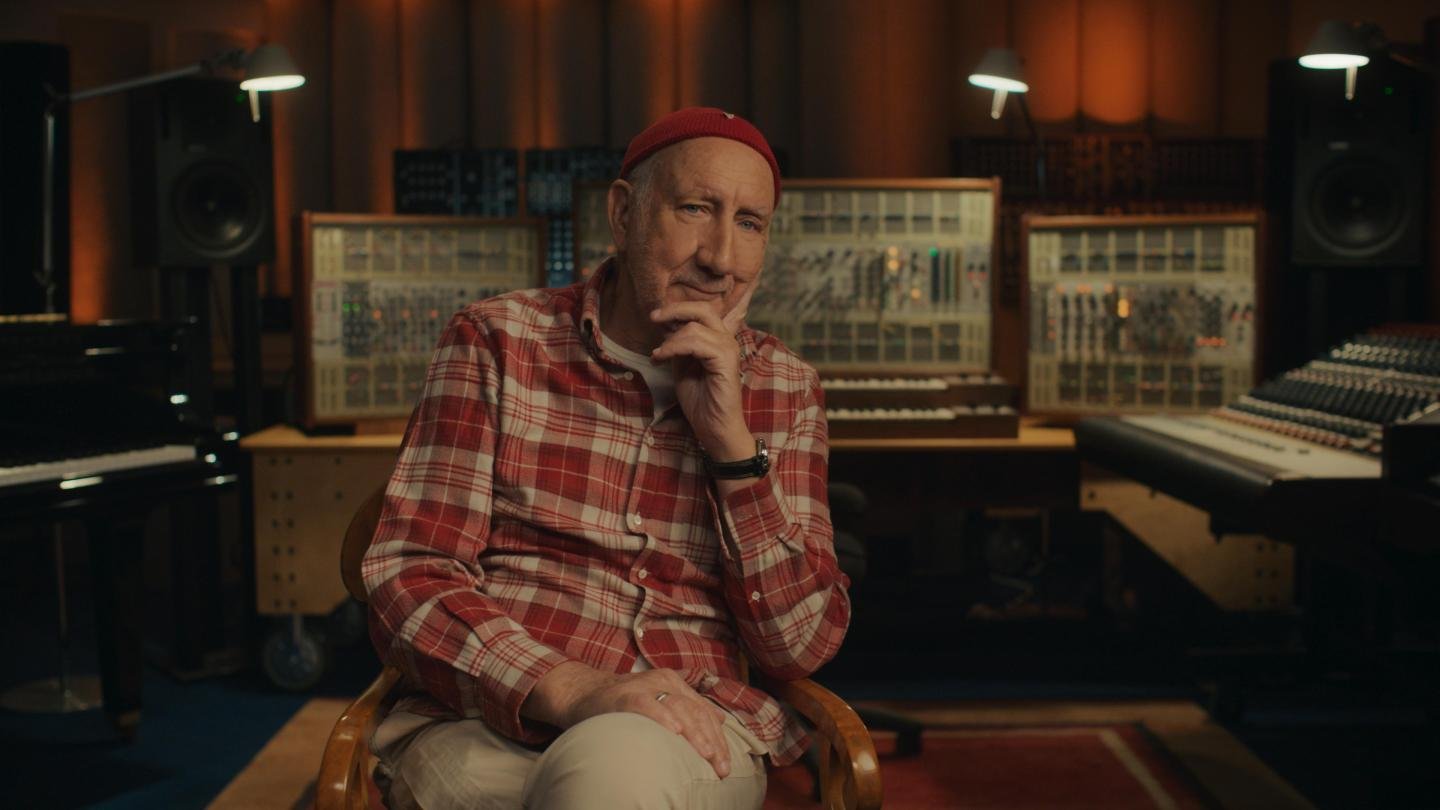
The legendary singer/songwriter Pete Townshend of The Who has cooperated with a documentary feature about his colorful life and career, and specifically about a time that almost destroyed him and his band: when, shortly after the release of the album Tommy, Townshend and The Who tried to make a science fiction rock opera called Lighthouse.
Behind Blue Eyes, which was co-directed by Frank Marshall and Nigel Sinclair, is headed to multiple fall film festivals as a sales title. The film’s backers — it was produced by Kennedy Marshall Documentaries, White Horse Pictures and VICE Studios, and is presented by Sobey Road Entertainment in association with Spirit Music Group, Polygram Entertainment and Trinifold Management — hope it will land a buyer and a spot in this season’s awards race.
Marshall and Sinclair exclusively discussed the film with The Hollywood Reporter.
What was it about Pete Townshend’s story — and specifically the story of Lifehouse — that made you feel this was a film that needed to be made now?
FRANK MARSHALL It’s a fascinating story and very compelling as a film now because the world has finally caught up with it. In 1971, no one could understand what Pete was talking about and he thought Lifehouse had failed. The irony is, 55 years later, we’re living inside his story.
NIGEL SINCLAIR And the other part of this is that Pete’s reached a point in his career and life where he is prepared to take a very intense look back at his creative process, with all its twists and turns; and that was captivating.
As you dug into this period of Pete’s life, what surprised you most about him or changed your understanding of the man behind the music?
MARSHALL I was surprised by how intellectual Pete is, his art school background and how he was trying to describe the future with technology. His solution wasn’t destroying technology, but human connection. He wanted to connect to the audience and bring them together through music. And out of that apparent failure came “Baba O’Riley,” “Won’t Get Fooled Again,” “Behind Blue Eyes,” “The Song Is Over” and other amazing music originally connected to Lifehouse.
SINCLAIR What surprised me was how self-aware he was from an early stage in his career. Discovering the link between his childhood torment and the character of Tommy was an extraordinary revelation. The other thing was the intense duality of his personality — the introvert and the extrovert, the rock superstar and the internal artist who wanted to be thought of as a writer not a rockstar.
Lifehouse emerged from a deeply personal crisis that nearly tore apart both Pete and The Who. How did you approach telling that story in a way that captures both the enormous musical ambition of the project and the personal stakes for Pete?
SINCLAIR Ironically, the enormous musical ambition of the project resulted in Who’s Next, which is easily the biggest album The Who released, groundbreaking, and often considered one of the top 10 rock albums of all time. In two days of interviews, Pete opened up his heart and explained how much Lifehouse was intended to reconcile the two sides of his personality, the rockstar and the artist. So its failure was heartbreaking then and, it appears so, now, as he tells it. So many of the later decisions Pete made about his career were so obviously driven by this “disaster.” And maybe from it came the wisdom that gave Pete a greater sense of fulfillment later, and made his relationship with Roger even more powerful.
What do you hope audiences come away understanding differently about Pete Townshend — and his place in music history — after seeing the film?
SINCLAIR Pete Townshend was one of the avatars who took rock and roll as a form of popular music and turned it into an anthem, a generational call to action, for then and for so many generations since. With Townshend, a select group — John Lennon, Bob Dylan, Ray Davies of the Kinks, and a little later David Bowie — gave the music, the lyrics and the performance of rock and roll the power to become an identity for millions and millions of people on earth. If Dylan changed the narrative with his The Times They Are a-Changin’ album, Pete turned it up to another level with the Tommy double album.
In the drama about progressive politics, religious faith, and the limits of tolerance, Reinsve and Stan play two fundamentalist parents who relocate from Romania to a small Norwegian village, only to find themselves accused of child abuse, and forced to defend their beliefs, and strict parenting style, in court. The film is in Romanian and Norwegian with substantial portions in English.
Reinsve, hot off her box office success with horror sensation Backrooms, starred in this year’s Best International Feature winner, Joachim Trier’s Norwegian melodrama Sentimental Value.
Fjord premiered in Cannes, where it won the Palme d’Or for best film. Neon snatched up the film for domestic release ahead of the festival. Under new Academy rules, the Palme d’Or win meant Fjordreceived automatic entry qualification for the Best International Feature category, whether Romania chose to pick it or not.
The film’s star power and its hot-button themes, as well as the Palme d’Or prestige, could help Mungiu secure his first-ever Oscar nomination. The Romanian director won the Palme d’Or back to 2007 victory with his breakout 4 Months, 3 Weeks and 2 Days, but that film was not put forward for the Academy Awards, triggering an outcry. His 2012 feature Beyond the Hills was Romania’s official Oscar pick and it made the shortlist, but did not secure a nomination. Fjord looks like a strong contender in this season’s race, not just for Best International Feature but in other categories, particularly Best Original Screenplay.
To date, the only Romanian film to be nominated for an Oscar is Alexander Nanau’s documentary Collective, about an investigation into hospital corruption in the wake of a nightclub fire. Collective was nominated for two Academy Awards, in both the Best Documentary and Best International Feature categories. A Romanian film has yet to win an Oscar.
The Academy of Motion Picture Arts and Sciences will announce the 15 films on the best international feature film shortlist on Dec. 15. The five nominees will be announced Jan. 21, 2027. The 99th Academy Awards ceremony will take place on March 14, 2027.
Cash Cat [$CASHCAT] is leading the memecoin sector by daily gains of more than 29%, resulting in a new peak of $0.30. The coin is the second largest by market cap on the Robinhood Chain, behind $PONS [$PONS].
$CASHCAT is the unofficial cat meme named after Robinhood’s discarded CashCat brand. This raises the question: why is the memecoin continuously making new highs?
Robinhood’s memecoin gold rush—$CASHCAT leads
The memecoin is driven by Robinhood Chain’s memecoin gold rush, sparking high trading activity.
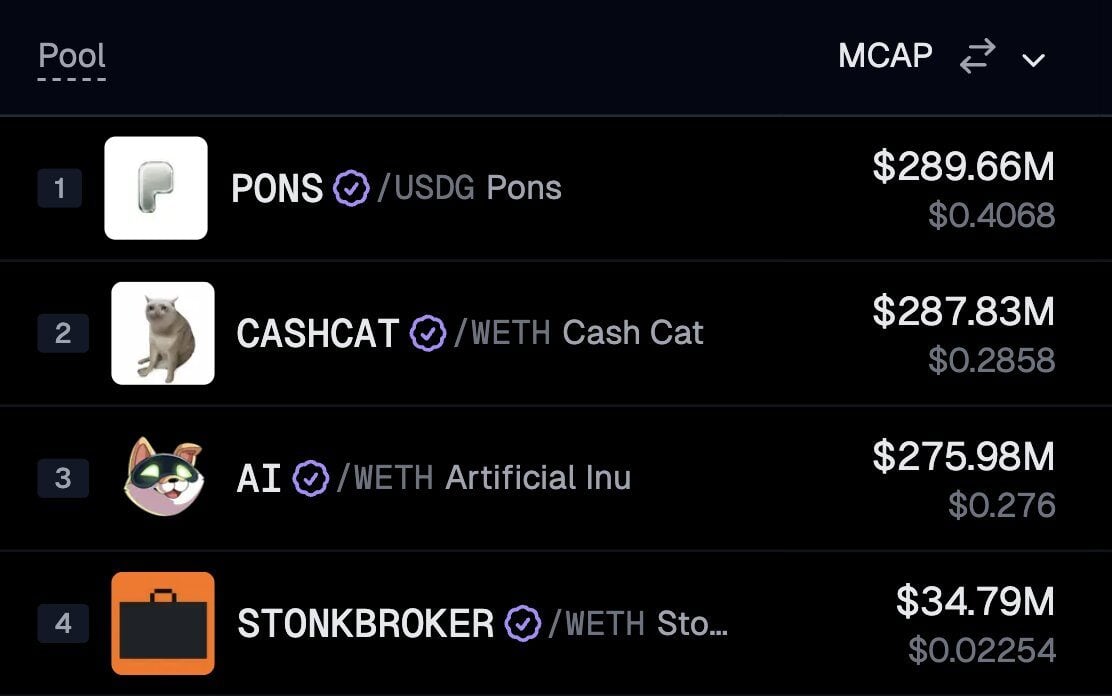
This frenzy is evident as the top three coins on the Robinhood DEX, that is, $PONS, $CASHCAT, and AI, have market caps exceeding $280 million. Each of them outweighs the fourth-ranked coin, STONKBROKER, by over 8x.
Source: GeckoTerminal
Moreover, Cash Cat is drawing liquidity from other cat-themed memecoins on other chains, such as BASECAT, which has a market cap of only $25 million. The Base Chain’s meme is more than 10 times smaller than $CASHCAT’s $287 million.
It has also outpaced OG cat memes like POPCAT, whose market cap is at $49 million.
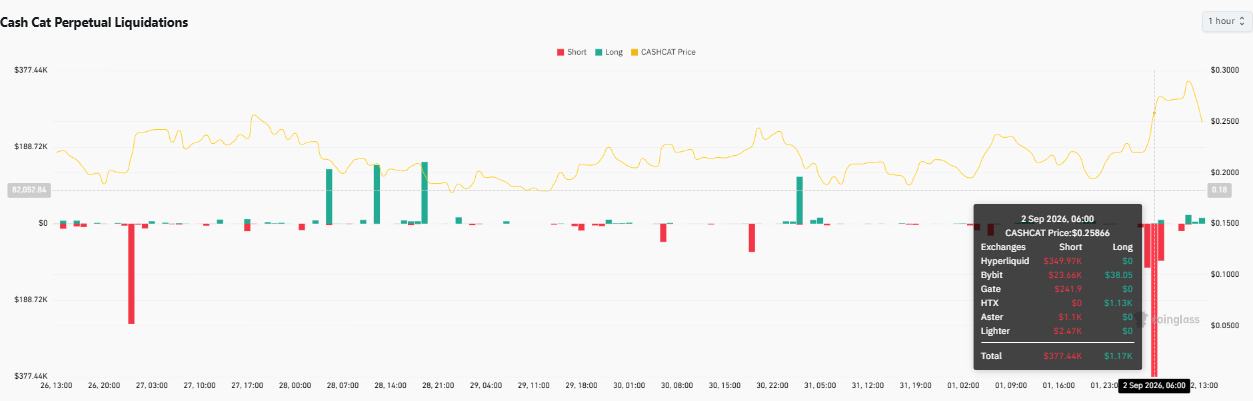
Apart from the hypon Robinhood fueling the memecoin, short liquidations over the past 24 hours have amplified the gains.
Over $377K in short orders was wiped out in under an hour. In total, more than $611K in short positions had been liquidated with a few hours left to close the day.
Source: CoinGlass
While the memecoin extended its weekly gains to over 40%, bulls appeared steady.
Can bulls keep $CASHCAT above the previous peak?
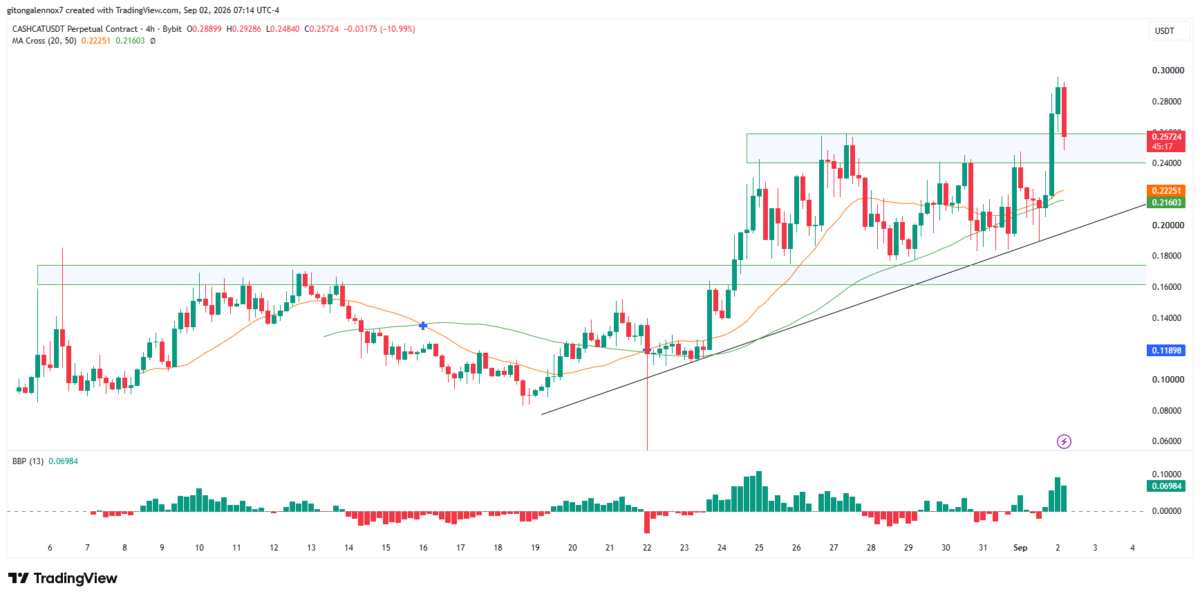
Overlying the price of the memecoin on a 4-hour chart showed a clear uptrend pattern. The new peak came after a week of consolidation between $0.17 and the previous high of $0.2592.
A consolidation around highs with sufficient momentum often hints at continuation. Now, $CASHCAT is testing the broken high, and if bulls keep it above this level, a new high may be formed again.
Otherwise, a breakdown may prompt a bigger correction. The coin’s next demand zone is at the $0.217-$0.225 zone, defined by the MA Cross indicator for the 20-day and 50-day MAs.
Source: $CASHCAT/USDT on TradingView
However, the trendline and horizontal support at $0.17 may act as more resilient support levels than those from MAs. Thus, the price might drop to these zones, but losing $0.17 may shift the market structure to bearish.
Interestingly, during the two recent sessions when candles were red, the bars of the Bull Bear Power (BBP) remained green. This reading reinforced that bulls were still present.
Final Summary
$CASHCAT rallies 29% in 24 hours, setting a new all-time high amid Robinhood Chain’s spike in trading activity.
$CASHCAT’s bulls held on to the coin’s strength with the last area of their defense against bearish control at $0.16.
Kraken is pulling 21 cryptocurrencies from trading. Trading and deposits end on September 11, 2026 at 14:00 UTC, withdrawals remain possible until December 10, 2026 at 15:00 UTC, and whatever is still sitting in the account after that the exchange sells itself between December 14 and 18. Anyone holding one of these tokens therefore has two windows: a short one for selling and a long one for withdrawing.
On September 3 we looked into where a withdrawal could actually lead. The result is the real reason for this article: at none of the three European venues we checked can any of these 21 tokens currently be deposited or traded. Moving to another exchange, the usual reflex in a delisting, leads nowhere here.
What Kraken announced on August 27 and which 21 tokens are affected
The notice carries the date of August 27, 2026 and names the affected assets only by their ticker: XTER, IR, GAIA, SCA, VANRY, BNC, SBR, RBC, MIR, JUNO, HDX, ACA, MULTI, RIZE, EPT, MAT, CQT, CXT, BKS, VULT and M. The exchange does not list full project names in this announcement, which makes identification harder for those affected, because several of these tickers are very short and therefore ambiguous.
The justification is brief. Kraken writes that several of the assets have limited or inactive markets, and attaches to that the warning that a later forced sale may fall considerably below recently observed reference prices. The notice makes no reference to European regulation, and there is no indication that this step has anything to do with MiCA. It is a clean-up of the exchange’s own line-up.
Delisting, trading halt and forced liquidation: each term in a single sentence
A delisting is an exchange’s decision to remove an asset permanently from its own line-up. A trading halt is the point from which that asset can no longer be bought or sold on the platform, while the balance remains in the account. A forced liquidation is the sale of a remaining balance by the exchange itself, after the withdrawal deadline has passed and the customer has not responded.
At Kraken these three steps run at different times, and that is exactly where the practical trap lies. After September 11 the account looks unchanged: the balance is still there, nothing disappears, and no second warning arrives. Only the sell button is missing.
The three dates: September 11, December 10 and the liquidation week
The first date is the most important, because it forces the one decision for which there is no later substitute. On September 11, 2026 at 14:00 UTC, Kraken switches off trading and deposits for all 21 assets. Anyone who sells by then has euros or dollars in the account and need not worry about anything further.
The second date, December 10, 2026 at 15:00 UTC, ends withdrawals. Until then the balance can be transferred to an address of your own. After that comes the third step: between December 14 and 18 Kraken sells all remaining holdings. The proceeds are credited to the account, but in the same notice the exchange makes clear that because of thin order books they can fall considerably below the most recently quoted prices and in individual cases turn out minimal or zero.
Three months sounds like a lot of time, and it is, as long as the withdrawal works technically. But anyone who only notices in December that the destination address does not fit or that the network is not supported has been without the trading route as a fallback for three months already.
A single compartment is still open: for the 21 delisted tokens, none of the European venues we checked offered an active deposit route.
Our September 3 survey: no second trading venue in Europe
This analysis was carried out by cryptoticker.io itself on September 3, 2026. We retrieved the publicly available asset and trading pair directories of four venues and held the 21 tickers from the Kraken notice against them. Kraken itself, Bitvavo, Coinbase and Bitstamp were queried, each retrieval with status code 200. That amounts to 21 tokens checked against 4 venues.
The result is clearer than we had expected. Across Bitvavo, Coinbase and Bitstamp combined, not a single one of the 21 tokens had an active trading or deposit route. Two tickers appear in Bitvavo’s directory at all, VANRY and ACA, but both carry the status «delisted» there, for deposits as well as withdrawals. Coinbase lists MIR as Mirror Protocol and MULTI as Multichain, both likewise with the status «delisted». At Bitstamp not a single ticker carries an active trading pair.
That overturns the usual course of action in a delisting. The advice to simply push the holding to another regulated exchange assumes that this exchange accepts the asset. For these 21 assets none of the venues checked does. Anyone reorienting themselves on the choice of trading platform anyway will find the providers available in Germany together with their terms in our comparison of the best crypto exchanges; for the tokens affected here, however, that changes nothing about the situation.
Why a delisting at Bitvavo, Coinbase and Bitstamp blocks the move
A deposit needs an active deposit address on the receiving side. If an asset carries the status delisted at an exchange, it no longer generates that address. Anyone transferring regardless, to an old address from the clipboard for instance, sends their balance to a place where nobody assigns it any more. Such cases regularly end up in support, often without result.
The second point concerns sequence. Even if a platform were to relist one of these assets in future, that no longer helps after December 10, because by then Kraken has closed withdrawals. The question of where the holding should go therefore has to be answered before the December date, and the only answer that depends on no outside decision is your own wallet.
19 of the 21 tokens still have a euro pair, two only a dollar pair
We counted this too on September 3. All 21 assets are still listed as tradable on Kraken at the time of our query, and 19 of them carry a direct trading pair against the euro. There are two exceptions: SCA and RBC are only tradable against the US dollar. Anyone wanting to sell these two therefore goes via the dollar and bears the conversion, which for small holdings shrinks the proceeds further.
The number of trading pairs per asset is consistently low, at one or two pairs. That is the measurable side of what Kraken means by limited or inactive markets: where only one pair exists there is only one order book, and a sell order quickly meets little on the other side.
Sell or withdraw: the decision due by September 11
The decision has two routes, and the deadline separates them cleanly. Until September 11 both are open. After that only one remains.
Route one: sell while the order book is open
Anyone who did not want to hold the asset anyway sells it on Kraken before the deadline. With thin order books it is worth setting a limit order rather than a market order and, if necessary, disposing of the holding in parts over several days, because a large market order in an empty book drags your own execution price down.
Route two: withdraw and hold in self-custody
Anyone wanting to stick with the project transfers the holding to an address whose keys they hold themselves. That can be a software wallet or a hardware device; which devices are available in Germany and what distinguishes them is set out in our comparison of hardware wallets. What matters above all is that the wallet really supports the network in question, because several of these tokens run on chains that common wallets do not carry out of the box.
Before the large transfer, a small test amount always belongs sent and confirmed at the destination. That minute costs fees and prevents the mistake that cannot be undone.
Self-custody as the only route left for the 21 tokens
According to our survey, for these 21 assets your own wallet is not one option among several but the only one that reliably works. That has a side effect which belongs with the deadline: a self-custodied token for which there is no longer a regulated trading venue in Europe can be held, but for the time being it can no longer readily be turned into euros. Anyone withdrawing is therefore deliberately choosing a holding with no foreseeable exit.
Nobody can take that weighing-up off your hands, and it comes out differently for a holding of a few euros than for a larger one. For completeness: doing nothing is a decision too, it merely leads to the forced sale in December at a price Kraken itself does not guarantee.
Kraken describes the proceeds of the forced liquidation in its own notice as possibly minimal or zero.
Why the liquidation proceeds can be minimal or zero according to Kraken
The wording comes verbatim from the exchange’s notice: the proceeds may fall considerably below recently observed reference prices and in individual cases turn out minimal or zero. That is not rhetorical hedging but the logical consequence of the procedure. In one fixed week in December, Kraken sells all remaining holdings of all affected customers into the same order book that was already described as thin beforehand. Supply and demand are in no balanced relation there.
For the individual investor that means the price a quote portal shows today for one of these tokens says little about what is actually credited in December. Anyone relying on that displayed value and waiting for that reason is planning with a number that no longer holds at the time of execution.
Tax consequences of the forced liquidation: a disposal without your own decision
A forced sale is for tax purposes a sale like any other. Under section 23 of the German Income Tax Act, gains from the sale of cryptocurrencies remain tax-free if more than a year lies between acquisition and disposal; within that period an exemption threshold of 1,000 euros per calendar year applies, and once it is exceeded the entire gain becomes taxable.
The awkward thing about the forced liquidation is that it dictates the moment of sale. Anyone who bought a token eleven months ago would have reached the one-year mark by waiting; the liquidation in December takes that possibility away. For anyone who passed the deadline long ago, the process is unproblematic for tax purposes. A loss from such a sale can be offset within the same category of income, which given the proceeds to be expected here is likely to be the more common case in practice.
For any of that to be documented at all, the acquisition data is needed. Anyone no longer holding it should export the transaction history from the Kraken account while the account is still complete. Tools that read this data and track the deadlines per position exist both as pure tax programmes and as portfolio trackers with a tax function. This section describes the legal position and does not replace tax advice in an individual case.
Distinguishing this from the August delisting wave: why this is a different list
Kraken has removed assets several times this year, and the dates overlap. Our article of August 14, 2026 on the 56 tokens facing forced liquidation describes three parallel cycles from May, June and July with deadlines on August 27, September 25 and November 6. The list dealt with here is entirely separate from those: none of the 21 tickers from the August 27 notice appears in those cycles.
So anyone who read the earlier article and checked their account at the time is not done with this check. The September 11 and December 10 dates belong to a new announcement, and they concern different assets. This accumulation is itself a finding: anyone holding smaller tokens at an exchange now has to look at its notice page regularly, because a single check is only a snapshot.
How to check your Kraken account for affected tokens in five minutes
The quickest route runs through the account’s balance overview. All positions are listed there with their ticker, and comparing them against the list above is a pure text check. What matters is looking at the very small holdings too, the ones that accumulate over the years, because it is precisely those that often sit in exactly these obscure assets.
After that a look at Kraken’s own announcement belongs in the process, because that is where any change to the dates would appear. If a position turns up on the list, it comes down to a single question: sell or withdraw. Anyone finding nothing has nothing to do, but should not have to make a note of September 11.
One aside, because it concerns the same account: very small amounts that cannot be explained are not always old holdings from your own purchases. Anyone finding a position on the list they do not remember should take a quick look in the transaction history before selling, to see where it came from.
How we surveyed and what we could not check
On method: on September 3, 2026 we called the public interfaces of four trading venues, read out the assets and trading pairs listed there and compared the 21 tickers from the Kraken notice against them automatically. Only disclosures from the venues themselves were evaluated.
Four points we could not settle, and they belong to the honesty of this analysis. First, Bitpanda’s directory could not be retrieved, the interface answering with an access block; our survey therefore says nothing about that offering. Second, we deliberately left out decentralised venues, because they place different requirements on the user and cannot sensibly be compared with an exchange account. Third, several of the tickers are very short, such as M, IR, MAT or SCA; an identical ticker at another venue can denote a different project, which is why we treated every hit only as a possible and not as a confirmed match. Fourth, we collected no trading volumes, so on actual market depth we only reproduce what Kraken writes about it itself.
What we did not do: no extrapolation to monetary values, no price figure for any of the tokens, no statement about how many investors are affected. For none of these figures do we have a reliable basis.
Checking the Kraken trading halt: what to take away
Compare your account today. Hold the 21 tickers against your own balance overview, very small holdings included. Anyone wanting to switch will find the alternatives in our comparison of crypto exchanges.
Decide by September 11. Sell while an order book exists, or deliberately hold and withdraw. The second route needs a wallet that carries the network; the devices are in our hardware wallet comparison.
Secure your records before the account empties. Export the transaction history and note the acquisition data, so that the deadline and the gain can be documented later; suitable tools are in our tax and portfolio overview.
(As of September 3, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Andrew Garfield isn’t ready to reach out to Tom Holland about the massive success of “Spider-Man: Brand New Day” or “The Odyssey,” for that matter.
For good reason — he hasn’t seen either film.
“I don’t want to be disingenuous,” Garfield told me Wednesday at the premiere of his historical action drama “The Uprising” at the DGA in West Hollywood. “A movie making money and people going to see it is an incredible thing, but I will reach out to him once I’ve seen [“Spider-Man”], which I’m very excited to see. And his other film, ‘The Odyssey,’ I haven’t managed to see either yet. I will send him a message when I see the work he has done.”
Andrew Garfield says he hasn’t congratulated Tom Holland on the success of “Spider-Man: Brand New Day” because he hasn’t seen it yet: “I don’t want to be disingenuous.” pic.twitter.com/t6XiDezh3y
Garfield, who played the web-slinger in two Spidey movies and reprised his role in “Spider-Man: Now Way Home” alongside Holland and fellow former “Spider-Man” star Tobey Maguire.
But Garfield isn’t surprised that “Spider-Man: Brand New Day” has made a staggering $891 million at the domestic box office and is predicted to become the first movie to make $1 billion in North America alone.
“Everyone has ownership over him, he’s everybody’s, and he’s decent and he’s good and he’s ordinary, and he’s extraordinary like all of us,” Garfield said. “It’s impossible not to see yourself in that character.”
I reminded him that he has a reputation for not telling the truth because he lied about not being in “No Way Home.” “You’ll find out, I suppose, one way or another,” Garfield said, smiling.
In Paul Greengrass’s “The Uprising,” Garfield plays a fictional character who becomes a leader during a rebellion of thousands of commoners against King Richard II in 1831.
Director Paul Greengrass told me Garfield insisted on doing most of his own stunts for the film’s many fight scenes. “He allowed me and what my could manage,” Garfield said. “I’m not a young guy anymore. It was a lot of ice packs on the knees.”
See more photos from “The Uprising” premiere below.
Thomasin McKenzie, Woody Norman, Katherine Waterston and Andrew Garfield at “The Uprising” Los Angeles Premiere held at DGA Theater on September 02, 2026 in Los Angeles, California. (Photo by Gilbert Flores/Variety via Getty Images)
Variety via Getty Images
Andrew Garfield, Woody Norman and Paul Greengrass at “The Uprising” Los Angeles Premiere held at DGA Theater on September 02, 2026 in Los Angeles, California. (Photo by Gilbert Flores/Variety via Getty Images)
Variety via Getty Images
Jason Blum, Thomasin McKenzie, Joanna Kaye, Paul Greengrass, Andrew Garfield, Katherine Waterston and Gregory Goodman at “The Uprising” Los Angeles Premiere held at DGA Theater on September 02, 2026 in Los Angeles, California. (Photo by Gilbert Flores/Variety via Getty Images)
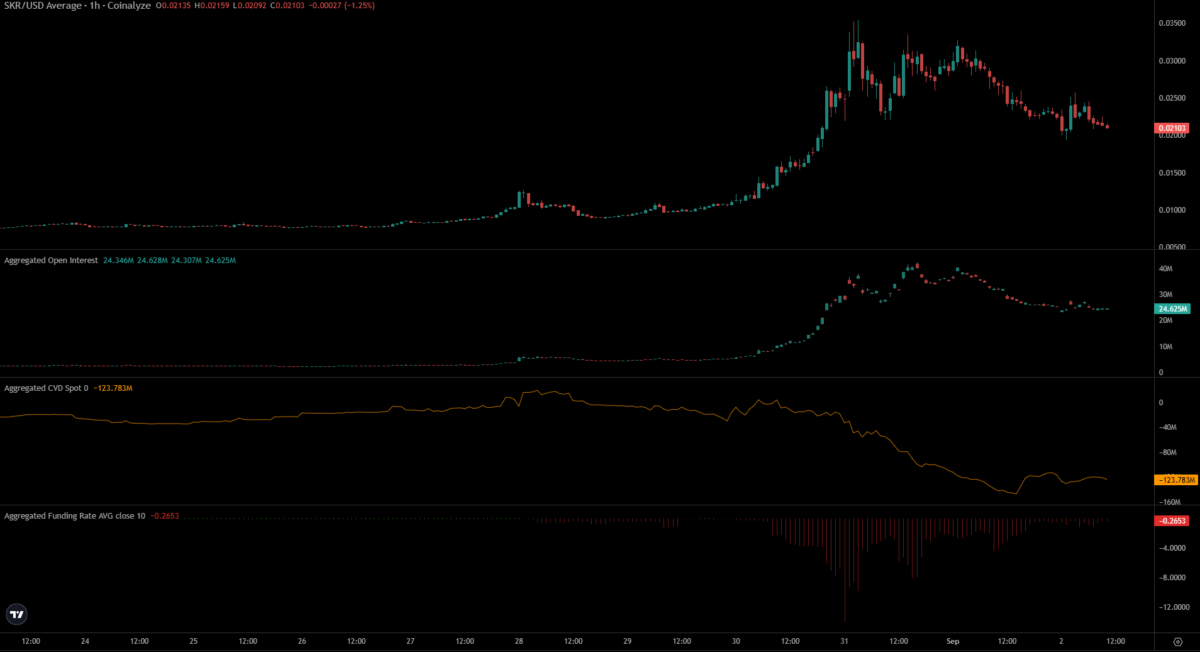
Seeker [$SKR] violently squeezed short positions with its 292% rally from $0.091 to $0.359 last weekend. Since making this swing high, the altcoin has faced selling pressure from profit-taking activity.
Source: Coinalyze
The native utility and governance token has witnessed negative Funding Rates in recent days. Extreme negative values and falling spot CVD signaled intense selling pressure on the 31st of August following the rally.
It reflected market conviction that the rally was about to end. The Open Interest has slumped from $42 million on Monday to $24.6 million at the time of writing. Market participants have taken profits and exited the derivatives market.
A retracement phase was underway. Here’s how low $SKR prices can fall to and where buyers might re-enter.
Bullish breakout confirmed, but another 40% $SKR dip possible
Source: $SKR/$USDT on TradingView
In the past 24 hours, Bitcoin [BTC] has shed 1.88%, falling from $78k to $76.6k. This minor correction toward the local $76k support zone helped explain why $SKR faced losses in recent trading hours.
The bigger reason is that $SKR was highly overextended after its rally towards the end of August.
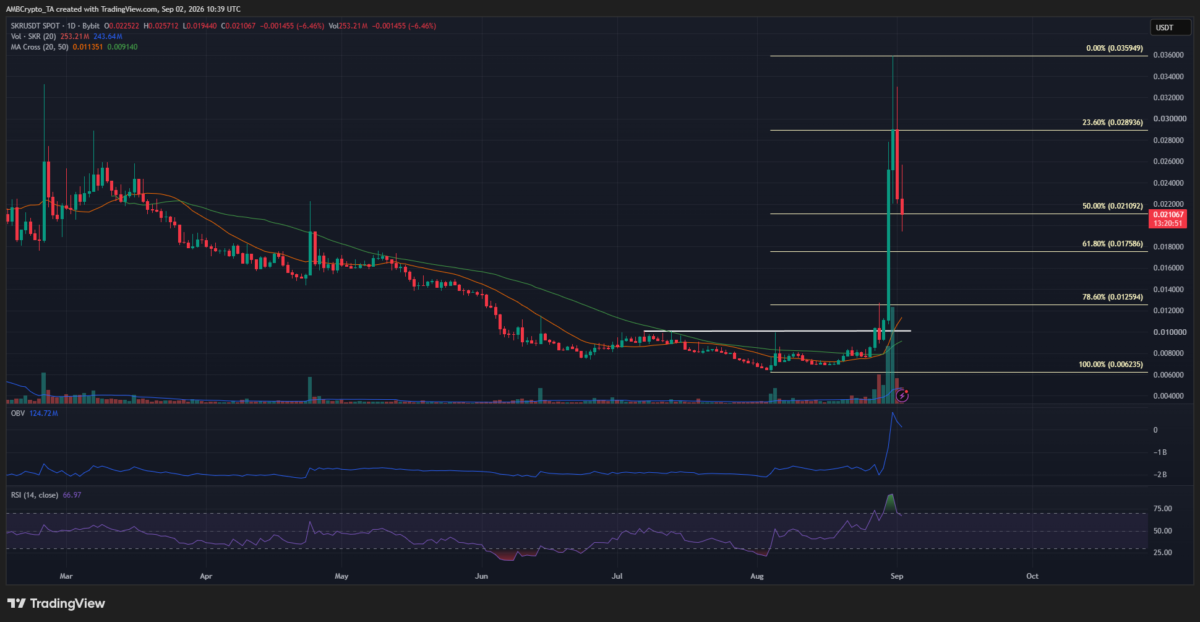
The rally in question broke the previously bearish trend. The $0.10 swing high from early July was decisively breached. Seeker bulls didn’t give the others any time within a consolidation to accumulate the token.
Instead, they drove a price move to $0.36, the highest the altcoin’s price has reached since February.
The bullish swing structure was used to plot a set of Fibonacci retracement levels (yellow). The golden pocket between $0.0126 and $0.0175 is likely to be tested before another rally.
Traders’ call to action – Be cautiously bullish
Source: $SKR/$USDT on TradingView
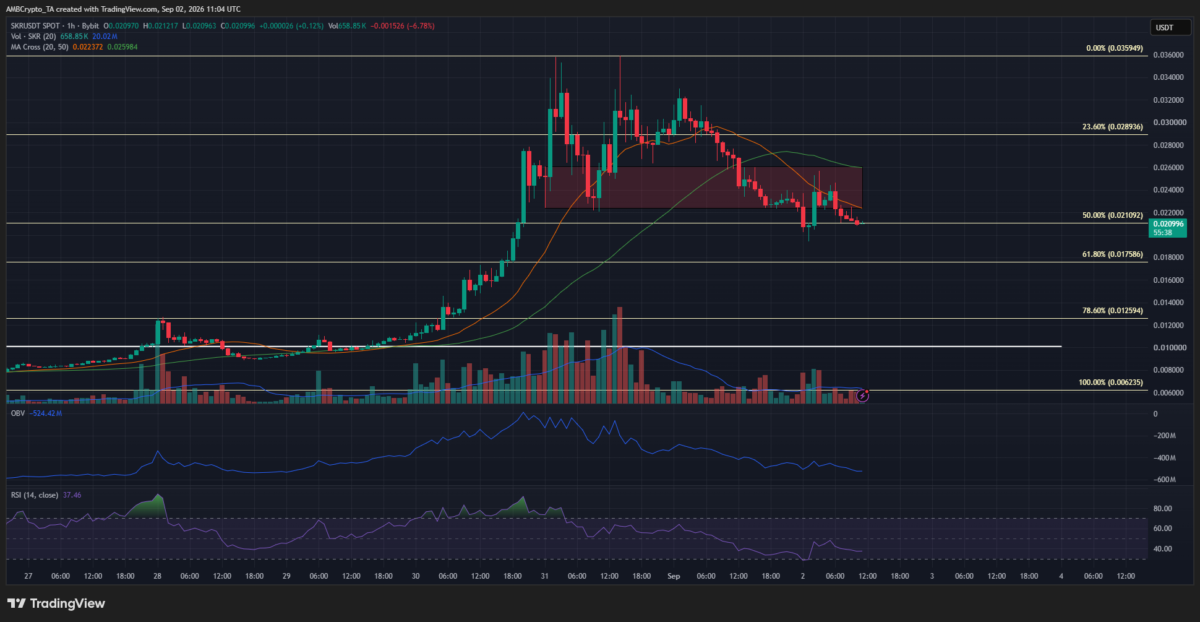
Seeker is a relatively small-cap token that has made a remarkable rally. It was retracing swiftly, and the Coinalyze data from earlier showed short-term bearish conviction.
The 1-hour chart showed that the $0.024 former support zone has been flipped to resistance over the past 48 hours. The RSI was below neutral 50, and the OBV was rapidly sinking, highlighting bearish momentum and heavy selling.
A dip to the $0.0125-$0.0175 is likely to be met with a reaction from the buyers. However, if Bitcoin continues its descent, it could spook the market and possibly upset the uptrend $SKR has established.
Final Summary
Seeker faced sizeable profit-taking pressure after the weekend’s rally and was in a retracement phase.
The current price dip could extend by another 40% if the price reached the 78.6% retracement level at $0.0125.
If you purchase an independently reviewed product or service through a link on our website, The Hollywood Reporter may receive an affiliate commission.
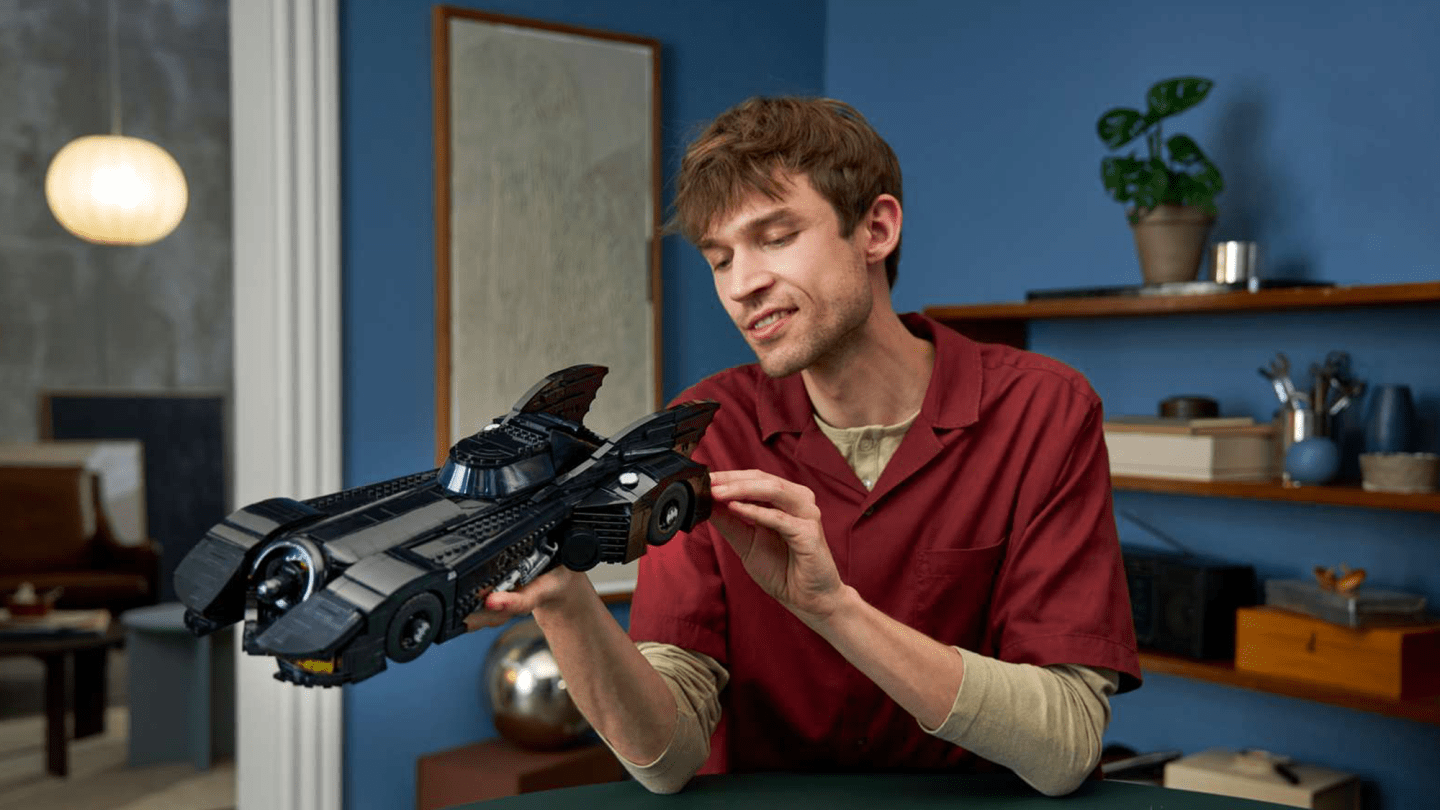
Lego Insiders got early access beginning Sept. 1, while the set becomes available to everyone on Sept. 4 for $229.99. The release arrives two decades after Lego launched its dedicated Batman range in 2006, initially with seven sets based on the titular character and his world. Since then, the company has made several vehicles, including The Dark Knight Tumbler and the 1995 Batman Forever Batmobile.
Lego
First of its kind
‘Batman Returns’ Batmobile Lego
Early Access for Lego Members
A clever transformation reveals the Batmissile tucked away inside the vehicle.
The 18-and-up set measures more than 17 inches long and includes six hidden Easter eggs, including The Penguin’s tracking device. Its headline feature is a button-activated transformation that drops the Batmobile’s side panels to reveal the Batmissile escape vehicle. The set includes an exclusive Batman minifigure with a newly molded cowl and cape, plus a dedicated Batman Returns display stand.
Lego
For longtime Lego Batman collectors, the significance of this release extends beyond the car itself. The company’s Batman catalog has grown from those seven inaugural 2006 sets into a sprawling archive of vehicles that have become sought-after display pieces.
For instance, Lego’s 1989 Batmobile that arrived in 2019 is now a retired product, but third-party sellers are offering up the collectible online for over $500, while the sold-out 2024 Classic TV Series Batmobile is going for over $250 on eBay.