Tag: CRYPTOS FoxBusiness

  • A $1.1 million crypto card hack crashed a neobank’s token 49%

    A $1.1 million crypto card hack crashed a neobank’s token 49%

    A vulnerability in an outdated Rain card contract drained roughly $1.1 million across several Solana-based programs, including $500,800 from 1,685 Avici users, sending the neobank’s AVICI token down as much as 49%.

    AVICI — a self-custodial neobank that enables users to spend their crypto via a Visa-integrated credit card — fell from a 24-hour high of $0.43 to a record low of $0.217 before recovering to around $0.378 at the time of writing.

    Tria, another crypto neobank, reported that 636 users were affected, resulting in losses totaling more than $430,000. It vowed to repay users in full, even as its token plunged by more than 10% at one point.

    Avici said the attack was confined to a Solana contract holding funds after customers topped up their cards. Its self-custodial wallets on Solana and Ethereum-compatible networks were not affected, and the company said every affected card balance would be refunded.

    Rain said its monitoring identified the vulnerability in an outdated contract version used by Avici and a small number of other programs. It upgraded every program running that version and reported no further unauthorized activity.

  • Renowned Economist Harshly Criticizes the Fed’s Latest Policies: “They’re on the Wrong Track”

    Renowned Economist Harshly Criticizes the Fed’s Latest Policies: “They’re on the Wrong Track”

    Economist James E. Thorne criticized the Federal Reserve’s tight monetary policy against inflation, arguing that interest rate increases may be insufficient to address the root causes of current price pressures. According to Thorne, Fed Chairman Kevin Warsh and Wall Street circles view supply-driven inflation as a classic overheating problem stemming from excess demand.

    Thorne stated that high inflation is not solely caused by strong consumer demand; energy costs, housing shortages, production cuts, and other supply constraints also play a significant role. Therefore, he argued that further interest rate increases, instead of reducing inflation, could weaken the economy’s productive capacity.

    Employment Data Does Not Support the “Overheating” Thesis

    Thorne specifically drew attention to the decline in quarterly full-time employment data. The economist stated that this decline could be a sign of the structural transformation the economy is undergoing, rather than just a one-month statistical anomaly, and that the fact that a significant portion of the decline stemmed from public sector employment did not diminish the significance of the situation.

    According to Thorne, this view indicates not so much that the economy is overheating, but rather that the labor market is adapting to changing fiscal policies, industrial structure, and institutional conditions.

    Thorne argued that the housing sector was sending a similar message, stating that the housing market, one of the sectors most sensitive to interest rates, was directly feeling the pressure of tight monetary policy rather than creating inflation.

    Thorne argued that the recent growth in the US economy could be explained not by widespread, credit-fueled overheating, but rather by the initial results of the Trump administration’s supply-side economic policies and a long-term investment cycle.

    Thorne, particularly highlighting the increase in investments in artificial intelligence, data center and computing capacity, electricity generation, and infrastructure, stated that these investments have the potential to increase the production capacity and efficiency of the economy.

    According to the economist, further interest rate increases by the Fed during this period, instead of controlling inflation, could make it more difficult to finance productive investments, hindering future expansion of supply capacity.

    “Customs Duties Are Not the Same Thing as Persistent Inflation”

    Thorne also added that, according to classical economic theory, real supply shocks should lose their effect over time as prices and production adjust.

    Thorne noted that a shock in oil prices does not necessarily require permanently high interest rates, and that tariffs can also create a one-time increase in the price level, but this is not the same as a self-reinforcing, continuous inflationary process.

    Thorne also argued that there is no strong evidence to suggest that the neutral real interest rate, considered a stabilizing factor in the economy, or “r*” level, has risen by approximately 100 basis points in a short period of time.

    According to Thorne, the fundamental question for the Fed is whether further tightening of monetary policy is appropriate while full-time employment is declining and the housing sector remains under pressure.

    The economist said that under current conditions, new interest rate hikes might represent less of “prudent inflation control” and more of a deliberate suppression of demand as a result of supply constraints and a misjudgment that an economy undergoing structural transformation is overheating.

    *This is not investment advice.

  • Zcash’s 19x Rally May Have More Room as Grayscale Eyes Bitcoin Share

    Zcash’s 19x Rally May Have More Room as Grayscale Eyes Bitcoin Share

    Grayscale Sees More Room After Zcash’s 19x Rally

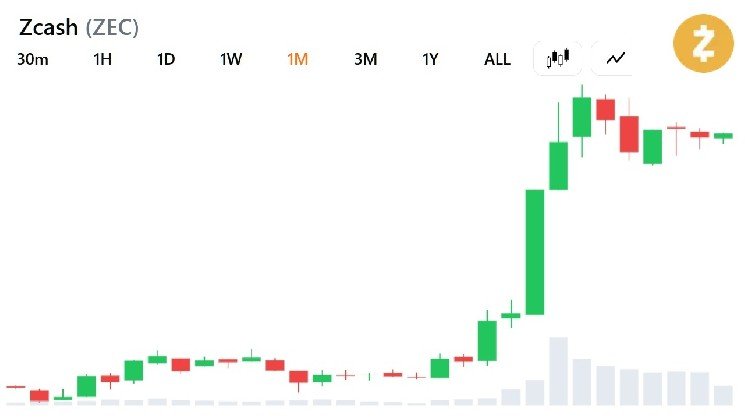
    Zcash may have further upside despite rising approximately 19-fold over the past year, according to Grayscale Head of Research Zach Pandl. The asset manager said Aug. 25 that Zcash could challenge Bitcoin’s network effects through capabilities that were unavailable or less relevant when Bitcoin established its lead.

    Grayscale’s “Currencies” sector groups crypto assets primarily designed to serve as digital money or stores of value. Bitcoin accounts for 93% of the category by market capitalization. The asset manager identified financial privacy, development addressing cybersecurity threats, and cross-chain reach through intents technology as Zcash’s potential advantages.

    “Zcash offers financial privacy and other attributes that users may find essential in an age of AI,” Pandl wrote, adding:

    “We think it is still undervalued and can continue to capture market share.”

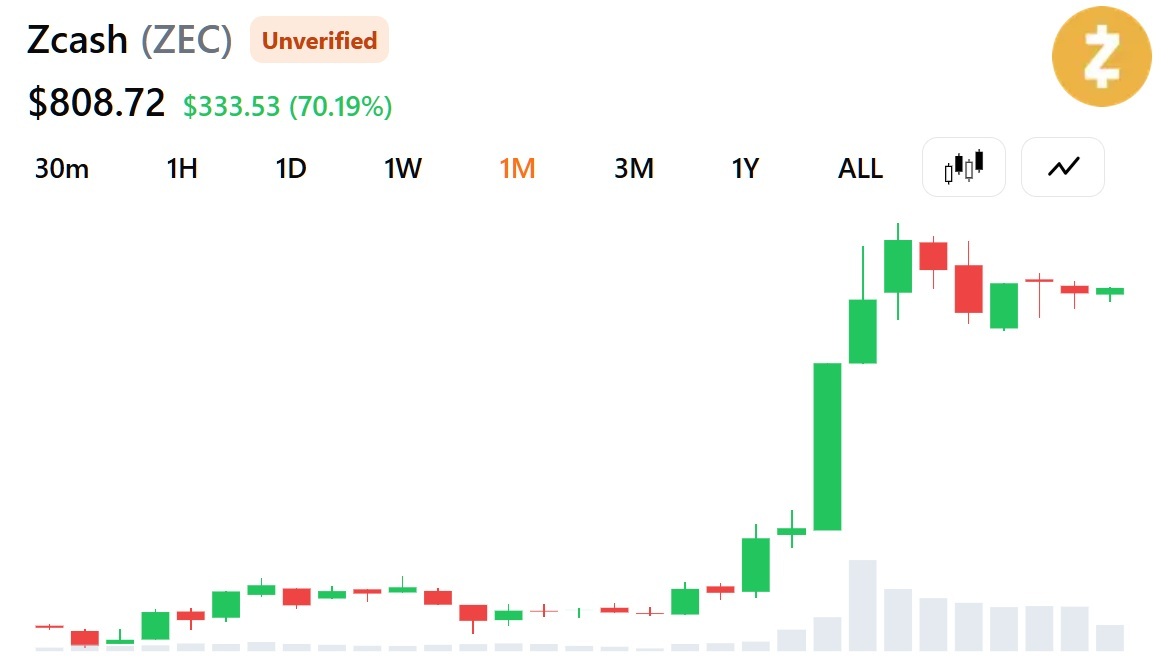
    $ZEC’s price as of Aug. 29 via Bitcoin.com Markets

    Bitcoin’s Market Cap Remains 114 Times Larger Than Zcash’s

    $ZEC remained valued at less than 1% of bitcoin’s market capitalization after its rally sharply improved Zcash mining economics. Grayscale said the disparity could indicate that investors are underpricing Zcash’s features, although it emphasized that $ZEC remains a smaller, more volatile, and higher-risk cryptocurrency.

    As of Aug. 29, bitcoin ranked first among all cryptocurrencies with a market capitalization of $1.56 trillion, while Zcash ranked 11th at $13.74 billion. $ZEC’s market capitalization equaled approximately 0.88% of bitcoin’s, leaving $BTC about 114 times larger.

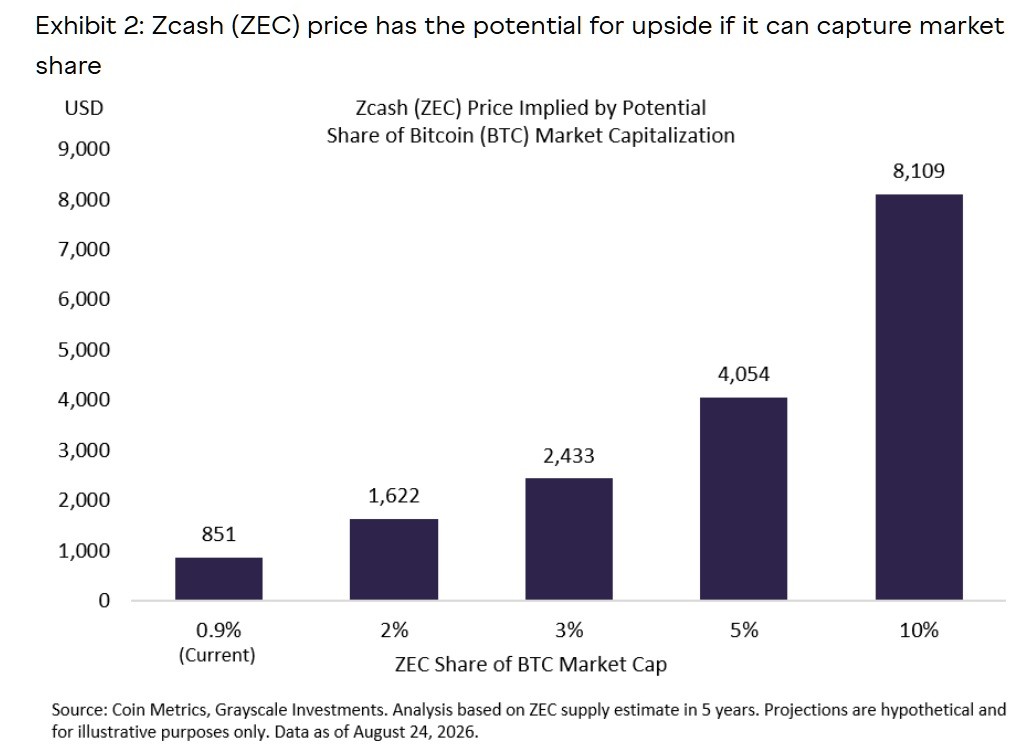
    Grayscale calculated how $ZEC could perform if it captured a larger share of bitcoin’s market capitalization over five years. Based on estimated $ZEC supply, the scenarios imply prices of $1,622 at 2%, $4,054 at 5%, and $8,109 at 10%. The figures are hypothetical, not price forecasts.

    Potential $ZEC prices at different shares of bitcoin’s market cap. Source: Coin Metrics and Grayscale Investments; Aug. 24, 2026.

    AI Surveillance Could Strengthen the Privacy Case

    Artificial intelligence could make financial surveillance more effective by connecting public addresses with exchanges, counterparties, wallet behavior, and transaction histories. Grayscale’s Aug. 19 Zcash financial privacy analysis argued that AI and blockchain adoption could create another wave of public concern about financial confidentiality.

    Intents technology lets a wallet coordinate cross-chain transactions based on the user’s desired result, such as converting another digital asset into $ZEC. This allows users or AI agents to access Zcash’s privacy features without merchants accepting $ZEC directly.

    In some respects, Zcash resembles Bitcoin through its proof-of-work security model and fixed supply of 21 million coins. Unlike Bitcoin, the network supports shielded transfers that conceal transaction details using zero-knowledge proofs. These transfers reflect how privacy coins use cryptographic techniques to obscure transaction details, including the sender, recipient, or amount.

    Market access expanded Aug. 25 when Grayscale’s Zcash ETF began trading on NYSE Arca under the ticker ZCSH. The fund moved from OTCQX quotations to NYSE Arca, giving investors spot $ZEC exposure through a publicly traded vehicle without requiring them to purchase the cryptocurrency or manage wallets and private keys directly.

    Privacy Use and Network Development Build Momentum

    Grayscale said in March that privacy and growing network momentum could help $ZEC compete with $BTC. Its March 18 comparison of Zcash and Bitcoin pointed to increasing use of shielding technology and new capital supporting wallet development and Zcash mining.

    Pandl wrote:

    “Zcash, a privacy-focused digital currency, is the Bitcoin competitor with the best shot at capturing market share over time, in our view.”

    Development carries security and execution risks alongside potential benefits. The Zcash Foundation patched two Zebra vulnerabilities involving a critical remote denial-of-service flaw and a high-severity potential chain-split flaw during the first quarter.

  • Zcash (ZEC) Social Buzz Vanished Before Its ETF Even Launched: Data

    Zcash (ZEC) Social Buzz Vanished Before Its ETF Even Launched: Data

    Zcash has been one of the best-performing assets this year. It has managed to attract significant institutional capital. This week, asset manager Grayscale Investments launched the first exchange-traded fund that tracks the spot price of $ZEC.

    But interest in the privacy-focused token peaked shortly before its price reached a recent high.

    Zcash Crowd Showed Up Early

    Data shared by Santiment revealed that social chatter faded by the time the $ZEC spot ETF launched. Grayscale converted its 2017 Zcash trust into a spot ETF, which began trading on NYSE Arca on August 25.

    Ahead of the launch, the asset climbed from around $509 on August 18 to about $878 on August 23, posting a gain of roughly 72%. Social mentions reached 232 on August 22, which is around six times the usual August baseline. However, that surge in attention did not last.

    Mentions had returned to their baseline level by the ETF’s launch day. According to Santiment, social activity peaked one day before $ZEC’s price high, which suggested that much of the crowd interest arrived ahead of the market’s high.

    Since reaching about $878, the token has pulled back to roughly $789, a decline of around 10% from the recent peak.

    Zcash Challenging Bitcoin?

    Grayscale Research believes $ZEC could emerge as a serious challenger to Bitcoin’s network effects as demand for financial privacy grows. In a report by Head of Research Zach Pandl, the firm said Bitcoin remains dominant among digital currencies. While alternatives such as Litecoin have emerged, none has seriously challenged BTC’s position.

    Grayscale, however, stated that Zcash could be different because it combines Bitcoin-like characteristics with privacy features that may become more important as AI-powered surveillance expands. The report also points to the ecosystem’s active development, which aims to address cybersecurity risks, including potential threats to traditional cryptography from quantum computing.

    Another advantage is its cross-chain reach through “intents” technology built into modern blockchain wallets, which allows Zcash to function as a private asset hub without requiring broad merchant adoption. $ZEC has already gained around 19 times over the past year but remains worth less than 1% of Bitcoin’s market capitalization. Grayscale said Zcash’s financial privacy and other features may be undervalued, thereby leaving room for further upside.

  • Will the Fed Raise Interest Rates in September? The Latest Probability Figures Are In

    Expectations that the Fed may raise interest rates at its September meeting have risen significantly following cautious remarks on inflation by Fed Chairman Kevin Warsh. The probability of a rate hike in forecasting markets has approached its highest levels in recent times, while bond yields have also seen a sharp increase.

    Market expectations are rapidly changing ahead of the Fed’s monetary policy meeting on September 16th. According to data from the forecasting markets, the probability of the Fed maintaining current interest rates is around 55%, while a 25 basis point rate hike is priced at around 46%. A larger rate hike is seen as having only about a 1% probability.

    CME Group’s FedWatch tool shows that investors have increased the probability of a rate hike at the September meeting to 55.7%. This represents an increase of approximately 20 basis points in just one day.

    Warsh: No Significant Improvement in Inflation Trend

    Federal Reserve Chairman Kevin Warsh, in a speech at the Jackson Hole symposium in Wyoming, noted that inflation remains high.

    Warsh acknowledged that the inflation data released during the summer was more positive than expected, but said that it did not indicate a lasting improvement in underlying inflation trends.

    Warsh stated, “While inflation data released this summer was better than expected, it doesn’t indicate a significant improvement in underlying trends.”

    The Fed chairman also added that it is necessary to ensure that inflation is moving clearly and quickly enough toward the level targeted by the central bank.

    Warsh signaled that otherwise the Fed might need to tighten monetary policy further, saying, “Otherwise, we have more work to do. This is our duty, our authority, and our responsibility.”

    However, Warsh did not offer any direct guidance on how the Fed will act in upcoming meetings, nor did he provide a definitive framework for what economic data interest rate decisions will depend on.

    US Treasury Yields Rise Sharply

    Following Warsh’s speech, US stock indices rose while selling pressure was observed in the bond market.

    The yield on the 2-year US Treasury bond, which is highly sensitive to expectations regarding the Fed’s interest rate policy, rose by approximately 8 basis points to 4.31 percent. This marks the highest level for the 2-year bond yield since the end of July.

    The rise in short-term bond yields indicates that investors’ expectations are strengthening that the Fed may implement a tighter monetary policy in the coming period.

    With approximately two and a half weeks to go until the September meeting, the new inflation and employment data to be released are expected to be critical in determining the direction of interest rate expectations. If inflation remains stronger than expected, the likelihood of an interest rate hike will increase, while a significant slowdown in price pressures could reinforce expectations that the Fed will keep interest rates unchanged.

    *This is not investment advice.

  • Venice posts record $1.1M quarterly earnings – Why is VVV down 13%?

    Venice posts record $1.1M quarterly earnings – Why is VVV down 13%?

    Venice Token [$VVV] dropped 13% to $16.03 at press time.

    However, the decline contrasted sharply with Venice Token’s improving protocol-level performance.

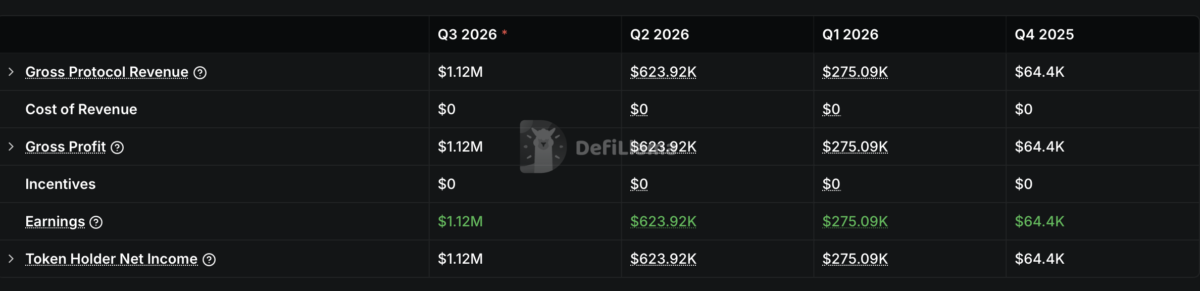
    DeFiLlama data showed record Quarterly Earnings of $1.1 million. Monthly Earnings also reached a record $654,000.

    Source: DeFiLlama

    The earnings growth suggested that activity and platform usage increased despite recent market turmoil.

    Even so, stronger protocol performance had yet to support $VVV’s price. This divergence raised two questions. Was $VVV entering a bearish phase, and which traders were driving the decline?

    Are derivatives traders pressuring $VVV?

    $VVV’s perpetual market showed the clearest signs of weakening trader sentiment. The Funding Rate fell from 0.0141% on the 28th of August to 0.0001% at press time.

    The Funding Rate remained marginally positive. Therefore, the decline showed weakening long demand rather than confirmed short dominance.

    Source: CoinGlass

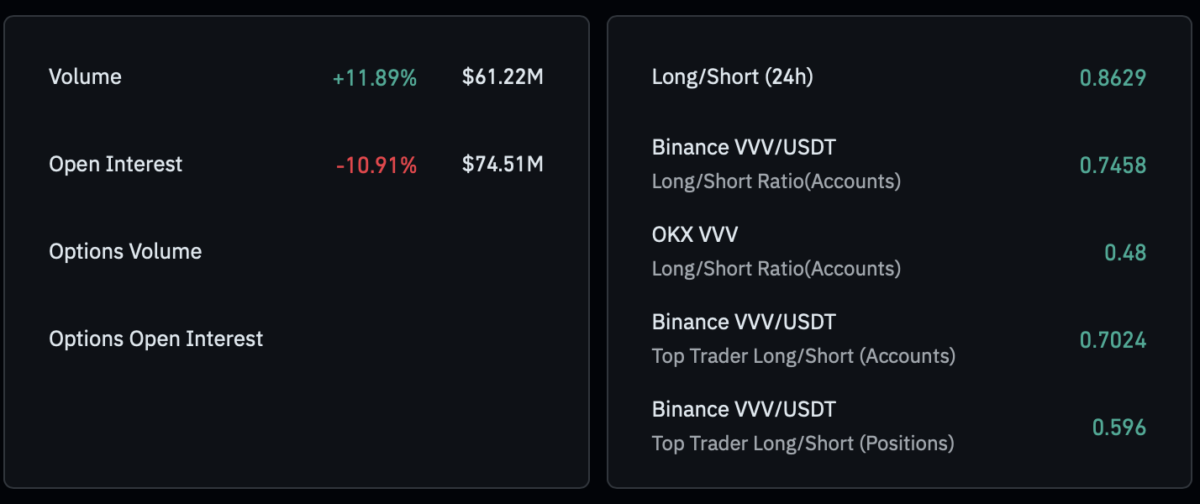
    However, $VVV’s Long/Short Ratio fell to 0.86, according to CoinGlass. A reading below one indicated that short accounts outnumbered long accounts within the measured market.

    Together, both Metrics pointed toward a weaker derivatives bias. Continued short positioning could maintain pressure on $VVV’s price.

    Are spot traders buying $VVV?

    By contrast, the altcoin’s Spot Market Netflow remained negative over recent sessions.

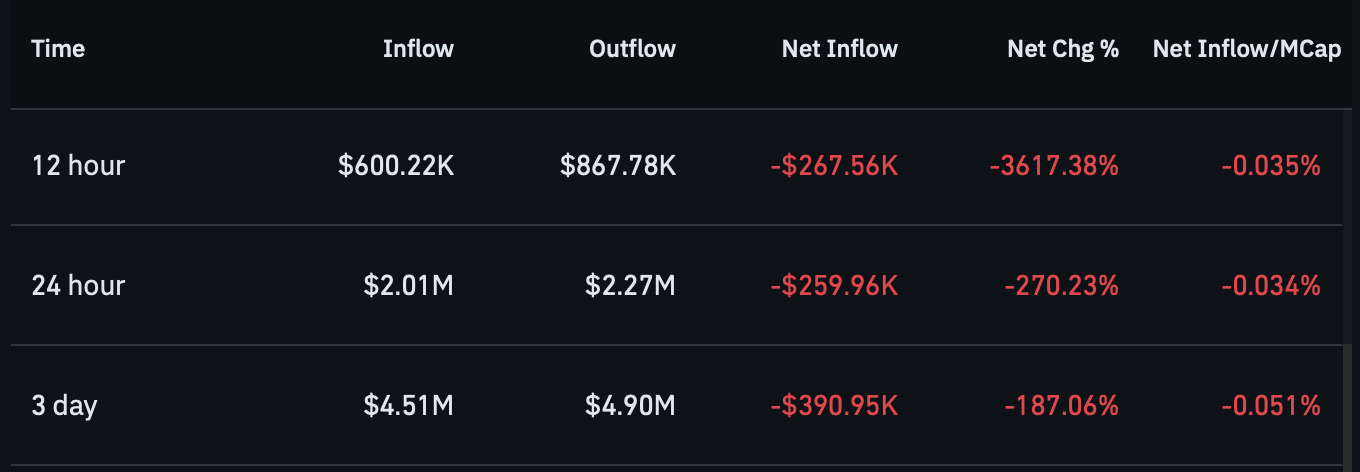
    Approximately $267,000 left centralized exchanges within 12 hours. Negative Netflows had also persisted for three days.

    Source: CoinGlass

    These outflows could indicate that holders were withdrawing $VVV from exchanges, reducing immediately available selling supply. However, negative Netflows alone cannot confirm fresh buying or long-term holding.

    $VVV therefore faced a clear market split. Derivatives traders leaned bearish, while Spot outflows suggested that exchange-side supply was tightening.

    If Spot accumulation continues, $VVV could attempt a near-term recovery. However, persistent derivatives pressure could delay that move despite Venice Token’s record earnings.


    Final Summary

    • Venice Token fell 13% to $16.03 despite record protocol Earnings. $VVV recorded $1.1 million in Quarterly Earnings.
    • $VVV’s Funding Rate fell sharply but remained marginally positive. The declining Funding Rate showed weaker long demand, rather than confirmed short dominance.
  • ‘This Seems Incorrect’: Ripple CTO Emeritus Slams Kalshi CFTC Argument

    ‘This Seems Incorrect’: Ripple CTO Emeritus Slams Kalshi CFTC Argument

    Fresh debate on whether U.S. states or the Commodity Futures Trading Commission (CFTC) should regulate the fast-growing prediction markets industry has emerged after a federal appeals court ruled that ​Kalshi cannot block Nevada gaming regulators from overseeing its platform.

    Prediction markets platform Kalshi and the CFTC have said sports event contracts are “swaps” under the 2010 Dodd-Frank financial reforms, affording the agency oversight through its authority to regulate national swaps markets.

    Ripple CTO Emeritus David Schwartz engaged with an X post from sports betting and gaming lawyer Daniel Wallach, who argued that the CFTC’s rulemaking is effectively “dead on arrival” because of the major-questions doctrine, which limits federal agencies from claiming broad powers without clear authorization from Congress.

    Schwartz responded that this premise might be incorrect, arguing that the central question is narrower: whether Congress actually delegated authority to regulate gambling through exchange-traded contracts.

    “This seems to be incorrect to me. The question is only whether Congress delegated the power to regulate gambling through exchange-traded contracts. As Kalshi correctly points out, traditional sportsbook gambling is very different,” Schwartz wrote.

    This seems to be incorrect to me. The question is only whether Congress delegated the power to regulate gambling through exchange traded contracts. As Kalshi correctly points out, traditional sportsbook gambling is very different. https://t.co/EY6MKlq1Mx

    — David ‘JoelKatz’ Schwartz (@JoelKatz) August 28, 2026

    Explaining further what he meant, Schwartz stated that: “Of course Congress didn’t intend to replace state-regulated sportsbook gambling with exchange-traded products outside of state regulation. It meant to create a new, uniform federal framework for creating exchange-traded products outside of state regulation.”

    What happened?

    The legal dispute began in March 2025, when the Nevada Gaming Control Board sent Kalshi a cease-and-desist letter claiming that Kalshi’s sports-event contracts constituted an unlicensed sports pool under state gaming law.

    Kalshi argued that the CFTC’s authority over swaps preempted Nevada’s gaming rules.

    On Friday, the 9th U.S. Circuit Court of Appeals in San Francisco upheld Nevada oversight of prediction markets. Circuit Judge Ryan Nelson said Kalshi’s contracts have the hallmarks of sports betting, “a quintessential form of gambling” that the CFTC does not regulate.

    “The CFTC is not a national gambling regulator,” Nelson said, adding that “it is difficult, then, to conclude that Congress intended to ​upend its decades of careful regulation ​of gambling based on broad definitions of the words used in a Wall Street Reform Bill.”

  • Leading Asset Manager Bitwise Moves $15.4 Million of XRP Off Supply

    Leading Asset Manager Bitwise Moves $15.4 Million of XRP Off Supply

    Leading asset management firm Bitwise has sparked discussions following its consistent $XRP purchases while $XRP continues to show mixed price actions as momentum begins to fade.

    Per recent data showcased by Whale Insider, Bitwise has extended its $XRP buying streak after it bought a large amount of $XRP worth $15.4 million.

    $XRP institutional demand skyrockets

    The recent price breakout has sparked confidence across the $XRP ecosystem, fueling rising demand among both retail and institutional investors.

    The bullish momentum has extended to the $XRP ETF market as all existing funds have continued to record steady daily inflows for the past two weeks.

    Following this consistent capital injection in the $XRP ETF market, Bitwise has continued to record growing demand for its $XRP product from institutional investors.

    Its latest $XRP purchase has particularly drawn attention from market analysts as it has come when $XRP has turned negative, reversing from its recent bullish performance.

    $XRP exits bullish zone

    Despite the sustained demand from $XRP institutional investors, it appears that momentum is fading as the asset has suspended its price rally, returning to red territory.

    Latest on-chain data shows that $XRP has retreated to the $1.3 price level, showing a price decline of about 2% over the last 24 hours as speculative trading appears to be outweighing its demand.

    Although $XRP has slowed from its recent price surge, the asset still maintains the highest price gain for this month following several months of extreme volatility.

  • The SEC is reviewing automatic filing pathways after exotic crypto and event-linked ETF proposals flooded the market

    The SEC is reviewing automatic filing pathways after exotic crypto and event-linked ETF proposals flooded the market

    Wall Street now wants a ticker to hold almost any financial idea an investor might type into a brokerage search bar, from Bitcoin and funds promising two or three times a stock’s daily return to private assets and contracts tied to elections or economic events.

    The ETF began as a cheap way to own a broad market portfolio, then became the distribution system for exposures that once required a futures account, a private placement, a crypto exchange, or a patient reading of a structured-note prospectus.

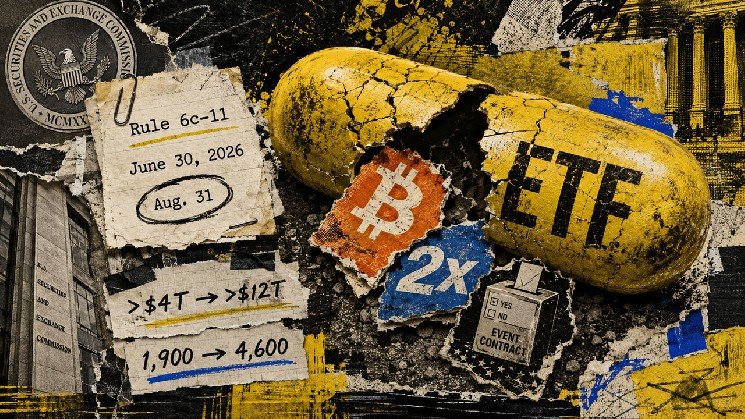
    The SEC is reviewing how far that distribution system can stretch. Its June 30 request for public comment covers crypto assets, commodities, heightened gearing, single-stock products, blockchain-based opportunities, private assets, and event contracts, with comments due Aug. 31.

    The review reaches beyond any single application because the agency is examining whether its existing rules give staff enough time and authority to assess products whose economic behavior can differ sharply from the diversified funds investors learned to trust.

    Assets in US ETFs climbed from more than $4 trillion at the end of 2019 to more than $12 trillion at the end of 2025, while the product count rose from almost 1,900 to more than 4,600, according to the SEC’s concept release.

    A format built for indexing has become the default shelf space for financial products whose risk can be hard to infer from the ticker alone.

    The ticker is the product

    An ETF packages a portfolio into shares that trade throughout the day on an exchange, letting investors buy exposure through the same account they use for ordinary stocks.

    The creation and redemption process lets authorized participants exchange large blocks of fund shares for the underlying basket or its cash equivalent, which helps keep the trading price close to the portfolio’s value.

    That mechanism turned what was essentially operational design into a retail habit by giving investors intraday trading, transparent pricing, broad brokerage access and, in many structures, better tax handling than a comparable mutual fund.

    Asset managers gained a product they could put inside model portfolios and trading apps, and every successful launch encouraged sponsors to place a more specialized exposure behind the same interface.

    The regulatory framework grew around that original bargain because early ETFs needed individual exemptive orders for features, including exchange trading and in-kind redemptions, that didn’t fit neatly within rules written for open-end mutual funds.

    In 2019, the SEC adopted Rule 6c-11, allowing qualifying ETFs registered under the Investment Company Act of 1940 to operate without seeking an order for each launch, provided they met conditions involving portfolio information, trading data, and the arbitrage mechanism.

    Rule 6c-11 made launches faster and more standardized, helping the product count more than double by the end of 2025. A plain index fund, a concentrated thematic portfolio, and a derivatives strategy can now look almost identical on a brokerage screen, even though their holdings, valuation methods, and loss profiles bear little resemblance to one another.

    The term ETF just describes the container, while the assets and contracts inside determine what an investor owns.

    The common brokerage screen hides several legal categories because many stock and bond ETFs are registered investment companies under the 1940 Act, while spot Bitcoin and Ethereum products commonly use commodity-trust structures registered under the Securities Act of 1933.

    Exchange-traded notes add another category: unsecured debt obligations whose return depends on the issuer’s promise, and brokerage interfaces often place all three side by side under a broad exchange-traded product heading.

    Those legal categories govern custody, board oversight, diversification, borrowing, derivatives use, valuation, and the remedies available when an issuer or service provider fails. A familiar ticker reduces the effort required to buy an exposure while leaving those differences intact, which is why the SEC is examining the conditions attached to the wrapper as closely as the portfolio inside it.

    Crypto taught the old ETF a new trick

    Spot crypto products became the cultural turning point because investors treated exchange listing as a bridge between an unfamiliar asset and an established account.

    The SEC’s approval of spot Bitcoin products in 2024 gave advisers and institutions a regulated trading venue, standardized disclosures, and conventional custody relationships, while the agency stressed that its order wasn’t an endorsement of Bitcoin itself.

    The distinction between legal approval and perceived legitimacy became harder to see as the product menu widened.

    Many investors encounter an ETF ticker at a major broker and infer that the underlying exposure has passed through a common filter, even when one product owns a broad equity basket and another holds a volatile commodity or rolls derivatives that can drift from the reference asset. Crypto showed sponsors how much commercial value sits inside that familiarity.

    Sponsors have since applied the same distribution logic to staking, options overlays, token products promising a multiple of the daily move, and baskets of digital assets. Each design can serve an investment use while adding its own custody, valuation, market-hours, and concentration issues.

    Crypto trades around the clock, ETF shares trade during exchange hours, and the creation process has to bridge those clocks when prices move sharply overnight or across a weekend.

    Event-contract funds expand into more unfamiliar territory by tying returns to election outcomes, economic releases, or other defined events inside shares that trade like ordinary funds. CryptoSlate identified more than two dozen event-linked ETF proposals, showing how quickly a niche contract market could reach retail brokerage accounts once an ETF supplies the route.

    The regulatory difficulty comes from function because an event contract can trade on an exchange overseen by the CFTC while the fund shares and disclosures sit within the SEC’s remit.

    Risks can spread across several rulebooks, requiring the review to examine how the contract settles, who supplies prices, what happens when trading halts, and whether the fund can meet redemptions near the event date.

    Those criteria apply differently to every category in the concept release.

    A private-asset fund can face stale valuations and limited exits, a single-stock multiplier product can reset daily and compound away from its stated multiple over longer periods, and a token-based product can depend on custody or staking arrangements that have no close counterpart in a traditional index fund.

    A product-by-product framework can attach conditions to each source of risk more precisely than a single definition of novelty.

    The SEC fast lane reached unfamiliar territory

    The SEC also has to decide whether its filing process gives staff enough time to examine unfamiliar structures before shares reach the market.

    Certain registration statements or post-effective amendments can become effective automatically once a statutory or rule-based waiting period expires, and some amendments filed under Rule 485 can take effect immediately when they meet specified conditions.

    Those pathways make routine fund updates and launches efficient, and the same route can carry a portfolio that staff hasn’t encountered before.

    SEC Chair Paul Atkins said in May that several sponsors had agreed to delay novel ETF launches, including event-contract products, while the agency evaluated the issues.

    A voluntary delay gives staff breathing room for the current set of filings, while a durable policy could require rule amendments, added disclosure conditions, a different review track, or a clearer boundary around which products qualify for automatic treatment.

    Every revision carries a cost because a broad restriction could slow ordinary fund launches and give established issuers an advantage over smaller sponsors, while a narrow rule could leave staff racing against automatic deadlines whenever a new payoff structure appears.

    The agency also has to preserve the arbitrage mechanism that keeps ETF shares close to net asset value, since disclosure alone can’t repair a portfolio whose assets are too hard to price or acquire during creations and redemptions.

    Crypto issuers have a direct stake in the outcome even if event contracts command the most attention.

    New staking structures, tokenized securities, multi-asset baskets, and products with daily return multiples could face added filing requirements based on how the SEC defines novelty and which safeguards it demands.

    A framework centered on custody, valuation, liquidity, and payoff complexity could give sponsors a clearer route, while a wrapper-level restriction could group economically different crypto products together.

    The SEC has already posted public comment letters and meeting records ahead of the Aug. 31 deadline. Once the current input period closes, the agency will have to weigh those submissions, decide whether current authority and disclosure standards are sufficient, and publish any proposed rule amendments through the normal notice-and-comment process.

    Existing products and pending applications will keep supplying data about premiums, discounts, trading quality, and investor use during that process.

    The ETF conquered Wall Street by making investment exposure easy to distribute, turning the wrapper into financial infrastructure for almost every kind of portfolio. A brokerage customer can move from an S&P 500 fund to Bitcoin, a two-times stock position, or an election-linked contract with a few taps, even though each trade enters a different economic world.

    The SEC now has to decide which exposures require a different gate before the common ticker persuades investors that the gate has already done all the work.
  • Oscar Winner Matt Damon to Headline Ripple Event as Featured Speaker

    Oscar Winner Matt Damon to Headline Ripple Event as Featured Speaker

    Academy Award winner Matt Damon will appear at the upcoming Ripple Swell event, scheduled for October 27-29, 2026.

    Ripple is bringing together the global financial community for the Swell event in New York City. For the first time, Ripple is combining the Swell event and XRPL Apex developer summit into a single event intended for institutional leaders and fintech innovators, as well as the developers and researchers building on the $XRP Ledger.

    As seen on the official Swell page, actor and screenwriter Matt Damon, who is also the co-founder of water.org, is named as a featured speaker at the event alongside top Ripple executives including CEO Brad Garlinghouse, President Monica Long and CTO Emeritus David Schwartz.

    Others include Tom Farley, Chairman and CEO of Bullish; Johann Kerbrat, SVP & GM of Crypto at Robinhood; Laide Majiyagbe, Global Head of Markets at BNY; Michael Blaugrund, Vice President of Strategic Initiatives at Intercontinental Exchange (ICE); and Raghuram Rajan, former Governor of the Reserve Bank of India.

    In a Friday X post, the Swell event updated its speaker list to include Alastair Sewell, Senior Investment Director at Aviva; Chase Lax, CEO of Susquehanna Crypto; Gary White, CEO and co-founder of water.org; and Jenny Just, co-founder of PEAK6.

    More voices are joining the Swell speaker lineup:

    Alastair Sewell, Senior Investment Director at Aviva

    Chase Lax, CEO of Susquehanna Crypto

    Gary White, CEO and co-founder of https://t.co/SBdXm1OVeI

    Jenny Just, co-founder of PEAK6

    See all speakers: https://t.co/LB3NRvg1iB pic.twitter.com/7mMxA7WebP

    — Swell (@RippleSwell) August 28, 2026

    Water.org, co-founded by Damon, is a Ripple partner, which makes his appearance significant. The connection gives Damon’s appearance a more practical angle than a typical celebrity keynote; however, the exact details of what Damon will discuss were scarce at press time.

    Ripple expands

    In October 2025, Ripple revealed that several of the world’s leading development and humanitarian nonprofit organizations, including Water.org, are leveraging Ripple Payments and the Ripple USD (RLUSD) stablecoin to help improve the speed, transparency, and impact of aid delivery and funding.

    In an announcement on Friday, Ripple unveiled the launch of its Delta One business within Ripple Prime, its global, multi-asset prime brokerage platform. Ripple Prime’s Delta One enables clients to execute Total Return Swaps across U.S.-listed equities, indices, and digital assets.