Category: Business

  • trade.xyz launches event contracts, wiring prediction markets into Hyperliquid platform

    trade.xyz launches event contracts, wiring prediction markets into Hyperliquid platform

    On Thursday, the prediction markets were incorporated into trade.xyz’s Hyperliquid trading platform via the launch of Events. The platform already operated one of the largest perpetual businesses on the network. Therefore, traders can now trade prices, interest rates, or scores without the need of switching to a different prediction market platform.

    This is important since trade.xyz does not have to start from scratch. Coin Metrics referred to trade.xyz as Hyperliquid’s top HIP-3 developer by opportunity trading and volume, allowing Events to immediately reach an already established group of traders in cryptocurrency.

    Events runs on HIP-4, not a separate venue

    Events is based upon Hyperliquid Improvement Proposal 4 (HIP-4) that permits the addition of fully collateralized outcome contracts to HyperCore. trade.xyz launches the markets under the venue name txyz. Each market uses a validator-approved template, but the deployer is responsible for choosing permitted parameters and for publishing how the outcome will be resolved.

    The launch of Events is also in line with the larger goal of trade.xyz for this platform. In announcing Events, the company stated:

    “vision of Hyperliquid as the universal exchange”

    In effect, this innovation allows the company to incorporate prediction markets as another product in Hyperliquid’s overall trading portfolio rather than as a separate gambling venue.

    The costs remain minimal during the launch phase. According to the documentation of trade.xyz, deployerFeeScale is currently set to zero, which means the company does not apply any additional deployer fee, while charging standard fees for outcome trading on Hyperliquid.

    How the contracts settle, and where trust sits

    The outcome contracts under HIP-4 are considered to be fully collateralized, which means that no leverage, funding payments, and liquidation are needed in this case. In a binary marketplace, when trading in Yes and No positions, one uses the same economic order book; thus, buying Yes for price p would be the same as selling No for 1-p.

    The most significant problem here is settlement. trade.xyz breaks down the process of resolution into two steps. First, the published methodology determines the result based on the declared data source. Next, the result is uploaded into HyperCore by the txyz deployer or the designated settlement address. The data source performs no settlement on its own.

    The Daily Up/Down markets utilize a five-minute average from Hyperliquid candle data, while the initial sports markets utilize ESPN unless specified otherwise. trade.xyz cautions that corrections, delays, or uncertain outcomes may cause delayed settlements, thereby ensuring the importance of resolution design and the integrity of the oracle to market risk.

    A distribution edge most rivals lack

    Coin Metrics reported that trade.xyz accounted for about 55% of Hyperliquid perpetual-market volume in August. As of its August 18 report, the platform had facilitated more than $460 billion in volume since January, roughly 30% of Hyperliquid’s total, while holding more than $4 billion in open interest. It also generated about $5 million in fees over the preceding month.

    That footprint gives Events a built-in distribution advantage. Prediction contracts can be put in front of traders already using trade.xyz for crypto, equities, commodities and other perpetual markets.

    Cryptopolitan reported on August 31 that Hyperliquid was opening prediction-market deployment to third parties, with trade.xyz preparing its own launch and a 500,000 HYPE bond required for outside outcome deployers.

    The stakes for Polymarket and Kalshi

    The market is already much larger than it was earlier this year. Galaxy’s June 9 analysis said combined prediction-market lifetime volume crossed $150 billion in April. That month, Kalshi recorded $14.81 billion in notional volume and Polymarket $9.01 billion.

    The latest Artemis prediction-market data supplied for this article shows how quickly the sector has grown. Combined lifetime volume across the tracked venues has reached about $402.76 billion. In August 2026, the latest complete month in the dataset, Kalshi generated $40.03 billion in notional volume, compared with about $8.50 billion for Polymarket across its international and U.S. activity.

    Kalshi retains the advantage of regulated U.S. exchange access, while Polymarket remains strong in consumer discovery. Hyperliquid is making a different bet: if event contracts become a routine line item beside perpetuals in the same account, prediction markets begin to look less like a niche and more like a standard part of onchain derivatives trading.
  • Treasury yields continue to rise even as Bessent doubles down on bond buybacks

    Treasury yields continue to rise even as Bessent doubles down on bond buybacks

    Yields also rose across other major bond markets, including Europe and Japan, as investors remained concerned about inflation, higher oil prices and the sustainability of government borrowing.

    The latest $6 billion operation follows the Treasury’s original announcement that it would at least double its long-duration buybacks from their typical $2 billion size. Yields initially fell after that announcement but later reversed sharply higher.

    The Treasury is effectively repurchasing longer-dated bonds while continuing to finance itself at the front end of the yield curve. That changes the maturity profile of the government’s debt but does not reduce its overall borrowing needs.

    The bond-market intervention followed earlier coordinated action by the U.S. and Japan to support the Japanese yen.

    Earlier this week, Treasury Secretary Scott Bessent challenged currency traders to bet against the intervention, declaring, “I am the house now.” A stronger yen is also in the U.S. government’s interest because it reduces the pressure on Japan to sell U.S. Treasuries to finance further currency intervention. Japan is the largest foreign holder of U.S. government debt.

    Alongside rising Treasury yields, WTI crude has climbed to around $97 a barrel, matching its May high. The increase has added to concerns that higher energy costs could keep inflation elevated, making the Federal Reserve’s job more difficult.

  • BIS chief warns AI capex arms race relies on opaque debt, posing systemic risks

    Hernandez said five largest big tech companies alone plan to invest over a trillion dollars on AI-related projects between 2025 and 2026,. with expectations that global AI-related investment will grow from roughly $500 billion today to between $3 trillion and $4 trillion by 2030. Bridgewater Associates recently reported that Microsoft MSFT$490.41·Market Closed, Alphabet GOOG$328.41·Market Closed, Meta META$654.01·Market Closed and Amazon (AMZ), which have a combined market cap of approximately $12 trillion, expect to spend $650 billion together on AI infrastructure this year alone.

    Concerns about an AI bubble have been circulating this year, such asCitrini Research’s bearish 2028 scenario that unsettled technology stocks in February.

    “With U.S. stocks accounting for a large share of global equity markets, the effects could propagate globally. In some jurisdictions, windfall gains from rising AI-related exports may also contribute to domestic asset bubbles, further exacerbating financial stability concerns,” he said.

    “I do not say that this is where the AI boom must lead.But the scale and speed of the current investment boom, and the weight of expected commercial returns, do warrant some caution.”

    The BIS chief said AI’s promise is real, including evidence of productivity gains in coding, consulting and professional writing,but added that the eventual economic effect will depend on how widely the benefits are shared and whether policymakers invest in skills, infrastructure and competition.

  • Binance Founder CZ Reveals the Crypto Market Offers Numerous Opportunities for Entry and Exit! Here Are the Details

    Binance Founder CZ Reveals the Crypto Market Offers Numerous Opportunities for Entry and Exit! Here Are the Details

    Changpeng Zhao (CZ), founder and former CEO of Binance, commented on investment opportunities in the cryptocurrency markets. Zhao stated that the market offers investors numerous opportunities to both buy and sell, emphasizing that the key is making the right decision.

    Changpeng Zhao, in a short post on X, stated, “The market offers many opportunities for entry or exit. All you have to do is make the right decision.” Zhao’s statement highlighted the importance of timing and decision-making for investors in a period of constantly changing market conditions.

    The statement by Binance’s founder aligns with assessments that price movements in cryptocurrency markets offer investors the opportunity to implement different strategies. Especially during periods of high volatility, investors can view price dips as buying opportunities and price increases as opportunities to reduce positions or exit.

    Zhao did not specify a particular cryptocurrency, price level, or investment strategy in his post. Instead, he pointed out that the nature of the market inherently offers investors opportunities to enter and exit at different times.

    Investment decisions in cryptocurrency markets are influenced by numerous factors, including price movements, liquidity, trading volume, macroeconomic developments, and investor sentiment. Zhao’s statement, rather than directly recommending a specific asset, emphasizes the need to properly assess the opportunities presented by market conditions.

    Zhao, as the founder of Binance, is among the most well-known figures in the cryptocurrency sector, and his social media posts continue to be closely followed by market participants.

    *This is not investment advice.

  • Japan’s 3% bond yield challenges U.S. Treasuries

    Japan’s 3% bond yield challenges U.S. Treasuries

    BlackRock warned on Sept. 8 that rising Japanese government bond yields could weaken demand for U.S. Treasuries by giving Japanese investors more attractive returns at home.

    Japan’s 10-year government bond yield briefly exceeded 3% for the first time since 1996, while its 30-year yield reached a record 4.18%.

    The shift matters because Japan holds roughly $1.1 trillion of U.S. Treasury securities. Decades of low and negative domestic interest rates encouraged Japanese banks, insurers and pension funds to invest abroad. Higher Japanese yields are beginning to alter that calculation.

    Japan is becoming a key focus in global bond markets.

    Surging yields on Japanese government bonds could attract some local investors and weigh on U.S. Treasury demand as competition for capital intensifies.

    Explore why Japan matters for U.S. bond investors in our latest… pic.twitter.com/3wpal4oJvp

    — BlackRock (@BlackRock) September 9, 2026

    Japan bond yields now compete with U.S. debt

    A Japanese investor can earn approximately 3% from a 10-year Japanese government bond, according to BlackRock’s commentary. A comparable U.S. Treasury produces about 2% after the investor hedges the dollar exposure back into yen using rolling three-month currency forwards.

    The comparison does not mean Japanese investors will immediately sell their foreign holdings. Hedging costs change with currency and interest-rate conditions, while institutions also consider liquidity, portfolio duration and regulatory requirements. However, the return advantage that pushed capital overseas has narrowed.

    Fitch Ratings reached a similar view on Sept. 9. The rating agency said higher yields could encourage Japanese institutions to retain more capital domestically. Fitch did not forecast a broad liquidation of existing bond portfolios.

    BlackRock used a hypothetical 5% shift in Japan’s Treasury holdings to illustrate the scale. Such a move would redirect about $55 billion, equal to roughly 7% of the U.S. Treasury’s expected net borrowing during the quarter. The calculation is a scenario, not a forecast of actual selling.

    Bank of Japan tightening raises repatriation risk

    Japanese yields have risen as inflation, wages and yen weakness increase pressure on the Bank of Japan to tighten policy. The central bank raised its policy rate to 1% in June and left it unchanged in July.

    BOJ board member Kazuyuki Masu said on Sept. 10 that the bank may need to increase rates more rapidly if inflation accelerates. A Reuters poll found economists expected a rise to 1.25% during September, followed by further tightening through 2027. Those forecasts remain subject to the BOJ’s decision.

    The yen previously weakened to about ¥160 per dollar before recovering. The U.S. and Japan also conducted a coordinated yen-buying intervention, the first joint operation of its kind since 1998. A stronger yen can reduce the value of unhedged overseas assets for Japanese investors and make domestic holdings more attractive.

    A weaker yen creates a different risk. Japanese authorities could sell foreign assets to finance intervention, potentially adding pressure to U.S. Treasuries. BlackRock described this as a possible feedback loop rather than a confirmed capital flow.

    Higher global yields add pressure to Bitcoin

    The global bond sell-off continued into Sept. 10. The 10-year JGB yield stood near 2.91%, below its recent 3% peak, while the U.S. 10-year Treasury yield reached approximately 4.84%. The 30-year U.S. yield traded near 5.29%.

    Higher government bond yields can weigh on Bitcoin and other non-yielding assets by increasing the returns available from lower-risk securities. They can also raise corporate borrowing costs and reduce liquidity available for speculative markets.

    As crypto.news reported, Bitcoin faced a possible decline toward $70,000 after retreating from $82,283 and struggling to hold the $78,000–$79,000 area. That weakness coincided with rising Treasury yields, stronger oil prices and renewed inflation concerns.

    Bitcoin’s reaction does not establish that Japanese yields caused its decline. Crypto prices respond to several factors, including ETF flows, leverage, dollar liquidity and investor positioning. Japan’s rate reset adds another source of competition for global capital.

    Inflation and central-bank decisions come next

    U.S. consumer inflation data scheduled for Sept. 11 will shape expectations before the Federal Reserve’s Sept. 15–16 policy meeting. A stronger inflation reading could support higher U.S. yields and reinforce competition between bonds and risk assets.

    Investors will then focus on the Bank of Japan’s September decision. A faster tightening cycle could push JGB yields higher and strengthen the yen, increasing incentives for Japanese institutions to hold more domestic assets.

    The main indicator will be actual portfolio data rather than modelled scenarios. U.S. Treasury disclosures, Japanese institutional reports and currency-hedging costs will show whether investors are repatriating capital or merely adjusting new purchases.

    BlackRock remains underweight Japanese government bonds because it expects yields to face further upward pressure. Its central argument is conditional: rising domestic returns could reduce Japanese demand for U.S. debt, but the scale and timing of any shift remain uncertain.

  • Dogecoin sinks 5% to lead majors losses, with bitcoin holding $78,000 level

    Dogecoin sinks 5% to lead majors losses, with bitcoin holding $78,000 level

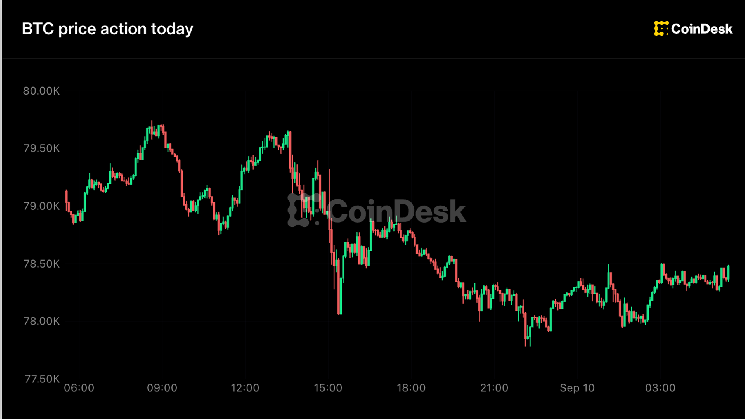
    Bitcoin traded just above $78,000 as of Asian morning hours on Thursday, down about 1% over 24 hours, with the rest of the majors falling harder.

    Dogecoin was the worst of them, down more than 5%, followed by BNB at about 4% and XRP at 3%. Solana, hyperliquid’s HYPE and ether each shed between 1% and 3%, leaving ether just under $2,475 and solana near $102. Tron was the only gainer, up less than 1% to about 34 cents, according to CoinDesk data.

    Bitcoin’s 50-day average price crossed above its 200-day average on Tuesday.

    FxPro analysts said a similar crossover in October 2024 and May 2025 produced nothing, but that this one follows a prolonged bull market rather than appearing inside a correction.

    “The current situation bears a closer resemblance to what we saw in 2019,” they wrote, pointing to a 90% rally in under two months after that signal.

    Read More: Bitcoin’s golden cross is here

    Brent crude climbed as high as nearly $102 a barrel in Asian trade after Iran said it was prepared for a more intense war, and the higher oil price is feeding straight into rate expectations.

  • Hunter Biden’s LAPTOP blames bots after 98% crash as traders rack up six-figure losses

    Among five wallets Nansen examined, one was sitting on a roughly $199,000 total loss after realising $171,000 and holding another $27,900 in unrealised losses. Another that bought about 28,400 $LAPTOP without selling was down roughly $118,000.

    One address that bought about 49,700 $LAPTOP was sitting on roughly $13,000 in unrealised profit at the time of the snapshot.

    Nansen put $LAPTOP at roughly a $720 million market capitalisation and a $2.1 billion fully diluted valuation even after the fall. Those figures flatter newly launched tokens, because small trades in thin liquidity move the quoted price a long way.

    As such, $LAPTOP‘s team pushed back against suggestions that insiders had an advantage, saying there was no presale and no allocations for investors, influencers or key opinion leaders. The contract address, token allocation, security audit and other disclosures were published before trading began, it said.

    “Everyone had the same information, at the same time,” the project said in the Thursday blog post.

    It reiterated that ounders’ 30% allocation is locked for six months and vests over two years. Another 30% of supply is tied to a predictions mechanism, under which tokens are either burned or sent to charity depending on the outcome of specified events.

  • Consensys Software Inc. Splits In Two, Rebrands As MetaMask

    Consensys Software Inc. Splits In Two, Rebrands As MetaMask

    Consensys Software Inc. is separating into two companies, the firm said Wednesday.

    The existing corporate entity will continue and rebrand as MetaMask, running the wallet and its consumer products under co-founder Joe Lubin as chairman and chief executive. Its Protocols Group and institutional blockchain infrastructure business, including the Linea layer 2, becomes a newly formed company named Consensys.

    The split separates Ethereum’s most widely used wallet from one of its largest protocol development shops for the first time since Lubin founded the company in 2014. Each side gets its own chief executive, board and capital allocation: a consumer business now selling stablecoin yield and card spending, and an enterprise business selling tokenization infrastructure to banks.

    Who Runs What

    Mike Kriak becomes chief executive of the new Consensys, with David Cunningham as president and Declan Fox as chief product officer, according to the company’s post on X. Lubin will be executive chairman. That entity keeps Linea, the Besu Ethereum execution client used in permissioned enterprise networks, the Teku consensus client and Consensys’ Ethereum protocol work. The announcement does not say which company takes Infura, whose website now brands it as part of MetaMask Developer.

    MetaMask keeps the wallet and the Money Account, the self-custodial product combining automated yield, card spending and swaps that launched on June 30 paying up to 4% on stablecoin balances. The company says the wallet has passed 100 million downloads across roughly 190 countries. Completion of the separation is expected by the end of 2026, and users need to take no action.

    “Stepping into this role full-time is a recognition that consumer finance deserves the same focus and ambition that we’ve brought to building Ethereum itself,” Lubin said in the announcement.

    The Institutional Pitch

    Cunningham framed the institutional side around settlement plumbing. “Financial institutions and market infrastructure are moving to always-on operations with tokenization at the core,” he said. The release cited a June 2026 Citi report estimating tokenized assets could reach $5.5 trillion to $8.2 trillion by 2030.

    Linea’s own numbers are smaller. The network holds $29 million in DeFi deposits, DefiLlama data show, against $38.1 million in stablecoins issued on it. LINEA trades at $0.002664, down 2.2% over 24 hours and 94% below its September 2025 all-time high, according to CoinGecko, for a market capitalization of $65.3 million. Another 960 million tokens unlock on Sept. 10.

    The token launched at roughly a $500 million market capitalization a year ago, and Lubin teased further rewards for holders after it halved within weeks.

    The $MASK Question

    Neither the press release nor Lubin’s accompanying blog post mentions a MetaMask token. Lubin confirmed on The Block’s podcast in September 2025 that a $MASK token was coming, and tied it to “the decentralization of certain aspects of the MetaMask platform.” The company registered a claim.metamask.io domain in October 2025 and has not shipped a token since.

    The announcement is also silent on the initial public offering the company has been preparing. Axios reported in October 2025 that Consensys had hired JPMorgan and Goldman Sachs to advise on a listing. Which of the two entities carries that process forward is unstated.

  • Crypto Long & Short: Inside the 300-to-1 onchain gap between the dollar and euro

    Crypto Long & Short: Inside the 300-to-1 onchain gap between the dollar and euro

    Euro stablecoin activity is small, but rapidly growing. Euro vault AUM across DeFi increased from roughly €12 million a year ago to €135 million today, still representing only 2.4% of total vault AUM. We believe euro-denominated real-word asset (RWA) yield products will accelerate EUR stablecoin growth.

    Path Dependency & Missing Infra

    Onchain euro issuance is trailing the offchain world primarily for two reasons: a historical path dependency and lack of euro-denominated DeFi infrastructure.

    Path dependency. Stablecoins were built to settle crypto trading, and crypto pairs were originally priced in dollars. Since the base pair was USD, USD stablecoins launched to match the assets they settled.

    Missing infrastructure. Vault infrastructure and looping (where each loan funds the next purchase) accelerated dollar-denominated DeFi. Dollar-denominated yield-bearing assets were issued onchain. Lending protocols accepted them as collateral and issued dollar debt against them, allowing users to buy more dollar-denominated yield-bearing assets.

    Consequently, every major lending market onchain today reflects this dollar-denominated looping trade. Euro-denominated leverage markets did not take off because the legs of the loop didn’t exist.

    Dollar Defi is Insufficient for Euro-Denominated Users

    Euro-denominated vault infrastructure is a market necessity for European asset managers, corporate treasuries that operate and report in euros and European DeFi users who think in euro terms. These users represent significant latent demand, as they have been structurally limited from fully participating in the onchain economy due to burdensome FX risk and hedging costs.

  • Attention Bitcoin and Ethereum Investors! Germany is Changing its System! Here are the Details

    Attention Bitcoin and Ethereum Investors! Germany is Changing its System! Here are the Details

    As countries around the world continue to regulate cryptocurrencies, taxation stands out as one of the most important issues.

    The latest notable regulatory effort on this issue comes from Germany.

    A New Era in Bitcoin and Cryptocurrency Earnings!

    Germany, one of Europe’s largest countries, is preparing comprehensive regulations to tax gains from cryptocurrencies, particularly Bitcoin and Ethereum.

    According to BlockBeats, a draft prepared by the German Ministry of Finance plans to subject cryptocurrency gains to a flat tax of 25 percent, similar to stocks and other capital investments.

    The draft legislation is not yet enacted and will be submitted to parliament for approval after a review process within the government.

    One Year of Tax Exemption is Ending!

    Under the current system, gains made by individual investors from selling cryptocurrencies held for more than a year are exempt from tax. However, the ministry wants to abolish this exemption, and the new regulation proposes removing this exemption and classifying cryptocurrencies as capital gains.

    At this point, the new system is planned to be applied to cryptocurrencies acquired on or after January 1, 2027.

    The draft also envisages preserving some important advantages for investors. The current annual tax exemption limit of €1,000 ($1,170) is expected to remain in effect. Furthermore, according to the report, the draft text also includes a provision allowing crypto investment gains and losses to be offset against gains and losses from other securities such as stocks.

    *This is not investment advice.