In brief
- Executives from DTCC and Barclays said the biggest near-term payoff from tokenization lies in putting collateral to work around the clock.
- Barclays’ head of digital assets said much of the early value lies in moving collateral between banks’ own accounts, before extending it to clients.
- Both executives said adoption is still early, but that institutions have moved from asking questions to putting real money into building.
The biggest payoff from tokenizing traditional assets won’t come from simply putting them onchain, but from putting idle collateral to work, according to executives at the Depository Trust & Clearing Corporation (DTCC) and Barclays.
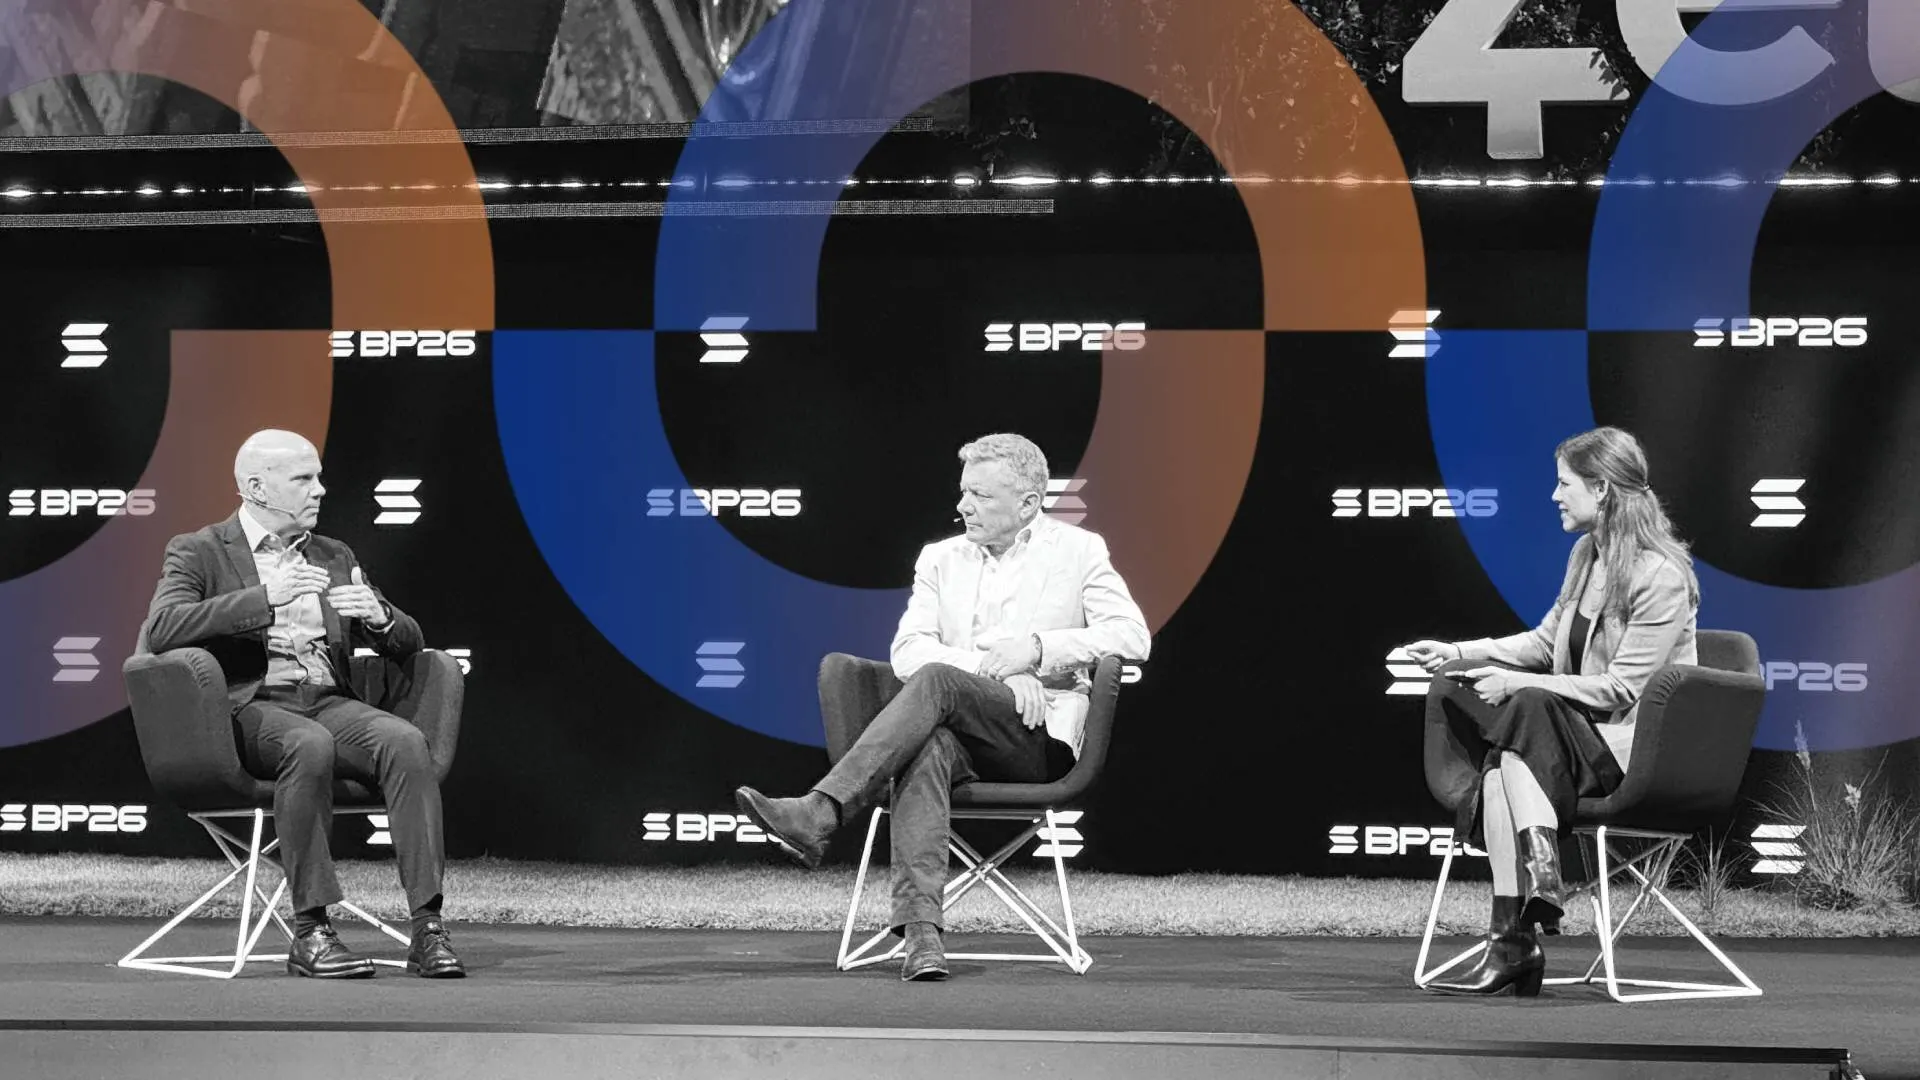
“You can tokenize an asset, but if you can’t do anything with it, what’s the point?” Val Wooton, DTCC’s global head of equities solutions, said at Solana’s Breakpoint conference in London. “For me, it really is around collateral and liquidity.”
Scott Lucas, head of digital assets at Barclays, agreed. A lot of collateral sits “relatively idle” at central securities depositories, he said, and much of the early value for banks will come from moving it more efficiently between their own accounts, before extending that to clients. “There’s a lot of money in good housekeeping,” he added.
The pair spoke on a panel days after DTCC announced that its tokenization service will connect to Solana, with tokenized assets expected on the network in the second half of 2027.
The service, which launched on October 28, can tokenize assets held at DTCC’s depository, starting with Russell 1000 stocks, ETFs tracking major indexes, and U.S. Treasury bills and bonds, Wooton said. The tokens carry the same legal and economic rights as traditionally held securities, and adding Solana reflects DTCC’s strategy of being “open,” “interoperable” and “multi-network,” he added.
From ‘just in case’ to ‘just in time’
Wooton said the biggest opportunity lies in “liquidity optimization,” which he said could save “millions, if not billions” of dollars by letting firms move assets that are currently stuck when markets are closed.
Large financial institutions today over-fund and over-collateralize every day because they treat collateral as “just in case,” he said. Moving assets onchain, around the clock, would let firms manage collateral “just in time,” freeing up “a significant amount of balance sheet” to put to other uses. He added that the ability to move assets and settle them atomically could be “extremely powerful” in times of market stress.
Lucas pointed to Barclays’ participation in DTCC’s tokenization launch last month, one of the bank’s first public moves into the space, and described the efficiency gains from managing its own collateral as good housekeeping.
Barclays is also working with Ironlight on tokenized structured products, Lucas said, though he stressed “it’s not a done deal.” He added that he would like to see Solana adopted by other central securities depositories around the world, building a shared infrastructure layer across Asia-Pacific, Europe and the United States.
‘Still in the crawl stage’
Both executives said adoption remains early. Wooton said the industry is “still in the crawl stage,” and that traditional and digital rails will exist side by side “for quite a long time,” though DTCC’s clients are already tokenizing assets daily.
Lucas said he tries to stay “healthily skeptical” about the speed of adoption while making sure Barclays is ready for its clients. At a recent traditional finance conference in Miami, he said, “every institution we met had money on the table,” making investments and building products, a shift from a year earlier, when most were still asking questions.
Barclays has been gradually expanding its crypto activities. The bank invested in U.S. stablecoin startup Ubyx earlier this year and has reportedly weighed a push into tokenized deposits and stablecoin payments, according to Bloomberg. It was also among the investors backing crypto custodian Copper in 2022.
Daily Debrief Newsletter
Start every day with the top news stories right now, plus original features, a podcast, videos and more.
Join 72,000+ readers
Leave a Reply