Category: Business

  • From Bitcoin to oil, perpetual contracts are breaking into American financial markets

    From Bitcoin to oil, perpetual contracts are breaking into American financial markets

    The Commodity Futures Trading Commission (CFTC) asked a federal court on Sept. 2 to dismiss CME’s challenge to Kalshi’s Bitcoin perpetual contract.

    The lawsuit turns on whether a contract without a fixed expiration belongs in the US futures regime. Before the court reaches that question, the regulator says CME must first show an injury the court can fix.

    The Commodity Futures Trading Commission says CME is free to list a comparable digital commodity product, so the exchange cannot blame the regulator for competitive harm caused by its choice to stay out.

    That threshold argument turns a dispute over one Bitcoin contract into a test of how perpetual-style futures can spread through regulated US markets.

    Bloomberg reported discussions about Coinbase seeking a regulated route to selected contracts linked to prices on Hyperliquid. Kalshi is reportedly preparing to seek approval for a West Texas Intermediate crude-oil version.

    Together, the examples trace a contract structure popularized in offshore crypto markets as it enters the American regulatory perimeter one venue and asset class at a time.

    CryptoQuant data shows that global crypto perpetual-futures volume reached about $61.7 trillion in 2025, up 29% from the previous year, while spot trading totaled $18.6 trillion over the same period.

    The CME case could shape how much of that activity US exchanges can pursue through the CFTC’s futures framework.

    The CFTC says CME can compete in Bitcoin perpetuals

    CME sued the CFTC on June 18, seeking to overturn the agency’s May 29 approval of KalshiEX’s Bitcoin perpetual contracts and the accompanying policy statement. CME argued that a contract without a fixed expiration is a swap rather than a future under the Commodity Exchange Act.

    The CFTC’s motion said the relief CME seeks would fail to remedy the exchange’s claimed competitive injury.

    The agency added that CME may list similarly structured digital commodity perpetuals, characterizing any disadvantage from CME declining that opportunity as self-inflicted.

    A judicial decision treating Kalshi’s product as a swap would not necessarily remove competing exposure from the market because another venue might offer it under that classification. In the agency’s view, a win for CME on that point would still fail to redress the alleged injury.

    The current schedule gives CME until Oct. 2 to oppose the dismissal motion. A ruling on standing could leave the deeper line between futures and swaps unresolved.

    The May 29 CFTC policy defined designated contract markets as those that could list similarly structured perpetuals tied to Bitcoin and digital commodities with deep, active, and continuous spot markets. Products outside that group were directed toward case-by-case review under Regulation 40.3.

    The result is a faster path for qualifying digital commodity products and a separate review track for other assets. That distinction will matter as venues look from crypto toward energy and other established futures markets.
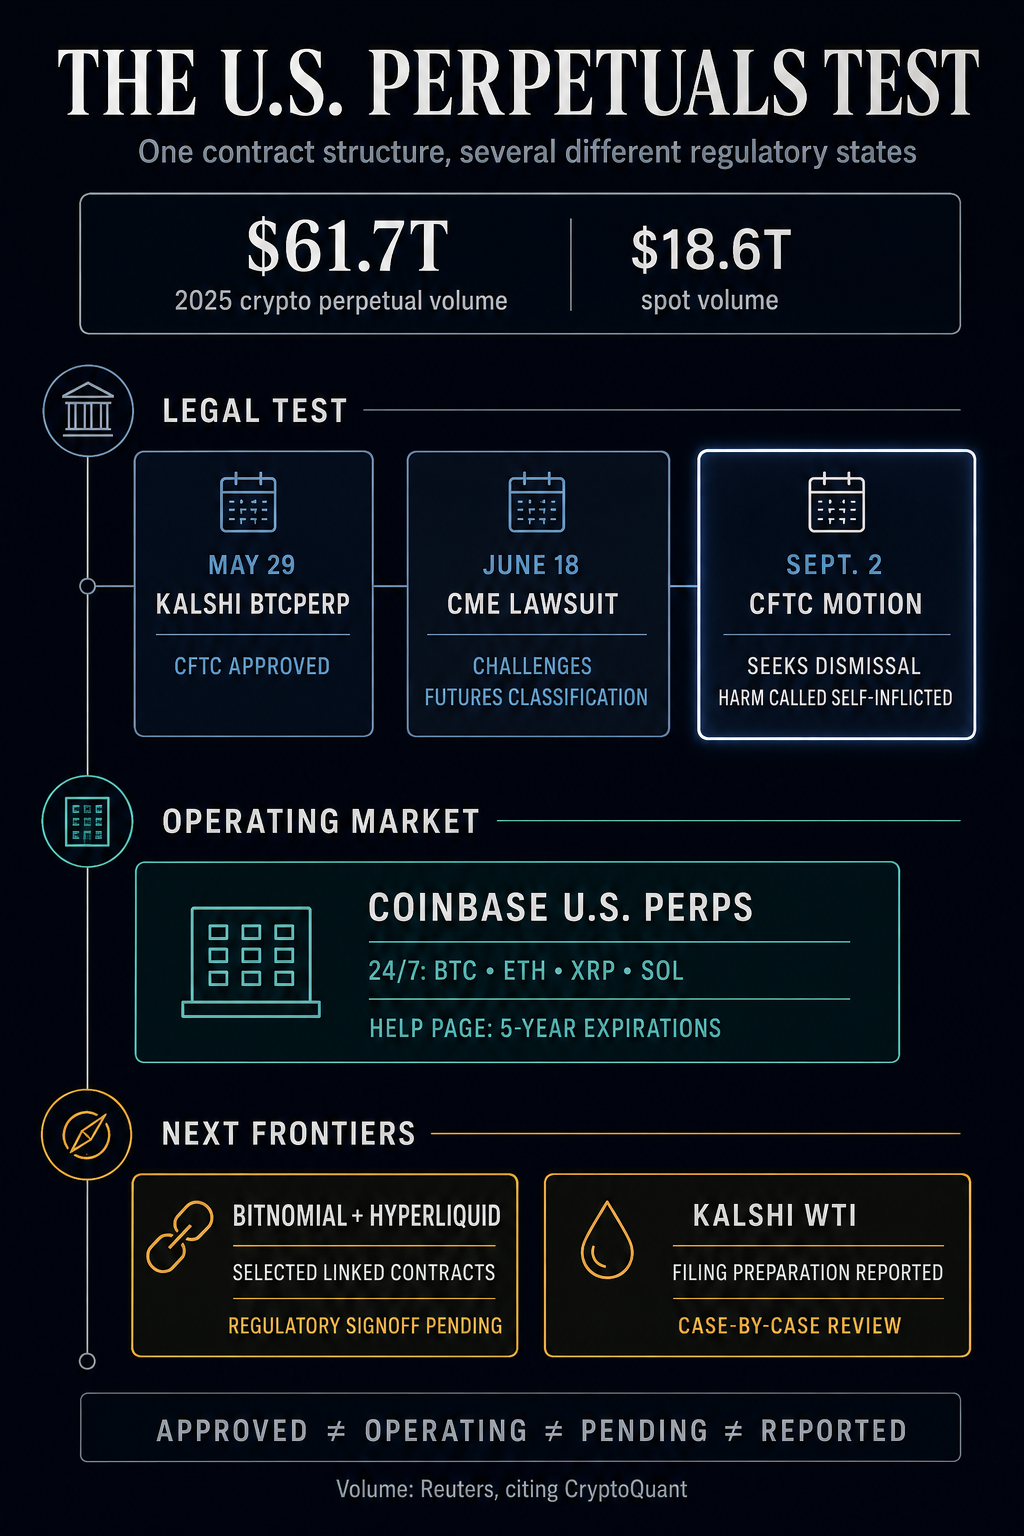
    The timeline shows Kalshi, CME, and CFTC milestones for US crypto perpetuals, alongside Coinbase’s operating market and pending Bitnomial, Hyperliquid, and Kalshi products.

    Coinbase’s derivatives market page markets US perpetual-style futures with 24/7 trading and contract families tied to Bitcoin, Ethereum, XRP, and Solana.

    The name “perpetual” covers different contract mechanics in the emerging US market. Coinbase’s official help material describes the covered contracts as having five-year expirations, so they offer long-dated, continuously traded exposure, while a literal expiry-free contract requires different terms.

    A June CFTC staff letter granted conditional relief for requests from Coinbase Derivatives and Bitnomial to remove expiration dates from existing digital commodity perpetual-style contracts that expired on June 30.

    Regulated US perpetual-style crypto futures have moved from policy concept to operating category, even as the exact expiration mechanics vary by contract. CME’s suit challenges the agency approach behind that change as rival venues adapt one of crypto’s largest trading formats.

    Hyperliquid would test an on-chain bridge

    Hyperliquid and Payward are reportedly discussing a structure for registered US users. Payward subsidiary Bitnomial, a regulated derivatives venue, would offer selected contracts tied to token prices on Hyperliquid.

    Payward completed its acquisition of Bitnomial in August, adding its US derivatives exchange and clearing infrastructure.

    President Donald Trump supplied a political signal on Aug. 19, saying that his administration was working on a US route for Hyperliquid during a White House technology event.

    A signed-off structure would test a bridge between a registered domestic venue and token prices formed in an on-chain market. Surveillance, market integrity, and the precise relationship between the venues would turn on the approved design.

    Polymarket’s international site shows live leveraged crypto perpetual markets, while Polymarket US is a separate platform. The international product demonstrates how quickly crypto-native venues are expanding the format, supplying global context.

    Oil brings the model into traditional futures

    In June, the CFTC requested public comment on 24/7 futures trading and perpetual contracts for storable, physically delivered energy commodities, including crude oil. That consultation placed the structure under active review in a longstanding futures market.

    Kalshi is reportedly preparing a CFTC filing for a perpetual contract tied to WTI crude oil, potentially as soon as the following week.

    A WTI proposal would follow the CFTC’s case-by-case route. Its review would also confront the practical differences between a cash-referenced crypto contract and a market built around a physical commodity with established delivery infrastructure.

    Perpetuals are being considered for a traditional commodity market where CME is an incumbent, placing the new structure closer to the core of established derivatives competition.

    A quick CFTC victory on standing would preserve the agency’s framework without a ruling on the futures-versus-swaps question. Other exchanges could read that result as support for proposing similar contracts, subject to the applicable listing or review process.

    Continued litigation on the merits would put the statutory classification question before the court. A decision on whether a no-expiry contract can qualify as a future would create a clearer legal boundary, while the period before a ruling could complicate product planning.

    Regulatory sign-off for selected Bitnomial contracts linked to Hyperliquid prices would test the on-chain bridge. Acceptance of a WTI perpetual would show the structure crossing into a traditional commodity.

    The CFTC is now defending its approach in court while exchanges probe its limits, with perpetual-style products entering the regulated US market.

    The next phase will depend on whether CME has standing, how a court classifies the Kalshi contract, which venues can meet the CFTC’s conditions, and whether regulators allow the model to extend from digital commodities to on-chain prices and physical markets.
  • Japan’s 4% bond yield spike threatens the low-cost borrowing strategy behind corporate Bitcoin buying

    Japan’s 4% bond yield spike threatens the low-cost borrowing strategy behind corporate Bitcoin buying

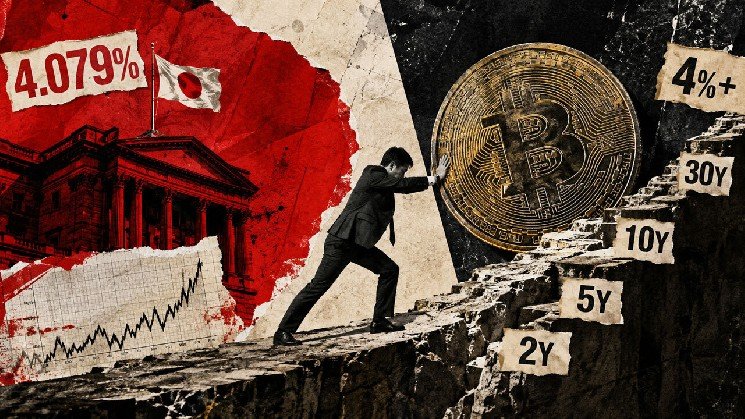
    Japan’s 30-year government-bond auction cleared at a 4.079% average yield on Sept. 3, underscoring a tougher backdrop for future capital raised by Metaplanet to buy Bitcoin. The long bond is a market signal; the nearer test for the company is the price of shorter-tenor debt and refinancing.

    The average yield rose 14.2 basis points from 3.937% at the previous 30-year auction on Aug. 6. Japan’s Sept. 1 10-year auction averaged 2.995%, placing the 4% threshold at the long end rather than across the entire curve. The Bank of Japan, meanwhile, maintains an operating guideline of around 1% for the uncollateralized overnight call rate.

    Metaplanet’s existing fixed obligations retain their contractual cash flows. Its ¥8 billion 20th-series ordinary bond is zero-coupon and matures on April 23, 2027, while its inaugural BitBonds carry fixed coupons. The shift in Japanese yields instead raises the benchmark for future issuance and refinancing.

    That leaves a narrower version of Metaplanet’s funding advantage intact. The bilateral zero-coupon bond protects near-term cash flow, but repeating such favorable terms at the scale required for sustained Bitcoin purchases remains uncertain.

    Metaplanet BitBonds face a shorter-tenor funding test

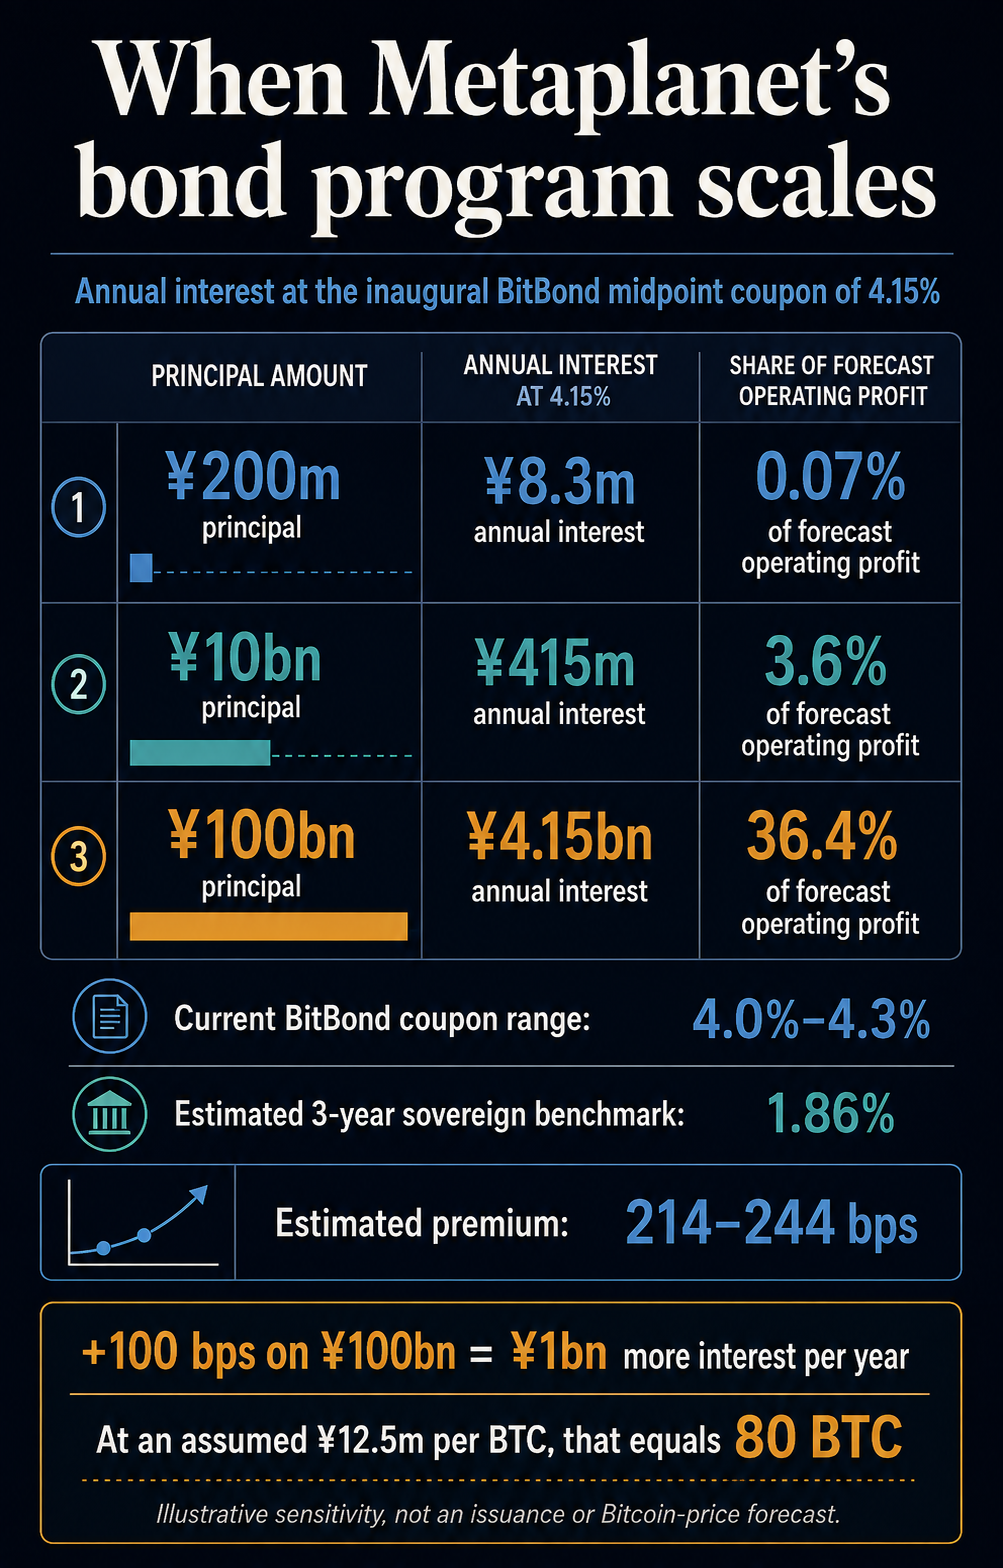
    Metaplanet’s inaugural 21st through 24th-series BitBonds total ¥200 million, pay fixed coupons ranging from roughly 4.0% to 4.3%, and mature in about three years. Recent government auctions cleared at average yields of 1.708% for two-year debt and 2.163% for five-year debt.

    A straight-line interpolation between those official results produces an estimated three-year sovereign benchmark of 1.8597%. The estimate is an analytical tenor comparison rather than a traded three-year quote or a cash-flow duration calculation.

    Against it, the inaugural BitBonds pay an estimated premium of about 214 to 244 basis points. Future coupons would rise if the sovereign benchmark increased while Metaplanet’s credit spread stayed constant. A wider credit spread would add further pressure.

    The bond terms explain why investors may require that premium. The BitBonds are unrated, unsecured and unguaranteed senior obligations. They carry transfer restrictions, and secondary-market liquidity is unassured. Metaplanet has said later series may differ in maturity and interest rate according to market conditions and investor demand.

    Existing instruments face a different equation. Higher rates can affect their market value, while the stated coupon and principal cash flows remain fixed. The company’s 20th-series ordinary bond funded Bitcoin purchases before all expected cash arrived from its 27th-series stock acquisition rights. Part of the warrant proceeds was designated to repay the bond, allowing Metaplanet to bring forward funding without an annual coupon bill.

    Metaplanet’s funding channels carry different costs

    Metaplanet was already drawing on several channels at midyear. At June 30, it reported 43,000 $BTC, $414 million drawn from a $500 million Bitcoin-collateralized credit facility, ¥67.486 billion of short-term borrowings, ¥8 billion of bonds due within one year and ¥1.805 billion of first-half interest expense.

    Second-quarter Bitcoin purchases used proceeds from the 20th-series bond, the credit facility, the 27th-series rights and Bitcoin-income revenue. This mix kept purchases moving while mNAV remained below 1.0x for most of the half and the company made no discretionary common-share allotments during the quarter. The funding inventory therefore separates into two parts: fixed structures protect current economics, while each new round of capital faces prevailing market terms.

    Scale turns a coupon into a constraint

    The inaugural BitBond issue is too small to transform Metaplanet’s economics. At 4.15%, the midpoint of its coupon range, annual interest on ¥200 million is about ¥8.3 million, equivalent to roughly 0.07% of the company’s ¥11.4 billion full-year operating-profit forecast.

    The same rate applied to larger illustrative programs produces a different result:

    The ¥10 billion and ¥100 billion rows are sensitivities rather than issuance forecasts. They show why the ability to expand the program at acceptable rates matters more than the first tranche’s small coupon bill.

    A one-percentage-point increase on an illustrative ¥100 billion program would add ¥1 billion to annual interest. At an assumed Bitcoin purchase price of ¥12.5 million, that amount equals 80 $BTC a year when the additional interest comes entirely from cash otherwise available for accumulation.

    Metaplanet could instead meet the expense through operating cash flow or another financing source. The 80 $BTC figure applies only to the stated price and cash-use assumptions. Its purpose is to translate a rate move into the company’s capacity to add Bitcoin for each share outstanding.

    The balance-sheet effect grows faster than the headline drama. A 4.079% 30-year sovereign yield changes little about a ¥200 million BitBond issue. A large future debt program near the current coupon range would consume a meaningful portion of forecast operating profit before any additional rise in the benchmark or credit spread.

    Equity access depends on Metaplanet’s valuation

    The 27th-series rights generally may be exercised only when company-notified mNAV is at least 1.01x. No rights were exercised in August. At Aug. 31, 947,300 rights representing 94.73 million potential shares remained, equal to about 7.0% of the company’s 1.345 billion issued shares.

    That leaves a material but conditional dilution overhang. If the mNAV threshold prevents exercise, warrant-funded Bitcoin purchases may stall and the proceeds intended partly for repaying the zero-coupon bond arrive more slowly. If the threshold is satisfied and exercises resume, Metaplanet gains funding while existing holders absorb more shares.

    The company also held authority to repurchase as many as 150 million shares for up to ¥75 billion through Oct. 28. It bought zero shares in August and zero cumulatively under that authorization through Aug. 31, leaving buybacks absent from the period’s offset to potential dilution.

    For the first half, Metaplanet’s issuer-defined measure of Bitcoin holdings per 1,000 fully diluted shares increased 9.6% to 0.0263554 $BTC. The reported funding mix was accretive over that period. Future accretion becomes harder as debt principal expands, coupons rise or more rights convert into shares.

    Japan’s Sept. 3 auction therefore tests Metaplanet’s funding advantage at the margin. The zero-coupon bridge preserves the clearest benefit on existing terms, and the BitBond program demonstrates access to fixed-rate yen debt at a meaningful premium over a comparable sovereign tenor. The next funding round’s price and scale will determine how much of that advantage continues to reach Bitcoin per share.

  • MemeToro Presale News: Three Audits Approve Its Contracts As Open-Source AI Validation Support Its Stage 7 Progress

    MemeToro Presale News: Three Audits Approve Its Contracts As Open-Source AI Validation Support Its Stage 7 Progress

    From time to time, a crypto project needs to address contract security and transparency.

    MemeToro’s Stage 7 progress has been supported by three independent smart contract audits, while MemeToro has presented its AI agent architecture as open source.

    These details matter because buyers need to know how a crypto project handles its code, launch rules, and token distribution before focusing only on price.

    MemeToro Presale News: What Three Audits Tell Buyers

    MemeToro presale news highlights three independent smart contract audits as an important technical milestone. A smart contract is code that runs rules on a blockchain. An audit checks that code for security problems, unexpected behavior, and other weaknesses before users depend on it.

    Three audits do not make a project risk-free, but they give users more information than an unaudited contract. For a presale project, this can be especially useful because buyers are sending funds to blockchain contracts and need to understand how those contracts are designed.

    The key points are during Stage 7, after launch, and as the platform gains users and trading activity.

    Three independent audits have approved MemeToro’s deployment frameworks.

    The project operates on BNB Chain. Public smart contracts are intended to enforce launch rules. The audit work supports, but does not guarantee, future security.

    For people following MemeToro Presale News, the main value of the audits is greater visibility into the technical side of the project. A recent project update also identifies Coinsult, BlockSAFU, and SolidProof as part of its reported three-audit security stack.

    How Open-Source AI Supports the Stage 7 Story

    Another major part of MemeToro Presale News is the project’s open-source AI agent. MemeToro describes an AI agent that monitors social media, online communities, and global news for emerging trends. It can then generate a memecoin concept, visuals, branding, marketing content, and token details before a launch.

    The open-source approach matters because users can inspect the architecture and understand more about how the system is intended to work. MemeToro also says its launch process removes private allocation tiers and insider advantages. Instead, public smart contracts enforce the published rules for launches.

    The AI proposes a launch, while smart contracts enforce the conditions. That separation can make the process easier to understand than a system where important launch decisions remain hidden.

    That distinction is useful for everyday buyers. Security reviews mainly answer technical questions, while an open-source AI model answers questions about visibility and process.

    Neither one answers the larger market question of whether users will adopt the platform or whether $MT will gain lasting demand after launch. Those outcomes depend on delivery, liquidity, trading activity, and wider crypto conditions.

    What the Audits and AI Validation Do Not Prove

    MemeToro Presale News does not mean audits or open-source code remove investment risk. An audit is a review at a specific point in time. New code, integrations, market conditions, or user behavior can create different risks later.

    Open-source architecture can improve visibility, but it cannot guarantee that AI-generated memecoins will perform well. Meme markets are highly volatile, and technical quality cannot predict demand.

    Users evaluating Stage 7 should therefore look at several areas together:

    • Audit findings and whether identified issues were addressed.
    • Public contract behavior and launch rules.
    • AI agent documentation and actual product delivery.
    • Tokenomics and distribution.
    • Liquidity and exchange plans after launch.

    MemeToro’s tokenomics list 1.2 billion total $MT, with 71% for the public sale and 10% for CEX reserves. It also describes up to 35% APR staking and a 24-month vesting period for marketing and partnership allocations.

    These details add useful context, but they should be assessed alongside security and market risks.

    More Information on MemeToro ($MT) Presale Here:

    Website: https://memetoro.com/

    X: https://x.com/memetoro_mt

    Telegram: https://t.me/memetoro_mt

    YouTube: https://www.youtube.com/watch?v=gY0jgWy_DtA

  • Citigroup Revised Its Fed Interest Rate Forecast Following the Release of U.S. Employment Data

    Citigroup has significantly postponed its expectation regarding Federal Reserve interest rate cuts following strong employment data from the US.

    The bank announced that it expects the Fed to make its next 25 basis point interest rate cut in June 2027. According to Citigroup’s new forecast, the Fed is expected to implement three separate 25 basis point interest rate cuts in June, September, and December 2027. Citi previously predicted rate cuts in October and December 2026, and January 2027.

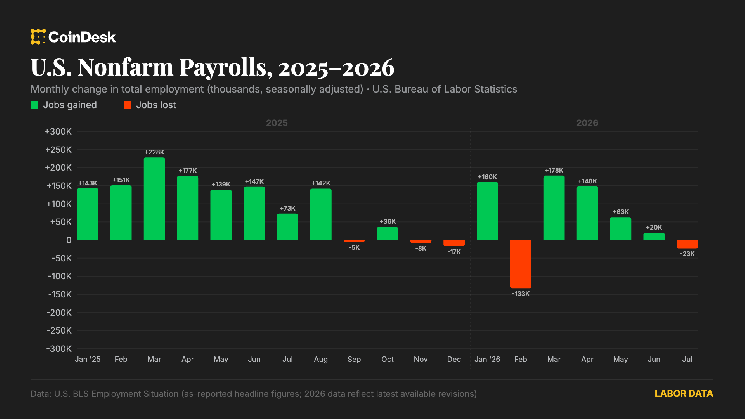
    Strong US employment data influenced the forecast revision. In August, non-farm employment increased by 162,000 people, exceeding market expectations, while the unemployment rate remained stable at 4.1 percent.

    Citigroup, which has long been known for its relatively dovish views on the Fed, stated that recent data may lead policymakers to assess the employment market as generally stable and shift the focus of monetary policy to the inflation outlook.

    In a note they published, Citi economists Andrew Hollenhorst and Veronica Clark pointed out that the unemployment rate remained unchanged and the labor force participation rate had recovered significantly.

    Following strong employment data, market expectations for the Fed have also changed. According to Fed funds futures, the probability of the Fed raising interest rates at its September 15-16 meeting has risen from 52 percent before the employment report to 61 percent.

    Investors are expected to watch the consumer price index (CPI) and producer price index (PPI) data to be released next week for new signals regarding the Federal Reserve’s future interest rate policy.

    *This is not investment advice.

  • Crypto Presale Outlook: Can MemeToro Benefit From Bitcoin’s $3 Billion ETF Inflow Streak?

    Crypto Presale Outlook: Can MemeToro Benefit From Bitcoin’s $3 Billion ETF Inflow Streak?

    Bitcoin’s institutional demand has become one of the strongest signals behind September’s crypto market. US spot Bitcoin ETFs recorded roughly $3 billion in net inflows across a nine-day streak before a brief outflow interrupted the run.

    This matters for crypto presale news because stronger Bitcoin demand can improve market confidence and liquidity. MemeToro enters that environment in Stage 7, but high Bitcoin dominance suggests any move into smaller projects may remain selective rather than market-wide.

    Bitcoin ETF Demand Supports the Crypto Presale Outlook

    The roughly $3 billion ETF streak was the strongest run reported during 2026. After a $202 million outflow interrupted the sequence, inflows returned with roughly $217 million on August 31.

    Bitcoin has since pushed toward $81,000 to $81,200. It is holding above its EMA20, EMA50, and EMA200, while Strategy has resumed corporate Bitcoin purchases with a roughly $370 million investment.

    These signals suggest large investors remain interested in $BTC.

    For a crypto presale update, the link is indirect but important. When Bitcoin rises on strong institutional demand, traders can become more willing to consider higher-risk opportunities elsewhere in the market.

    However, the current environment is not a confirmed altcoin season.

    Bitcoin dominance remains around 59%, while earlier Altcoin Season Index readings stayed below the 75 level normally used to declare broad altcoin leadership.

    This suggests liquidity may move selectively into certain narratives rather than lifting every presale equally.

    MemeToro Enters Stage 7 During Stronger Sentiment

    MemeToro’s latest presale dashboard shows $118,562.95 raised toward a $156,312.74 Stage 7 target. The current $MT price is $0.00430.

    That timing could help MemeToro if stronger Bitcoin conditions encourage investors to explore smaller assets.

    The project is also positioned within two narratives that could attract selective capital: AI and memecoins.

    Rather than launching only a standalone meme token, MemeToro is developing an AI-powered launch system on BNB Chain. Its agent is designed to scan trends, generate memecoin concepts, and move validated ideas toward structured launches.

    Its wider process follows Propose, Verify, Fund, and Launch.

    That creates a product-led argument for considering MemeToro a best crypto presale to watch, particularly if the 2026 market continues rotating toward AI-integrated projects rather than entering a broad altcoin rally.

    Bitcoin Greed Could Also Create Short-Term Risk

    ETF inflows do not mean Bitcoin will rise in a straight line. $BTC’s daily RSI has reached about 72.4, placing the market in overbought territory.

    The Fear & Greed Index is also at 74, or Greed.

    Both indicators show strong demand, but they also suggest traders have become increasingly optimistic. A Bitcoin pullback could reduce appetite for speculative presales, especially if investors move back toward larger assets.

    That makes risk management important when reading crypto presale news.

    MemeToro does have several project-specific factors that could help separate it from general market momentum:

    • Three displayed security reviews from Coinsult, BlockSAFU, and SOLIDProof give buyers additional sources for contract due diligence.
    • Fixed-rate funding gives participants the same round price without separate insider tiers.
    • Launch manifests publish supply, price, caps, reasoning, and evidence before funding begins.
    • Deterministic validation checks allocation and funding rules before proposals move forward.

    These features cannot protect $MT from broader market volatility.

    Still, if Bitcoin’s institutional demand continues and liquidity begins rotating selectively toward AI and memecoin infrastructure, MemeToro enters September with a clearer catalyst than Bitcoin momentum alone.

    FAQs

    How much entered Bitcoin ETFs during the streak?

    US spot Bitcoin ETFs recorded roughly $3 billion in net inflows over nine consecutive days before the streak was interrupted.

    Could Bitcoin ETF inflows help MemeToro?

    They could improve overall risk appetite, but there is no direct link guaranteeing that Bitcoin ETF money will flow into MemeToro.

    What is MemeToro’s latest Stage 7 data?

    The latest dashboard shows $118,562.95 raised toward $156,312.74, with $MT priced at $0.00430 and a displayed launch price of $0.05186.

    More Information on MemeToro ($MT) Presale Here:

    Website: https://memetoro.com/

    X: https://x.com/memetoro_mt

    Telegram: https://t.me/memetoro_mt

    YouTube: https://www.youtube.com/watch?v=gY0jgWy_DtA

  • MemeToro Prediction 2027: Can AI Utility and Exchange Listings Support $MT After Launch?

    MemeToro Prediction 2027: Can AI Utility and Exchange Listings Support $MT After Launch?

    MemeToro Prediction 2027 focuses on what could support $MT after its launch, rather than only its early meme appeal.

    MemeToro is building an ecosystem around an AI agent, a memecoin launchpad, decentralized prediction markets, staking, and planned exchange access. Looking toward 2027, the main question is whether these features can create steady use and demand.

    MemeToro Prediction 2027: Why AI Utility Matters

    MemeToro Prediction 2027 starts with the project’s AI agent because it is a central part of the planned ecosystem.

    MemeToro says the agent continuously scans social media, online communities, and global news to find trends with viral potential. It can then generate a memecoin name, concept, visuals, branding, and marketing content.

    The goal is to automate much of the work needed to create a memecoin. The AI proposes a launch, while public smart contracts are designed to enforce the published rules. MemeToro says there are no private allocation tiers or insider advantages in its launch model.

    This matters because regular launchpad use could connect $MT to platform activity. If the AI launchpad is used regularly, $MT could become connected to activity across the platform.

    The main utility areas include:

    • AI-powered memecoin creation and launches.
    • Memecoin trading and funding.
    • Prediction markets using $MT and stablecoins.
    • Staking and ecosystem rewards.

    MemeToro Prediction 2027 therefore depends partly on whether these features move from planned products to active services with real users.

    How Prediction Markets Could Support $MT

    Another part of the MemeToro prediction 2027 case is the project’s decentralized prediction market. MemeToro describes a blockchain-based platform where users can use $MT and stablecoins to predict outcomes of real-world events. The platform is designed around audited smart contracts and on-chain settlement.

    Prediction markets can give a token a practical role. In MemeToro’s model, $MT is used for predictions, while successful positions can earn rewards in $MT and USDC. That creates a direct link between product activity and token use.

    MemeToro also connects market information, memecoin activity, AI analysis, and prediction tools. If users move between these products, $MT could become a common asset across the ecosystem.

    However, the 2027 outlook depends on adoption. A product can be technically available without becoming popular. The stronger signal would be steady activity, repeat users, trading volume, and transparent on-chain participation.

    For MemeToro Prediction 2027, utility is therefore a possible support factor, not proof of future price growth.

    Can Exchange Listings Strengthen the 2027 Outlook?

    Exchange access could be another important factor in the MemeToro prediction 2027 discussion. MemeToro’s tokenomics allocate 10% of total supply to CEX reserves, showing that centralized exchange access is part of the stated token structure. Wider exchange availability can make a token easier for new users to discover and trade.

    Liquidity is also important. A token may have useful technology, but limited liquidity can make trading harder and increase price swings. If $MT gains listings with meaningful volume, that could improve market access and support broader participation.

    The project lists 1.2 billion total $MT supply, with 71% assigned to the public sale. It also describes up to 35% APR staking and a 24-month vesting period for marketing and partnership allocations.

    A careful MemeToro Prediction 2027 view should not treat utility or listings as automatic price drivers. Actual usage, liquidity, delivery, competition, and crypto conditions will matter.

    By 2027, strong signs would be:

    • Active prediction markets.
    • Frequent AI-generated launches.
    • Growing trading activity.
    • Exchange liquidity.
    • Community participation.

    FAQs

    What could support $MT in 2027?

    AI utility, prediction markets, memecoin activity, staking, liquidity, and exchange access could support demand if users adopt the products.

    Why are exchange listings important?

    They can improve access, visibility, and liquidity, although a listing does not guarantee a higher price.

    More Information on MemeToro ($MT) Presale Here:

    Website: https://memetoro.com/

    X: https://x.com/memetoro_mt

    Telegram: https://t.me/memetoro_mt

    YouTube: https://www.youtube.com/watch?v=gY0jgWy_DtA

  • BIS’s Choice Surprises: This Altcoin Was Preferred in the New Study! Here’s Why!

    BIS’s Choice Surprises: This Altcoin Was Preferred in the New Study! Here’s Why!

    $XRP, ranked fifth among the largest cryptocurrencies, experienced a 6% increase in the last 24 hours. As the $XRP price approaches $1.5 again, the BIS published a noteworthy study regarding the $XRP ecosystem.

    At this point, the Bank for International Payments (BIS) announced that it used XRPL in a proof-of-concept study for formal data validation.

    According to the official statement, the BIS used the $XRP Ledger in a proof-of-concept blockchain-based system to verify the accuracy of official statistical data.

    BIS researchers have announced in a new study that they have developed a proof-of-concept on the $XRP Ledger (XRPL) to improve the verifiability of official economic and financial data.

    The system could be used to verify whether official statistics such as GDP, inflation, and interest rates have been manipulated and to confirm the data source.

    The study noted that the system does not record all economic or financial data on the blockchain, i.e., XRPL; instead, a cryptographic fingerprint (hash) is created from the data, and this record is stored on the $XRP Ledger. This allows users to verify whether their data file matches the original publication and whether the data has been altered.

    The prototype developed by BIS researchers reportedly completes the publishing process in 3 to 5 seconds and the verification process in 1 to 2 seconds. However, it was emphasized that the research is still in the technical validation phase and BIS has not yet decided whether to use XRPL in a real system.

    Why was $XRP Ledger chosen?

    What made the study noteworthy was that BIS researchers chose $XRP Ledger from among numerous blockchains.

    Researchers cited XRPL’s low transaction fees, fast transaction speed, and development environment as reasons for choosing it.

    In this context, the new study revealed that $XRP Ledger can be used not only as a payment infrastructure but also to verify data integrity.

    In conclusion, while BIS’s XRPL test isn’t direct news of $XRP adoption, it’s seen as a noteworthy development in terms of the network’s potential for enterprise use.

    *This is not investment advice.

  • U.S. added stronger than expected 162,000 jobs in August as labor market bounced back

    U.S. added stronger than expected 162,000 jobs in August as labor market bounced back

    The U.S. labor market strengthened appreciably in August, giving the growing group of hawks at the Fed more ammunition to hike interest rates at the bank’s policy meeting in less than two weeks.

    According to the government’s Nonfarm Payrolls report released Friday morning, the U.S. economy added 162,000 jobs last month. That was well above the consensus estimate of 56,000 and followed the addition of 21,000 jobs in July (revised from an originally reported decline of 23,000).

    The unemployment rate came in at 4.1% versus 4.1% expected and July’s 4.1%.

    Reaction in markets was swift, with bitcoin tumbling about 2% to below $80,000. The U.S. 10-year Treasury yield jumped 3.3 basis points to 4.80%. U.S. stock index futures are modestly lower.

    Will they, or won’t they

    Federal Reserve Chairman Kevin Warsh put a September rate hike firmly on the table one week ago today with his hawkish Jackson Hole speech.

    But Fed Governor Chris Waller (with an assist from FRBNY President John Williams) this week sent markets surging by suggesting a rate hike at the bank’s policy meeting in two weeks was far from a done deal.

    This morning’s jobs report is another data point in favor of the hawks, but the key figure in the Fed’s decision is likely to be next Friday’s CPI report for August.