Category: Business

  • Banks could slow stablecoin growth by paying savers more, BIS paper finds

    Banks could slow stablecoin growth by paying savers more, BIS paper finds

    The findings add evidence to a debate that has drawn warnings from bank executives. Bank of America CEO Brian Moynihan warned in January that as much as $6 trillion in deposits could move into stablecoins and related products offering returns, potentially reducing lending capacity and raising borrowing costs.

    The effect is partly based on where issuers put their reserves. A December Federal Reserve staff analysis explained that money placed in stablecoins can return to banks as issuer deposits, changing who supplies banks’ funding even when total deposits remain unchanged.

    Larger, uninsured balances could require banks to keep more liquid assets and leave less room for long-term loans that financial institutions issue.

    Paying more to retain customers also raises banks’ funding costs. The Fed analysis suggested banks could target better rates at customers most likely to switch, while keeping lower rates for less mobile depositors.

    The BIS paper does not establish losses of bank deposits or lending. Its sample covers one high-rate episode, and the findings may change as yield-bearing stablecoins and tokenized money market funds gain ground.

    Banks “retain some influence over the pace of that adoption through deposit pricing,” the authors wrote.

  • Sell Alert on Altcoin That Surged 370 Percent: Massive Inflows of Tokens to Binance

    Sell Alert on Altcoin That Surged 370 Percent: Massive Inflows of Tokens to Binance

    In contrast, the $UNI price has fallen by over 30% from its recent peak of $10.90. Darkforth noted that $UNI inflows to Binance reached their highest levels of the year during this period.

    The fact that inflows into the stock market exceeded $40 million on some days at the end of September revealed the magnitude of the movement. The Z-score, which measures the deviation of inflows from the usual level, also rose above the 4 level on multiple occasions.

    The analyst says that while stock market inflows are still high, they are starting to slow down. He believes that if this trend continues, the correction may be over.

    *This is not investment advice.

  • Boy, 5, diagnosed with rare ‘childhood dementia’ after specialist saw symptom in his face

    Boy, 5, diagnosed with rare ‘childhood dementia’ after specialist saw symptom in his face

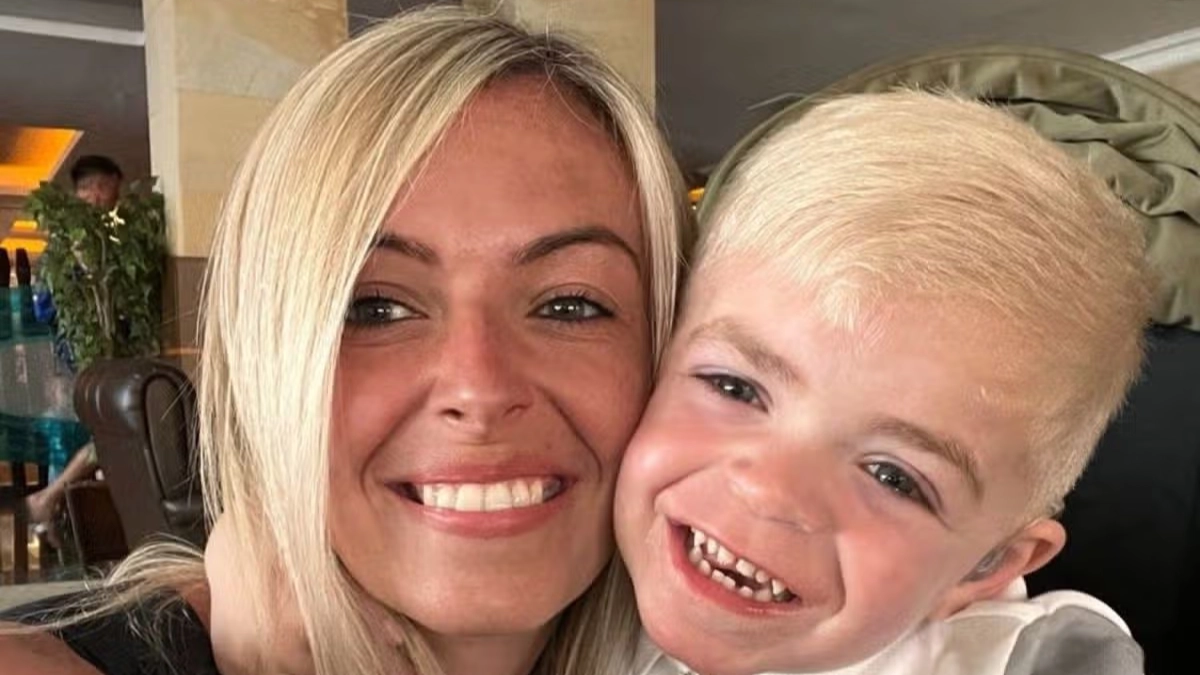
    A mum is raising awareness of her five-year-old son’s condition, often referred to as ‘childhood Alzheimer’s or dementia’.

    Sanfilippo syndrome is a rare, fatal genetic neurodegenerative disorder, affecting roughly 80 to 100 babies every 10 years.

    Sophie Lowe’s son Bobby was diagnosed after the speech and language therapy team noticed a delay in his speech development in 2024.

    “The symptoms are similar in some respects to older people’s dementia in terms of the commonly known ones like memory or mobility as the child gets older but in babies, they aren’t always apparent,” Sophie, who works for Blackpool Teaching Hospital Trust, explained.

    “The key symptoms in children with Sanfilippo syndrome are around speech and language delay, frequent infections and mild physical features.”

    Children diagnosed with Sanfilippo syndrome rarely live beyond their early teens and the mother wants to make sure ‘Bobby gets the most out of his short life expectancy’.

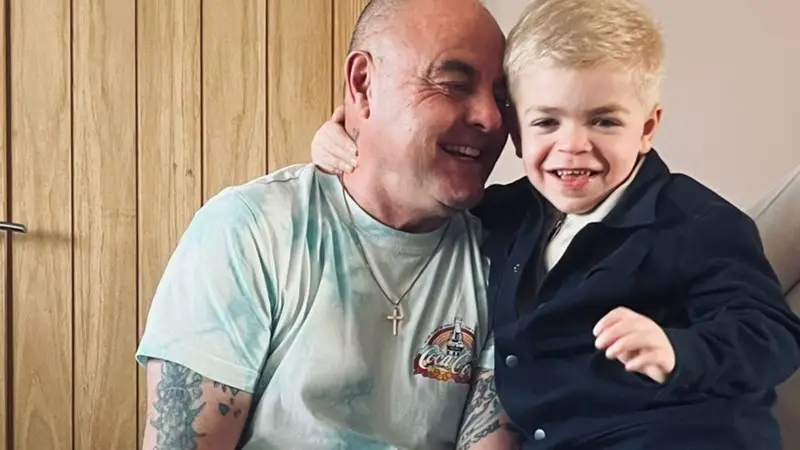
    Sophie said Bobby was close to her dad Alan, who unexpectedly passed away earlier this year (JustGiving)

    Sophie said Bobby was close to her dad Alan, who unexpectedly passed away earlier this year (JustGiving)

    Childhood dementia has a similar mortality rate to childhood cancer, with 204 recorded deaths per year from the condition compared to 260 annual childhood cancer deaths.

    “He loves animals, tractors and nature so we want to spend as much time as we can giving him the chance to experience life as much as he can; and to get as much quality time with him while he is around,” she said.

    “To us he was our baby, you don’t notice things that others might call ‘abnormalities’ you just brush them off because you love your child and you love them however they develop.”

    Sophie is surprised that not more people are aware of Sanfilippo syndrome.

    “If it’s causing a similar number of deaths as childhood cancer then why aren’t we paying more attention to it? Some consultants we have encountered don’t know what it is,” she added.

    Sophie says she wants to make sure ‘Bobby gets the most out of his short life expectancy’ (Facebook)

    Sophie says she wants to make sure ‘Bobby gets the most out of his short life expectancy’ (Facebook)

    “I do admit though that the consultants we have been involved with have done their best to at least familiarise themselves with the condition before we meet with them.

    “I can often see a page on their screen which shows they’ve looked it up before we arrive.

    “Again, this is something we have noticed that makes the appointment more person centred when a specialist has taken the time to check on our individual circumstances.

    “That’s great but I want to do more to make people aware of the condition in the first place.”

    Sophie’s dad Alan died unexpectedly passed away in March, as she says he and Bobby shared ‘an incredibly special bond’.

    At the time of writing, over £5,000 has been raised on JustGiving, as Alan’s close friend Kass is walking from Brighton to Blackpool to raise money for Bobby and awareness of his condition.

    “The money raised will help with Bobby’s care and the many additional needs that come with living with Sanfilippo syndrome. As his condition progresses, his needs become increasingly complex, and the financial pressures can be overwhelming,” Sophie writes.

    “The funds will help us provide specialist care, equipment, activities, experiences and support to make Bobby’s life as comfortable, fulfilling and joyful as possible.”

  • Bitcoin’s inflation hedge has a hidden cost, and leverage makes it worse

    Bitcoin’s inflation hedge has a hidden cost, and leverage makes it worse

    One Bitcoin bet, three different bills

    Someone who buys $10,000 of Bitcoin with cash has no interest payments to make while holding it. The coins can rise or fall in price without a lender demanding repayment.

    The Federal Reserve’s interest-rate release showed a 4.26% three-month Treasury constant-maturity yield for Oct. 13, the day before the CPI report. While that’s an annualized market benchmark, it still illustrates what we call opportunity cost. If $10,000 could earn 4.26% for an entire year, the return would be $426 before taxes.

    If Bitcoin ended the year at the same price it was bought for, its holder would have no trading loss, but they would have missed that hypothetical alternative return. So even though cash buyers don’t get an interest bill, choosing a non-yielding asset has an economic cost when other investments offer income.

    Now consider another investor with the same $10,000 who borrows an additional $10,000 at a hypothetical 8% annual rate and buys $20,000 of Bitcoin.

    The investor has doubled the exposure and also accepted an $800 annual interest obligation. If Bitcoin ends the year at the same price, selling the position and repaying the $10,000 loan plus $800 interest leaves him with $9,200.

    The first investor breaks even before fees, and the second loses 8% of their own capital without Bitcoin falling at all.

    That difference becomes easier to see across several possible outcomes:

    Hypothetical one-year outcomes. Both investors start with $10,000 of their own money. The borrower pays 8% interest on a $10,000 loan. Figures exclude taxes, fees, and any early liquidation.

    The leveraged investor needs Bitcoin to jump 4% just to cover the $800 interest bill. Matching the cash investor’s illustrative $426 alternative return would require a 6.13% Bitcoin gain.

    At a 10% price increase, leverage helps the borrower earn more than the cash buyer. But at a 10% decline, it makes the loss substantially worse.

    And the table assumes something real markets don’t always allow: that the borrower gets to hold the position for a full year.

    If Bitcoin falls sharply along the way, a lender can demand additional collateral or liquidate a position before the eventual recovery arrives. Investors may be right about where Bitcoin finishes and still be unable to remain invested long enough to benefit.

    Futures can hide the cost in the entry price

    Bitcoin futures can easily obscure leverage, making the financing charge less obvious.

    Dated futures contracts let traders take on Bitcoin exposure at a price agreed today for settlement later. That price can be above the current spot price, creating what traders call the futures basis.

    Suppose Bitcoin trades for $80,000 in the spot market while a contract settling in 90 days trades for $81,200.

    The $1,200 premium equals 1.5% of the spot price, or about 6.08% annualized. If Bitcoin’s spot price is still $80,000 at settlement, the long futures position loses $1,200 per Bitcoin of exposure as the contract converges toward the underlying price.

    The trader never had to take out a loan to experience that difference, because the premium was embedded in the entry price.

    This is where we start to see the connection to interest rates. Traders who buy spot Bitcoin and sell a more expensive future may need to borrow to fund the spot purchase, so inflation, which affects the cost of dollar financing, can influence that premium.

    Future prices also reflect the demand for leveraged exposure, and show the capital available for arbitrage. They also reflect the trading constraints investors face when dealing with derivatives.

    Spot and futures observations need to be matched in time before their difference means anything. A premium calculated from unrelated price snapshots can easily describe a trade nobody could execute.

    Unlike dated contracts, perpetual futures have no scheduled expiry, and exchanges use funding payments to keep their prices near a reference market.

    Under Deribit’s published rules, positive funding means long positions pay short positions, while negative funding means shorts pay longs.

    That makes funding different from a fixed borrowing rate. It can rise, fall, or change direction depending on how traders are positioned. Government borrowing costs can remain high while perpetual funding turns negative during a market sell-off.

    Neither a Treasury yield nor an annualized funding quote tells an investor the full cost of a derivatives position by itself.

    Collateral can earn interest, depending on the venue and how the account is funded. Margin requirements can change, trading fees matter, and funding payments must be measured over the actual holding period.

    A careful calculation also avoids charging the same financing expense twice. The price difference built into a dated future and the separate cost of borrowing to fund collateral are not automatically two complete versions of the same loan bill.

    An inflation hedge isn’t the same as an inflation adjustment

    Bitcoin’s long-term scarcity case is often presented as protection against currencies losing purchasing power. Its supply is capped at 21 million coins, and investors such as Michael Saylor have helped make that argument central to corporate Bitcoin ownership.

    But the supply cap doesn’t mean its price rises when CPI increases.

    Inflation measures changes in the prices people have already paid for goods and services, while Bitcoin’s return depends on what future buyers are willing to pay. Those are different processes, even if investors believe the former will eventually strengthen demand for the latter.

    Treasury Inflation-Protected Securities (TIPS) adjust their principal with changes in the relevant inflation index, and the security’s terms include the inflation adjustment.

    The ten-year inflation-indexed Treasury had a constant-maturity yield of 2.88% on Oct. 13. That’s a useful benchmark, though an investor selling a TIPS early can still lose money if market yields rise and the security’s price falls.

    Investors can compare several assets with different income streams, inflation exposures, liquidity needs, and market risks.

    A Bitcoin holder is not necessarily wrong about the eventual effect of inflation, but future appreciation must be large enough to justify what holding the position costs along the way.

    The appeal of Bitcoin’s limited supply doesn’t depend on a single monthly inflation report, nor can one strong CPI reading prove that Bitcoin will outperform cash, bonds, or other assets over the next several years.

    Higher borrowing costs change how long some investors can afford to wait for that outcome.

    Cash buyers can hold through a disappointing year, accepting the income forgone elsewhere. Borrowers must find the interest money and maintain enough collateral to avoid being closed out, while futures traders must manage the contract’s premium, funding, margin requirements, and eventual exit.

    All of them can see the same future for Bitcoin but end up with very different results.

    Bitcoin might recover from an ugly decline and finish above the original purchase price, yet the leveraged investor who was liquidated during the fall will see none of that recovery.

    Inflation can strengthen the case for owning Bitcoin, but expensive financing can shorten the time available to prove that case right.
  • The hidden trade behind Strive’s 16.7% Bitcoin income offer

    The hidden trade behind Strive’s 16.7% Bitcoin income offer

    The upsized offering is expected to raise $630 million before expenses, with settlement scheduled for Oct. 20. Strive will use the proceeds to acquire Bitcoin, support its business, buy income-generating assets, or repurchase other shares.

    The eye-popping yield makes the product easy to advertise and sell. However, it doesn’t tell us what an investor bought for $90, or what that investment would be worth if they needed their money back.

    A $100 claim is not a $100 exit

    SATS is preferred stock, which means its owners are in a different position from shareholders who buy Strive’s ordinary stock.

    Common shareholders receive whatever value remains after the company satisfies its liabilities and more senior claims. Preferred holders receive contractual payment rights and a higher place in the repayment order, but their upside is generally more limited.

    Strive’s prospectus sets an initial liquidation preference of $100 per SATS share, subject to adjustments that can’t reduce it below $100.

    That preference determines the claim investors can assert under the relevant liquidation provisions, and it doesn’t mean a holder can demand $100 whenever they want to sell.

    The market price depends on what another buyer is willing to pay for the dividend stream and its associated risk. That’s the most important difference by far, particularly because SATS is perpetual. There’s no maturity date when the company must return the investor’s original purchase price.

    So, a share bought at $90 could trade at $100 or more if buyers get comfortable with the company’s finances and accept a lower yield. It could also fall to $75, even if Strive continues making every scheduled payment.

    The calculation is straightforward:

    Illustrative yields calculated from the $15 annual dividend. Market prices other than the $90 offering price are hypothetical. Cash yield excludes price changes, fees, and taxes.

    Someone who pays $90, collects $15 over a year, and sells for $75 receives $90 in total before costs. If every dividend were paid on time, the investor would still have made nothing.

    If the resale price falls further, the payments might not even cover the capital loss. If it increases, the buyer can earn more than the advertised income. That’s why the advertised 15% is just a contractual dividend rate.

    Strive’s preferred shareholders still stand in line

    The word preferred might sound like a promise of safety, but its value depends on who stands above and below the investor in practice.

    SATS ranks ahead of Strive’s common shares for dividends and liquidation distributions, but behind all of its existing SATA preferred stock. Debt and certain obligations at subsidiaries also take priority, while the company retains the ability to issue additional securities with equal or higher ranking.

    Consider a simplified company with $200 available after other liabilities, $100 owed to senior preferred shareholders, and $50 owed to junior preferred holders. The remaining $50 belongs to common shareholders, so a $40 decline in available assets would hit common shareholders first.

    Another $30 decline would wipe out the remaining common value and leave the junior preferred holders $20 short, but the senior preferred claim would still be covered.

    That’s the protection junior preferred owners are buying: common equity can absorb some losses before they do. But that protection thins as senior claims grow or the company’s asset value falls. For Bitcoin treasury companies, both can happen at once.

    Strive can raise money by issuing more securities and use the proceeds to buy additional Bitcoin. That way, its holdings rise, but so do the financial claims attached to the business. A growing Bitcoin balance doesn’t automatically mean every shareholder’s position has improved equally.

    Strive’s October Bitcoin purchases lifted gross Bitcoin per effective common share by just 1.72%, despite a much larger increase in its total holdings.

    SATS buyers are exposed to the same basic tension: the company can grow while the protection underneath an individual claim changes.

    There are additional rights in the SATS terms, including a holder repurchase right following a defined fundamental change, generally at the $100 stated amount plus accumulated unpaid dividends. Strive also has limited redemption rights under specified conditions.

    These provisions aren’t substitutes for an everyday right to sell at $100. In normal trading, the exit price is whatever the market provides.

    Daily dividends still need a source of cash

    SATS dividends are scheduled to begin on Nov. 9 and be payable every business day.

    At seven million shares, the $15 rate implies $105 million in annual SATS dividends. Strive intends to establish a reserve of $22.50 per share at closing, or $157.5 million total, representing 18 months of scheduled dividends.

    The reserve will provide an initial payment buffer, but it won’t turn Bitcoin into an interest-paying asset or establish that the company can fund the same payments indefinitely. Strive’s prospectus anticipates using further capital raising as a primary source of dividend funding beyond the initial reserve period.

    Income promises accumulate even though the underlying asset doesn’t produce a cash return.

    SATS buyers are essentially relying on Strive to maintain enough liquidity to make payments, enough asset value to support their claim, and enough market confidence to preserve a reasonable resale price.

    Strive isn’t the only company using preferred securities to finance corporate Bitcoin exposure, since Strategy has also built a substantial preferred-share business of its own. Keeping these securities attractive can become an ongoing capital-allocation task.

    Preferred dividends can be funded in a lot of different ways, including through cash reserves, new financing, investment income, or asset sales. Each choice significantly changes the company’s position: issuing more claims creates future obligations, while selling assets reduces holdings the business might otherwise retain.

    Bitcoin appreciation can increase the balance sheet’s value. But that appreciation can’t turn into cash in the corporate bank account until a transaction converts it into spendable funds.

    A perpetual preferred share from a Bitcoin treasury company is a legitimate investment, since some investors prefer a defined income claim over common equity.

    The offering’s $90 price is the most important aspect covered here, because it puts a real cost on that choice. It means that investors are demanding the equivalent of 16.7% a year if payments continue in full.

    That unusually high indicated cash yield shouldn’t be mistaken for free income, though. That’s the compensation investors are offered for risks related to payment capacity, claim priority, duration, and resale value.

    That’s why the most important comparison we can make here isn’t between SATS and Bitcoin, but between the dollars a buyer pays today, the dollars Strive can distribute over time, and the dollars another investor will eventually pay to take over that claim.

    While Bitcoin drives appreciation in Strive’s underlying business, the company itself delivers the dividend promise. The market now decides what that promise is worth.

  • I went to my first NFL game in London and finally understood the American obsession

    I went to my first NFL game in London and finally understood the American obsession

    It’s 13 minutes to kick off and Jaxson de Ville is about to launch himself off the top of Tottenham Hotspur stadium.

    If this is to be a drab NFL match-up, watching a person in a Jaguar mascot suit suspended 100ft in the air wondering what they signed up for is incredible consolation viewing.

    Is this how the Romans felt when Maximus Decimus Meridius entered the Colosseum? More importantly, has Chirpy the cockerel ever been suspended above the centre circle before a Spurs home game?

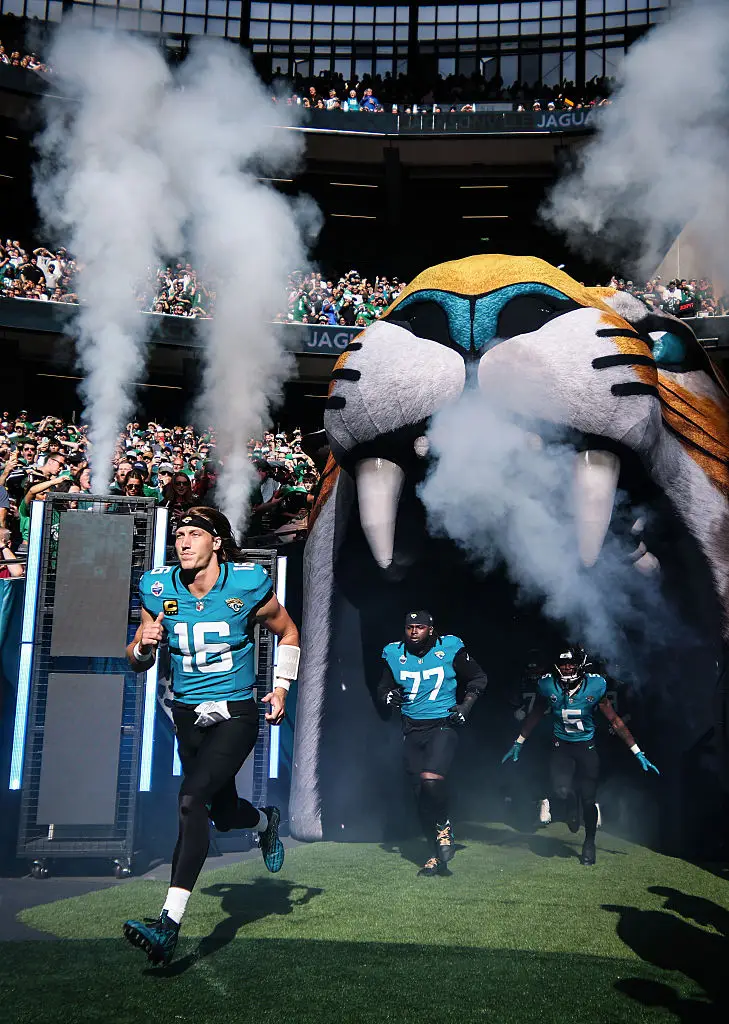
    And if you thought Philadelphia Eagles at Jacksonville Jaguars would be a watered down international exhibition then it’s abundantly clear that it isn’t; the Philly fans boo the Jags entering their official home game at maximum lung-busting hostility.

    Of course it’s not unusual for the home team to be booed off at this ground, but booed on. Sensational.

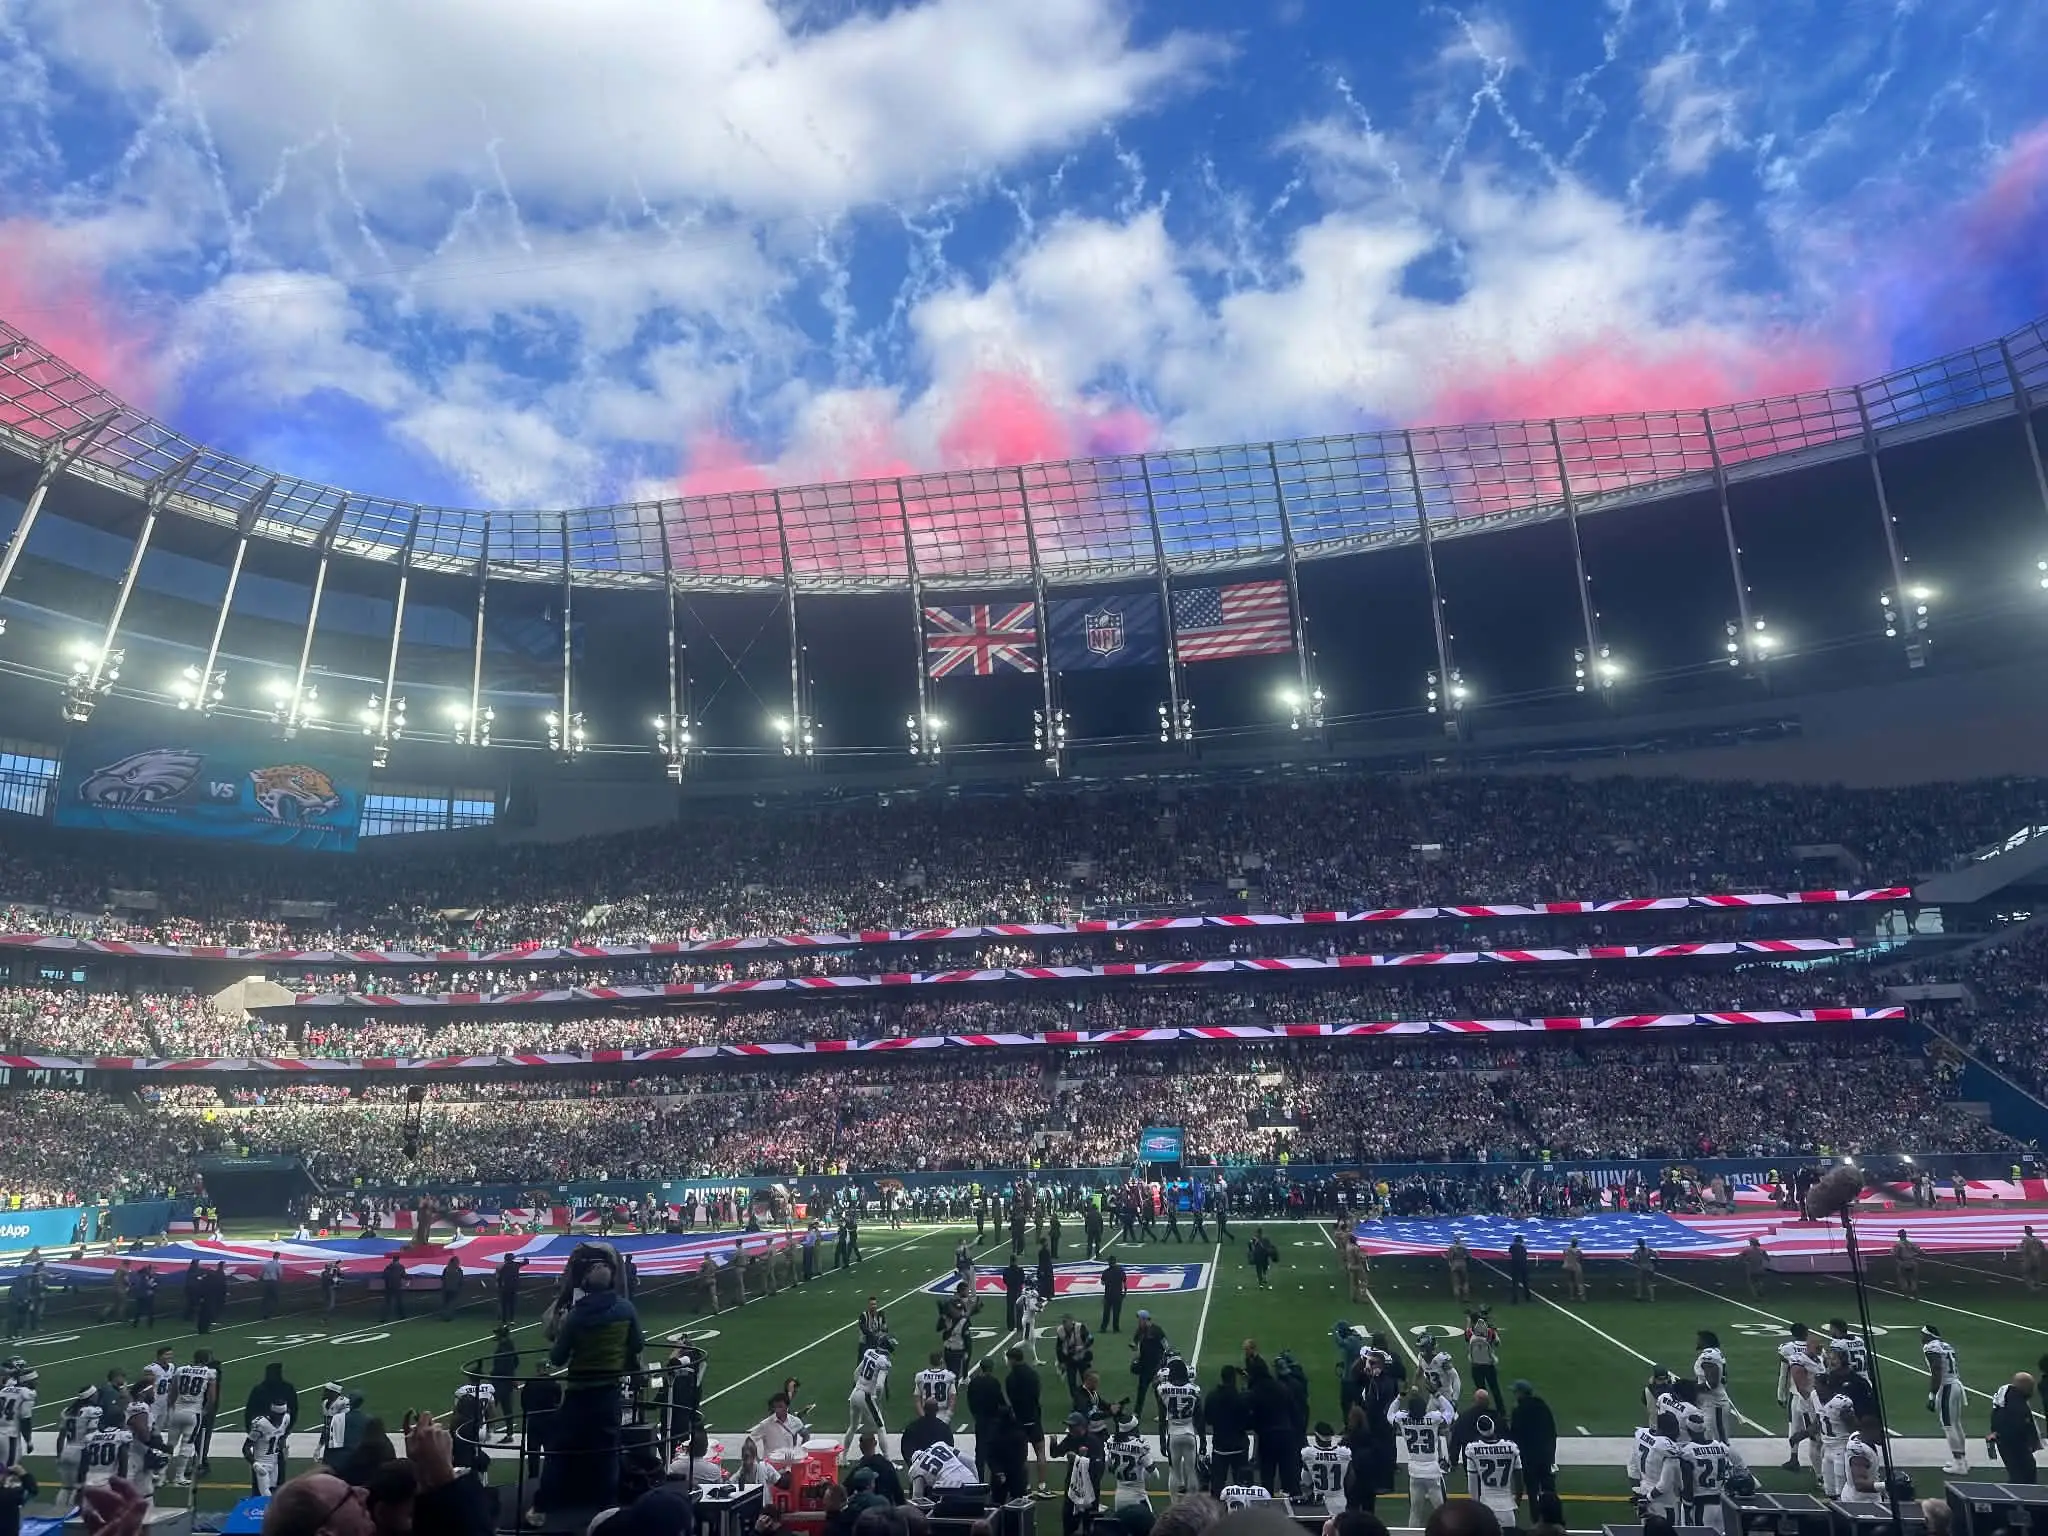
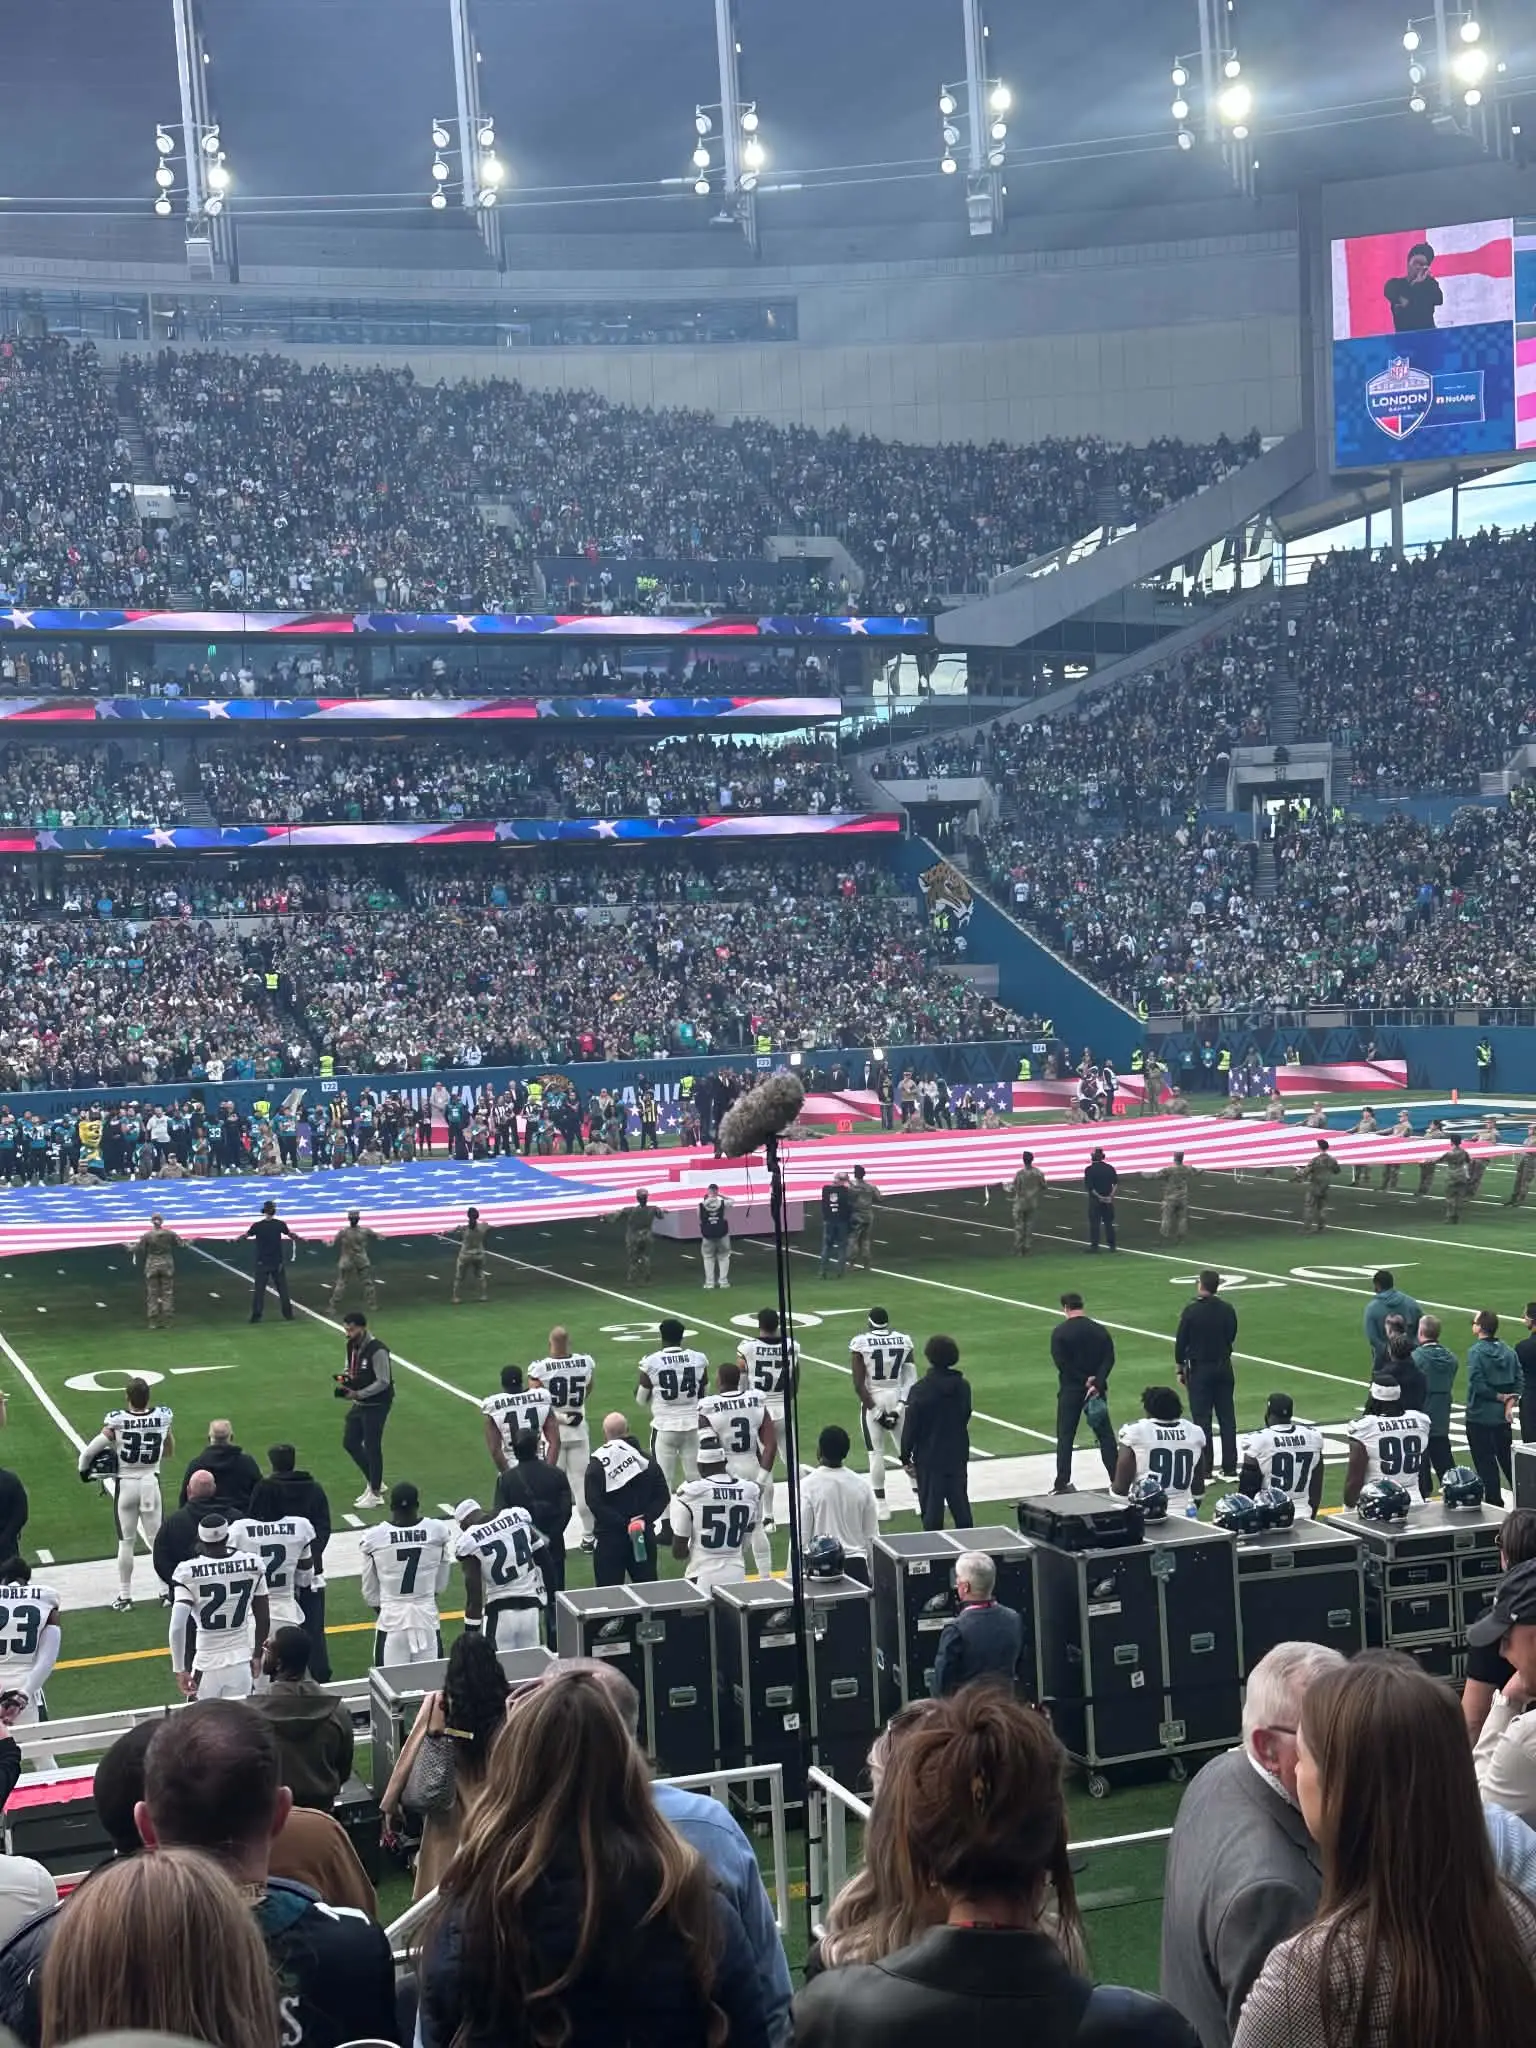
    After the match ball is naturally delivered via a cardboard FedEx box and everyone has finished belting out the national anthems, there’s a disallowed touchdown inside the first 13 seconds followed by an on-field tear up in a blistering start to the game.

    Jacksonville getting booed onto their own home turf out of a giant Jaguar head. (Ryan Pierse/Getty Images)

    Jacksonville getting booed onto their own home turf out of a giant Jaguar head. (Ryan Pierse/Getty Images)

    It’s clear Americans don’t do things by halves and this is an exhilarating introduction to one of the biggest sports on earth.

    But why am I here? This is my first live American Football game and I am bang up for the occasion to see what this sport is all about, along with a record 61,000 fans in attendance.

    A patriotic start to proceedings (LADbible)

    A patriotic start to proceedings (LADbible)

    Marriott Bonvoy, an official sponsor of the NFL, has appointed NFL veteran Efe Obada as its ‘Check-In Coach’, sharing advice for travellers building a trip around the main event.

    His advice is straightforward: “Book your hotel, know how you’re getting to the main event and ask people who know the city for advice.”

    It’s pretty clear how we’re getting there, tube-hopping to the stadium you only have to follow echoes of “Go Birds” between each passing Philly supporter. From then on just follow every ‘jersey’ you can possibly imagine marching up Tottenham High Road.

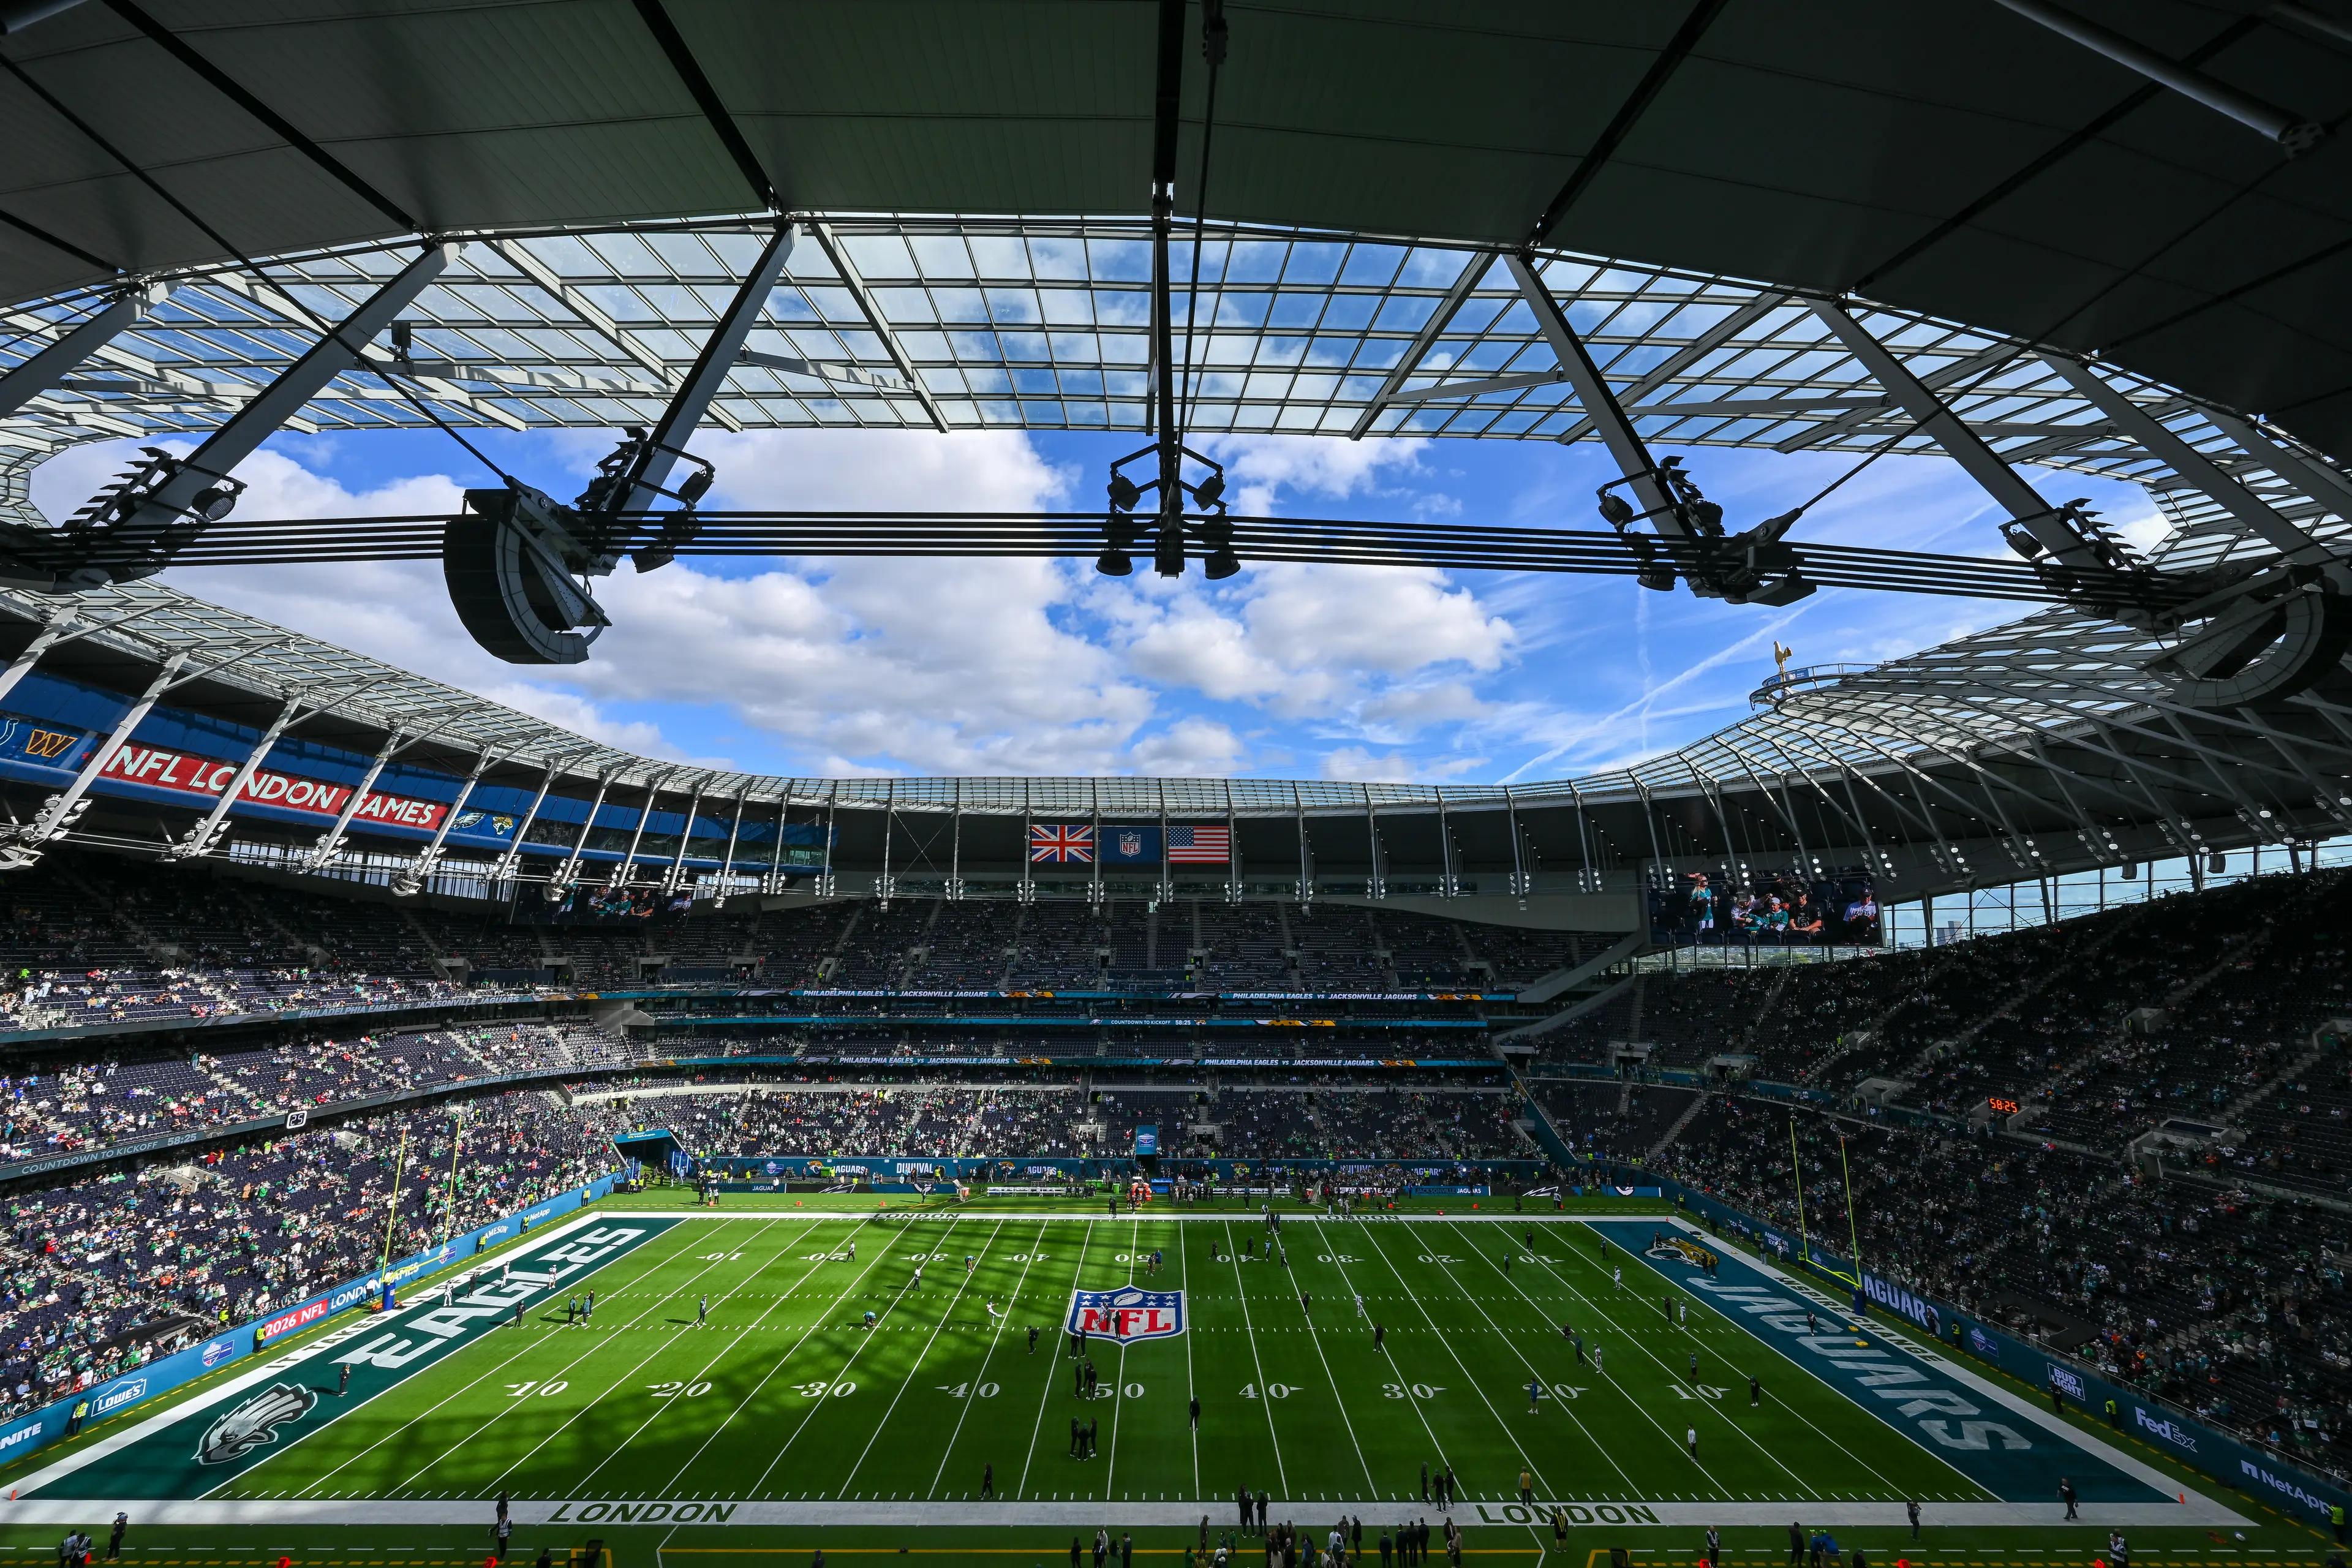
    The Tottenham Hotspur Stadium is made for hosting NFL (Defodi Images/Getty Images)

    The Tottenham Hotspur Stadium is made for hosting NFL (Defodi Images/Getty Images)

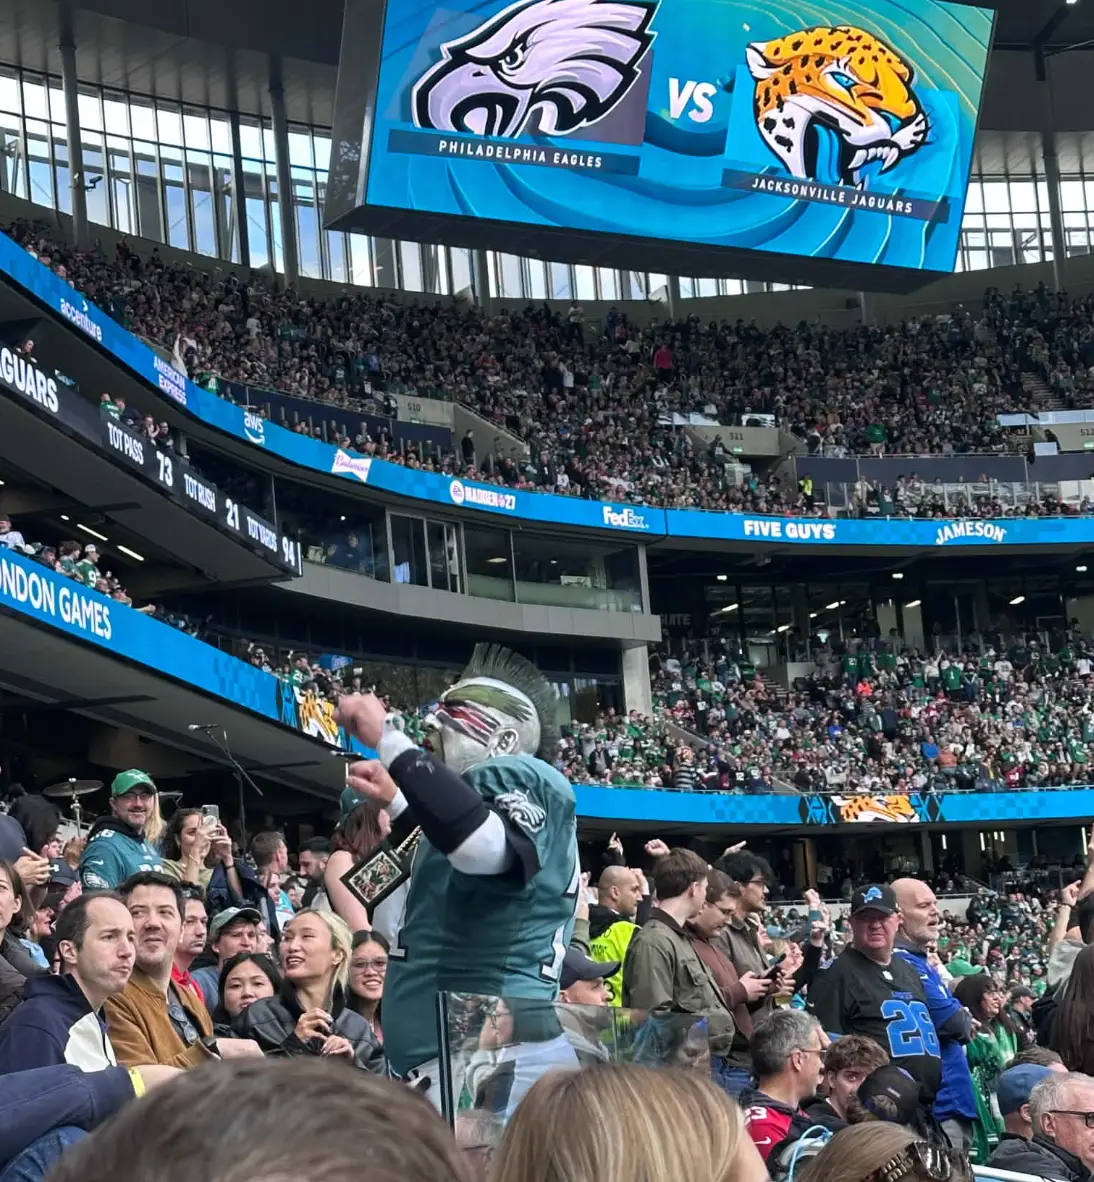
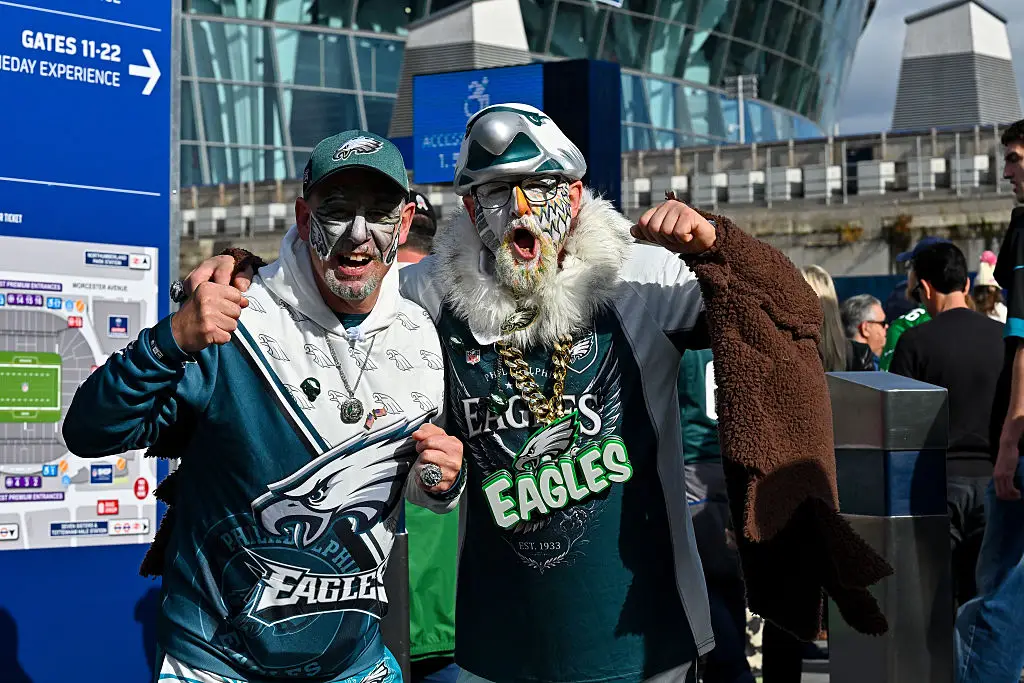
    Some have taken the dress code more seriously than others. Special mentions go out to the convocation of grown men dressed as eagles by the burger van outside the ground, and the Philly Sports Guy, a silver-faced, green mohican sporting Eagles superfan with a Union Jack across his nut for the occasion.

    Philly's number one fan getting the crowd going (LADbible)

    Philly’s number one fan getting the crowd going (LADbible)

    Inside, the transformation goes considerably further than face paint. Tottenham Hotspur Stadium has a dedicated NFL playing surface set 1.6 metres below where the football pitch would usually sit. This place is built for hosting NFL and doesn’t feel like a makeshift venue.

    Us Brits go into American Football with preconceived ideas, there are too many breaks in play, but maybe Tommy Tuchel could have done with a tactical timeout against Argentina then we might have reached the World Cup Final.

    There’s a band thrashing out rock tunes during breaks in play, the giant stadium screens are trying to hone in on the next Coldplay couple, people are firing t-shirts out of air-powered bazookas from the sidelines and there’s even a half time show.

    National anthems deliver a spectacle before the game (LADbible)

    National anthems deliver a spectacle before the game (LADbible)

    The breaks might be the thing that put some impatient Brits off watching on TV, but in the stadium there’s plenty competing for your attention while the players regroup.

    It’s clear why people build a weekend around it when the game goes international. Research commissioned by Marriott Bonvoy found 62% of Brits plan trips around sporting, music and cultural events, while 45% say an event has taken them somewhere they might not otherwise have visited.

    But all the entertainment around the pitch would struggle to compete with what happens in the final eight seconds.

    The Eagles take a one point lead into the dying embers of the game and somehow still manage to lose it. Cam Little’s 57-yard field goal seals a 19-17 win for the Jags, and suddenly those breaks in play feel like a pretty minor complaint.

    "Go Birds!" (De Fodi Images/Getty Images)

    “Go Birds!” (De Fodi Images/Getty Images)

    I am converted and aside from belting out the national anthem ahead of kick off, I feel truly American for an entire 60 minutes on the game clock that somehow turns into 3 and a half hours.

    Would I buy a ticket to go again? Yes. You don’t need to arrive knowing every rule to get something out of this. Come for the spectacle and you might find yourself caring an awful lot about where a ball lands in the final second.

  • Katie Zacharia speaks out as she’s fired from White House press secretary role after just 5 days

    Katie Zacharia speaks out as she’s fired from White House press secretary role after just 5 days

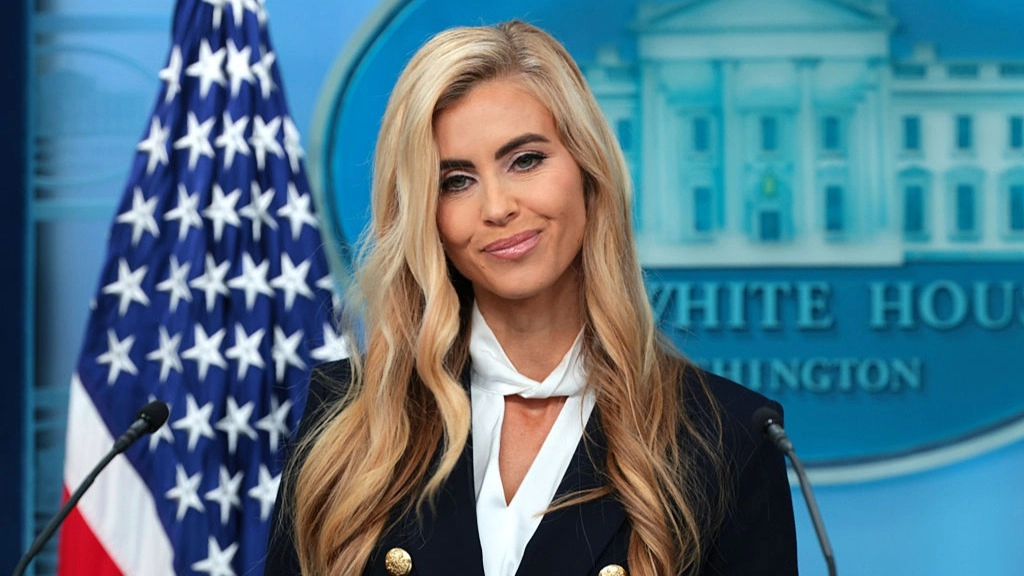
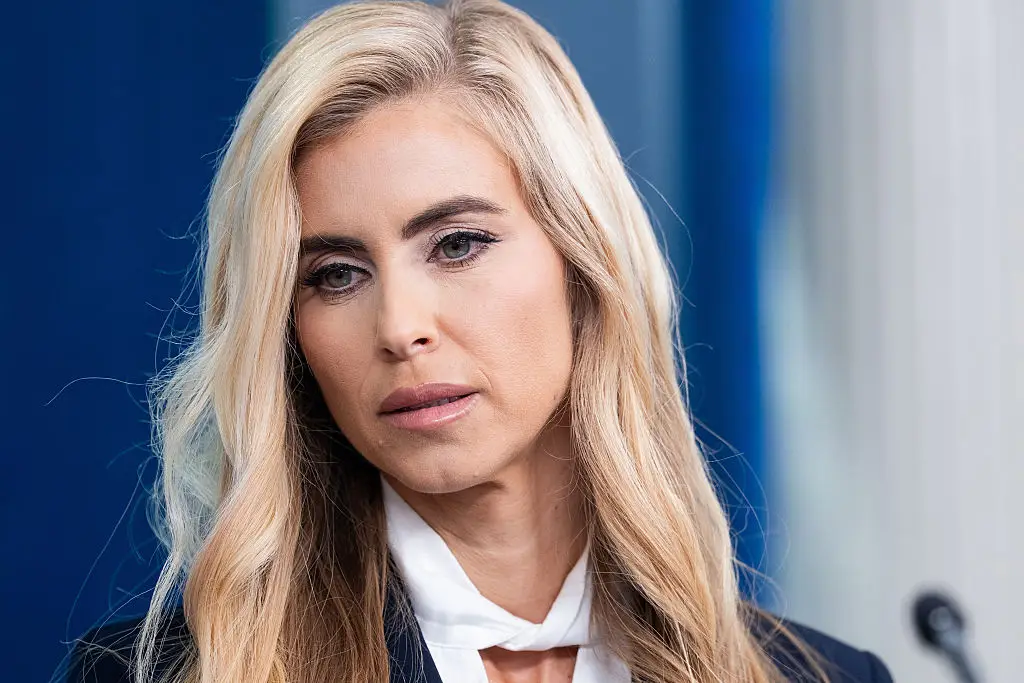
    Katie Zacharia has praised Donald Trump after she was axed from her role as White House press secretary following a rocky inaugural briefing.

    A person familiar with the matter said on Friday (16 October) that Zacharia, 42, would be transitioning out of the role after just five days in it.

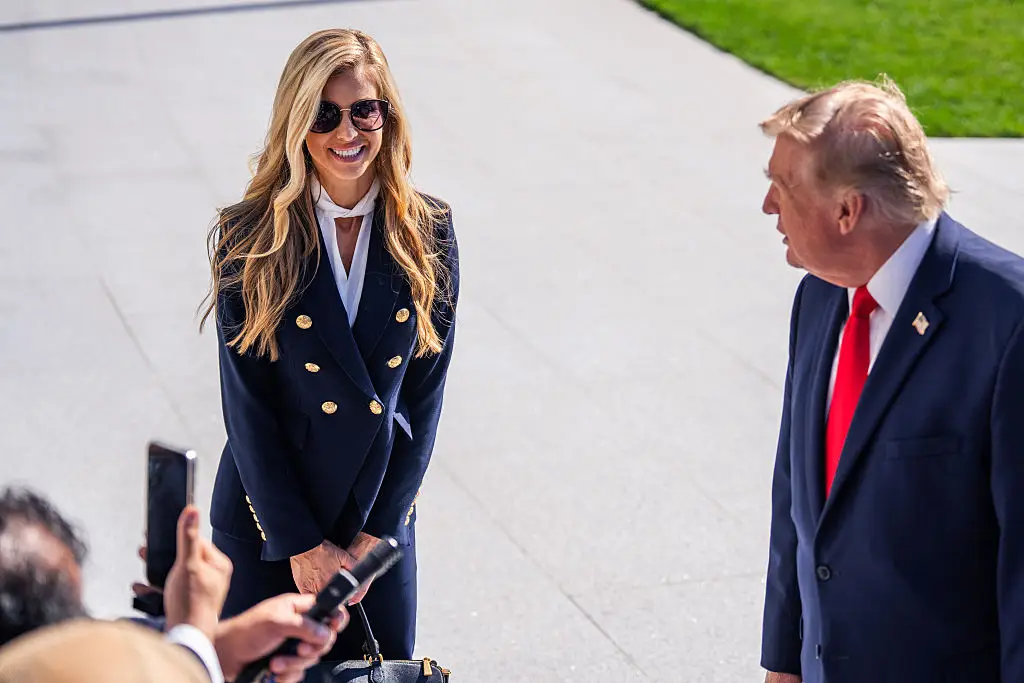
    Taking to X, she wrote alongside a photo of herself and Trump that it was ‘an honor to work for him’.

    “President Trump is a kind, wonderful, gracious, thoughtful, enthusiastic, and hardworking man,” she penned.

    “I wish more Americans appreciated him. No one will ever make America great the way he has and continues to.”

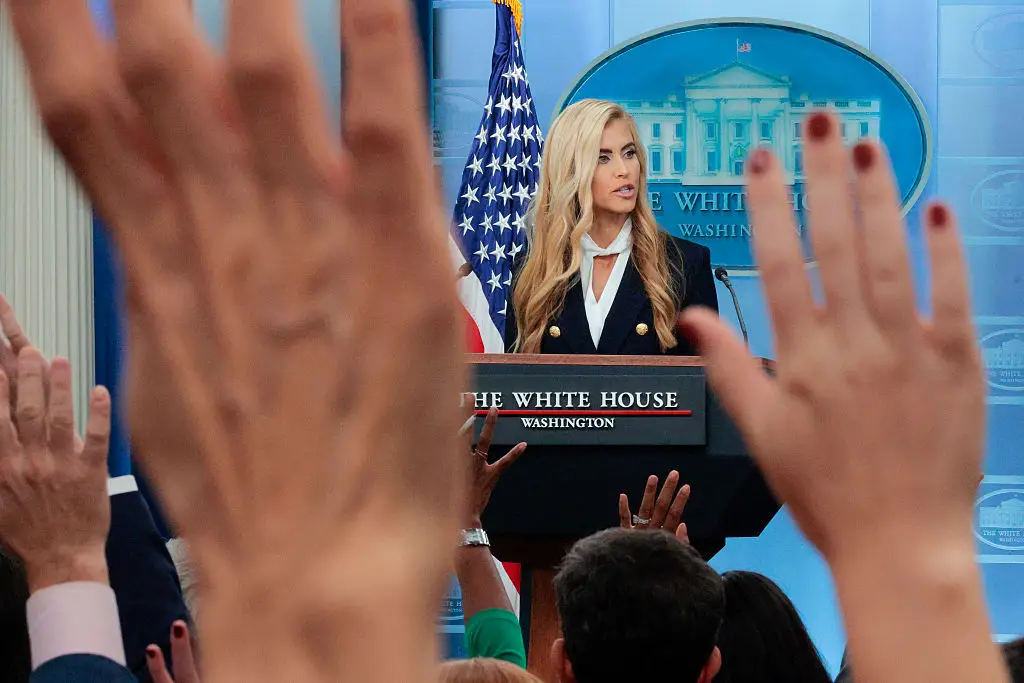
    During the 14-minute briefing on Tuesday, Zacharia visibly struggled to answer just three questions. She spent more than half that time reading pre-prepared remarks.

    Zacharia struggled during her first inaugural briefing (Chip Somodevilla/Getty Images)

    Zacharia struggled during her first inaugural briefing (Chip Somodevilla/Getty Images)

    When asked by Fox News if the US had stopped sharing intelligence with Ukraine, she said she would ‘have to get back to you on that’.

    There was also an awkward moment when she referred to ‘my president’ instead of ‘my husband’.

    Following on from Karoline Leavitt, Zacharia was a surprise choice when Trump announced her appointment earlier this month.

    He said he told Zacharia that she might want to change her mind about the job, and said he thought she had been treated unfairly by the press.

    “I told her, ‘I think you’re better off being happy’,” Trump told reporters on the White House lawn as he left for a rally in Georgia.

    Zacharia praised Trump and said that it was ‘an honor to work for him’ (Tom Williams/CQ-Roll Call, Inc via Getty Images)

    Zacharia praised Trump and said that it was ‘an honor to work for him’ (Tom Williams/CQ-Roll Call, Inc via Getty Images)

    “I said, ‘Honestly, if I were you, I’d reconsider’. I said, ‘You think about it, but I would reconsider’.

    “‘Katie, do you need this? I don’t think you need this’,” and that he wanted ‘her to have a good life’ and not be subjected to criticism, which he likened to being ‘brutalised by the media’.

    On Friday, Zacharia was asked by Fox News if she had the president’s confidence and responded: “I hope to be able to build the trust and confidence of everyone around me.”

    Zacharia graduated from Pepperdine University’s Seaver College in 2007 and the Caruso School of Law in 2011.

    Zacharia was fired after just five days in the job (Aaron Schwartz/Bloomberg via Getty Images

    Zacharia was fired after just five days in the job (Aaron Schwartz/Bloomberg via Getty Images

    That year, she married film producer Tyler Zacharia and the couple has four children.

    She has spoken publicly about being adopted as a newborn and meeting her biological mother Ruth at 18.

    After graduating, she and her husband moved to Beijing, where she worked as an international legal consultant/associate at the Zhong Lun Law Firm and managed fundraising and communications for Compassion for Migrant Children.

    However, the conservative commentator had long called herself a lawyer when she had not passed a bar exam.

    Before becoming White House Press Secretary in October 2026, Zacharia worked as a senior communications adviser for Trump Media & Technology Group, the company operating Truth Social, and briefly served as the deputy assistant secretary for public affairs at the US Department of Homeland Security (DHS) in early 2026 before resigning after about a month.

  • Horror details emerge after nine children found ‘locked in cages’ in ‘deplorable’ home

    Horror details emerge after nine children found ‘locked in cages’ in ‘deplorable’ home

    A couple from Ohio have been arrested on charges of child endangerment after allegedly forcing their nine children to ‘squat’ against a wall for hours with ‘no good reason at all’.

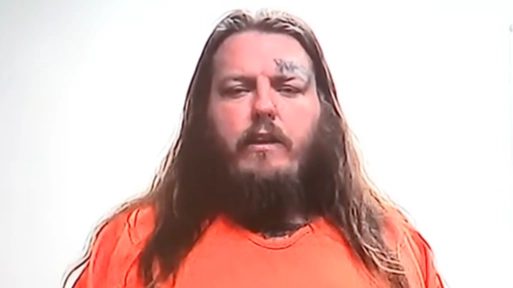
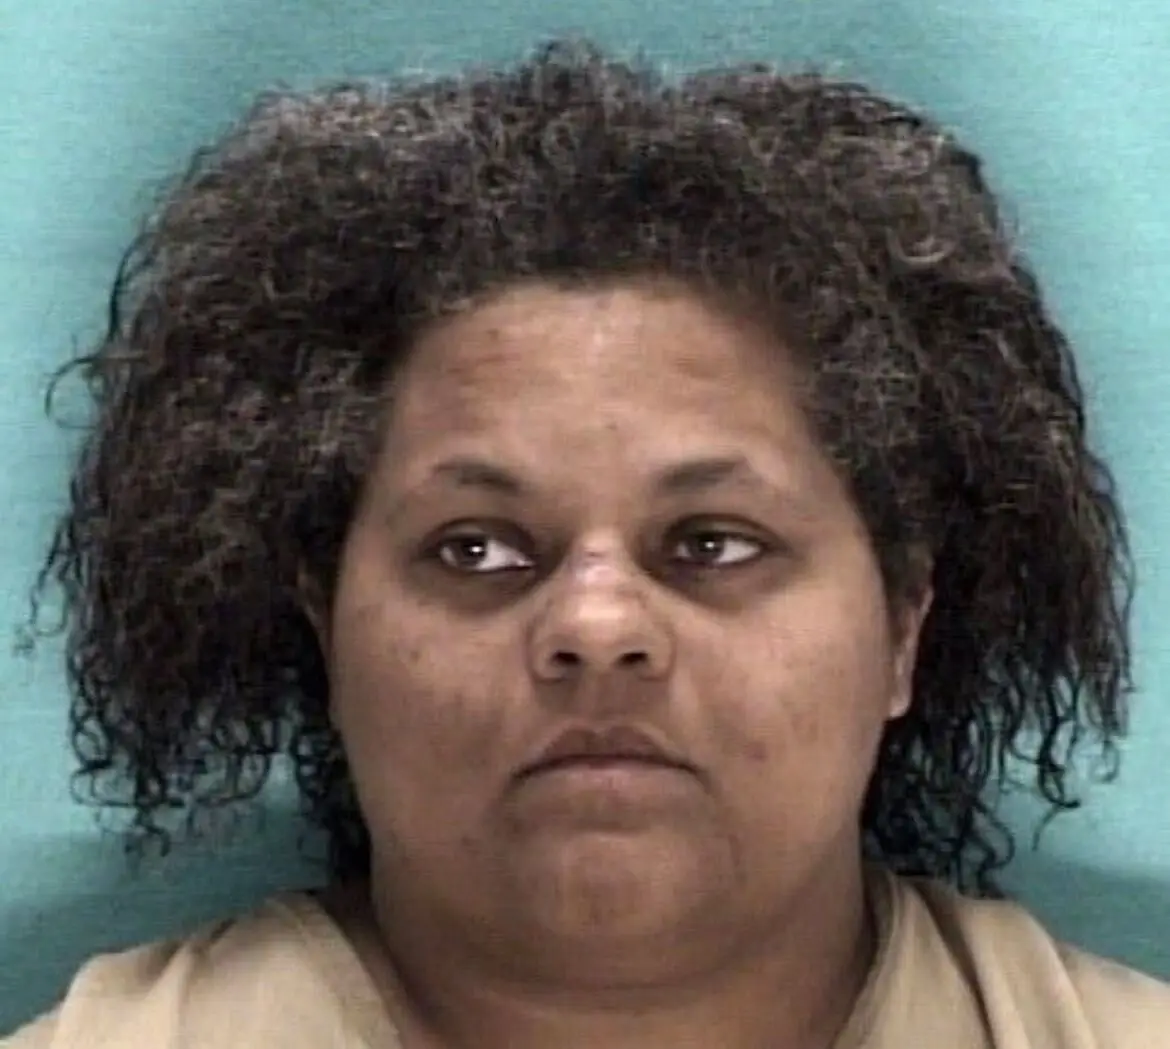
    Jonathan Parr, 37, and Jacqueline Coleman, 32, are being held on a $150,000 bond after Licking County Sheriff’s Office (LCSO) officers searched their Etna Township home to ‘discover deplorable living conditions and a bug infestation’, according to the complaint.

    Coleman is the mother to the nine children, all under the ages of 13, while Parr is the father to seven.

    In total, 12 people between the ages of 1 and 64 years old lived at the home, LSCO said.

    LCSO Captain Jay Cook told WBNS: “Part of the disclosure from the children was the abuse.

    Jacquelyn Coleman (Licking County Sheriff's Office)

    Jacquelyn Coleman (Licking County Sheriff’s Office)

    “Sometimes it was punishment; sometimes it was for no good reason at all, where they would have to stand with their back against the wall like a wall squat situation.

    “It was reported that they would sometimes have to stand there all day.”

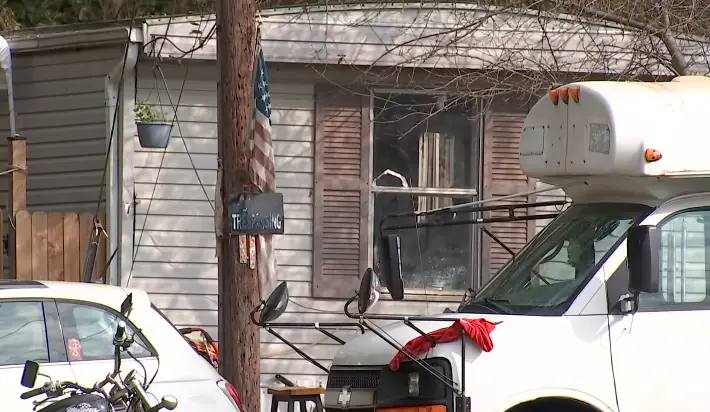
    When LCSO deputies arrived, they ‘discovered deplorable living conditions and a bug infestation, including inadequate sleeping arrangements and bedding for the juveniles’.

    Police searched their Etna Township home to ‘discover deplorable living conditions and a bug infestation’ (YouTube/WBNS 10TV)

    Police searched their Etna Township home to ‘discover deplorable living conditions and a bug infestation’ (YouTube/WBNS 10TV)

    The criminal complaint alleges that Coleman and Parr’s abuse went back as far as April 2023, as the pair ‘unlawfully, did administer corporal punishment or other physical disciplinary measure, or physically restrain the child in a cruel manner or for a prolonged period, which punishment, discipline, or restraint was excessive under the circumstances and created a substantial risk of serious physical harm’.

    “The Licking County Sheriff’s Office received a referral involving physical abuse and deplorable living conditions involving 9 juveniles,” the complaint adds.

    Jonathan Parr (Licking County Sheriff's Office)

    Jonathan Parr (Licking County Sheriff’s Office)

    The referral ‘outlined physical abuse, including failure to provide food and water, insufficient living space, and juveniles being forced to stand for hours with nails between their toes and locked behind cages or barriers’.

    As reported by WBNS 10TV, Parr said to the court that ‘it’s not true. I didn’t keep anybody in cages, any of the charges’.

    “I love my kids,” he added. “I would die for my kids.”

  • Should We Panic About Bitcoin and Altcoins After the Recent Drops? An Analysis Firm Responded by Naming Specific Altcoins

    Santiment also noted that the decline in the cryptocurrency market was not limited to digital assets. According to the platform’s data, since September 22, Bitcoin has lost approximately 6.5% of its value, while gold has fallen by between 4% and 5%. The decline in the S&P 500 index, however, remained at around 0.3%.

    Bitcoin Whales Have Accumulated Over 85,000 $BTC

    One of the most striking pieces of data in Santiment’s analysis was the purchases made by large Bitcoin investors.

    According to the platform, investors holding between 10 and 10,000 $BTC in their wallets have accumulated a total of 85,916 $BTC since September 18th. This accumulation, which occurred over approximately four weeks, shows that large investors continue to increase their Bitcoin positions despite price drops.

    However, Santiment noted that the continued buying by small investors does not create an ideal picture for a strong short-term recovery.

    According to analysts, a decrease in the number of small wallets holding less than 0.01 $BTC may indicate weakening optimism among individual investors regarding the market. Historically, periods when large investors accumulated while small investors withdrew from the market tended to create more favorable conditions for price increases.

    Santiment assessed that if large investors continue to hold onto their holdings and small investors slow down their purchases, the likelihood of Bitcoin returning to the $85,000 to $90,000 range could strengthen.

    Looking at on-chain data, Bitcoin’s 30-day market capitalization/realized value ratio (MVRV) has fallen to approximately minus 2.3 percent.

    This indicator suggests that investors who traded in the last 30 days are, on average, carrying unrealized losses. According to Santiment, while negative MVRV values historically indicate areas where buying opportunities might begin to emerge, current levels do not yet signal a strong opportunity.

    On the other hand, the 365-day MVRV indicator being at 0.56 percent reveals that it is quite close to the average cost for long-term investors.

    Bitcoin’s Relative Strength Index (RSI) is around 46.5. This value indicates that there are no significant overbought or oversold conditions in the market.

    Santiment also noted that funding rates on Binance have remained largely stable. According to analysts, a significant increase in negative funding rates could lead to a concentration of short positions, and short liquidations in a potential upward move could accelerate price action. However, current data does not yet point to such a scenario.

    It was also noteworthy that the amount of Bitcoin held on exchanges began to increase again after the sharp drop at the beginning of October. However, Santiment added that this increase was not at a level that would raise concerns about a large-scale sell-off.

    Related News Experienced Analyst Issues Warning About Bitcoin: “It Shouldn’t Close Above This Level This Week, or There Could Be a Sharp Drop”

    Santiment Explains Notable Movements in Altcoins

    Santiment, which also analyzed the altcoin market in addition to Bitcoin, noted that on-chain activity has increased significantly in some projects.

    In the platform’s activity analysis, Quant (QNT) stood out with activity data showing a 234% increase in the last 30 days and a 219% increase in the last 90 days.

    Staked Ethereum, Starknet (STRK), Wrapped Bitcoin (WBTC), Gnosis (GNO), LayerZero (ZRO), Ether.fi (ETHFI), Basic Attention Token (BAT), Bitcoin Cash (BCH), and Curve (CRV) were also among the notable projects.

    Santiment also noted that accumulation activity among the top 100 investors in the Virtuals Protocol (VIRTUAL) token has reached one of its highest levels in recent times.

    However, analysts emphasized that increased on-chain activity does not necessarily mean price increases. Increased activity can signal a recovery in declining assets, but it can also be a leading indicator of selling pressure in projects where excessive optimism is observed.

    Is It Too Early to Panic in the Cryptocurrency Market?

    According to Santiment, although pessimistic views are increasingly prevalent in the cryptocurrency market, a significant panic has not yet emerged.

    The platform’s social media analysis showed that approximately eight days ago, bearish expectations outpaced bullish expectations, followed immediately by a market recovery. Recently, however, positive and negative comments have reportedly returned to similar levels.

    Analysts pointed out that prices often move in the opposite direction when the vast majority of investors have the same expectations.

    The continued accumulation of large Bitcoin whales, the MVRV indicator moving into negative territory in the short term, and pessimism in market sentiment are considered positive signals for a possible recovery.

    However, the continued buying by small investors, the stability of funding rates, and the persistence of macroeconomic uncertainties indicate that a strong rally is not yet certain.

    *This is not investment advice.