What the 0.04% rate measures
The FXRP supply APR in that snapshot was about 0.04%, while the FXRP borrower APR was about 0.7%. The supply figure describes a simple annualized base rate at the observation time.
Rewards change the displayed return. In the Nov. 1 capture, Kinetic’s official FXRP row showed a 0.59% supply APY and a separately displayed 0.55% rFLR reward component. The reward component belongs inside the quoted yield comparison; adding it again to the headline supply APY would overstate the display.
DefiLlama’s specific isoFXRP pool page separately labeled its 0.57% supply APY as a 30-day average, alongside a 0.04% base component and a +0.54% reward component labeled WFLR. Rounding and differing observation windows limit direct reconciliation with the app’s figures.
DefiLlama’s Kinetic adapter calculates base yield from supply rates and rewards from separate emissions and token prices. That separation identifies the economic question behind the headline: how much comes from borrowers paying for credit, and how much comes from incentive distributions? The observed reward component was much larger than the quoted base rate.
Low token borrowing can coexist with collateral use
FlareSignal reported about 19.45 million FXRP supplied and 1.31 million FXRP borrowed in the dated observation. It also reported about 5.04 million USDT0 supplied and 4.68 million USDT0 borrowed. The utilization figures show substantially different demand for borrowing the two assets within the isolated market.
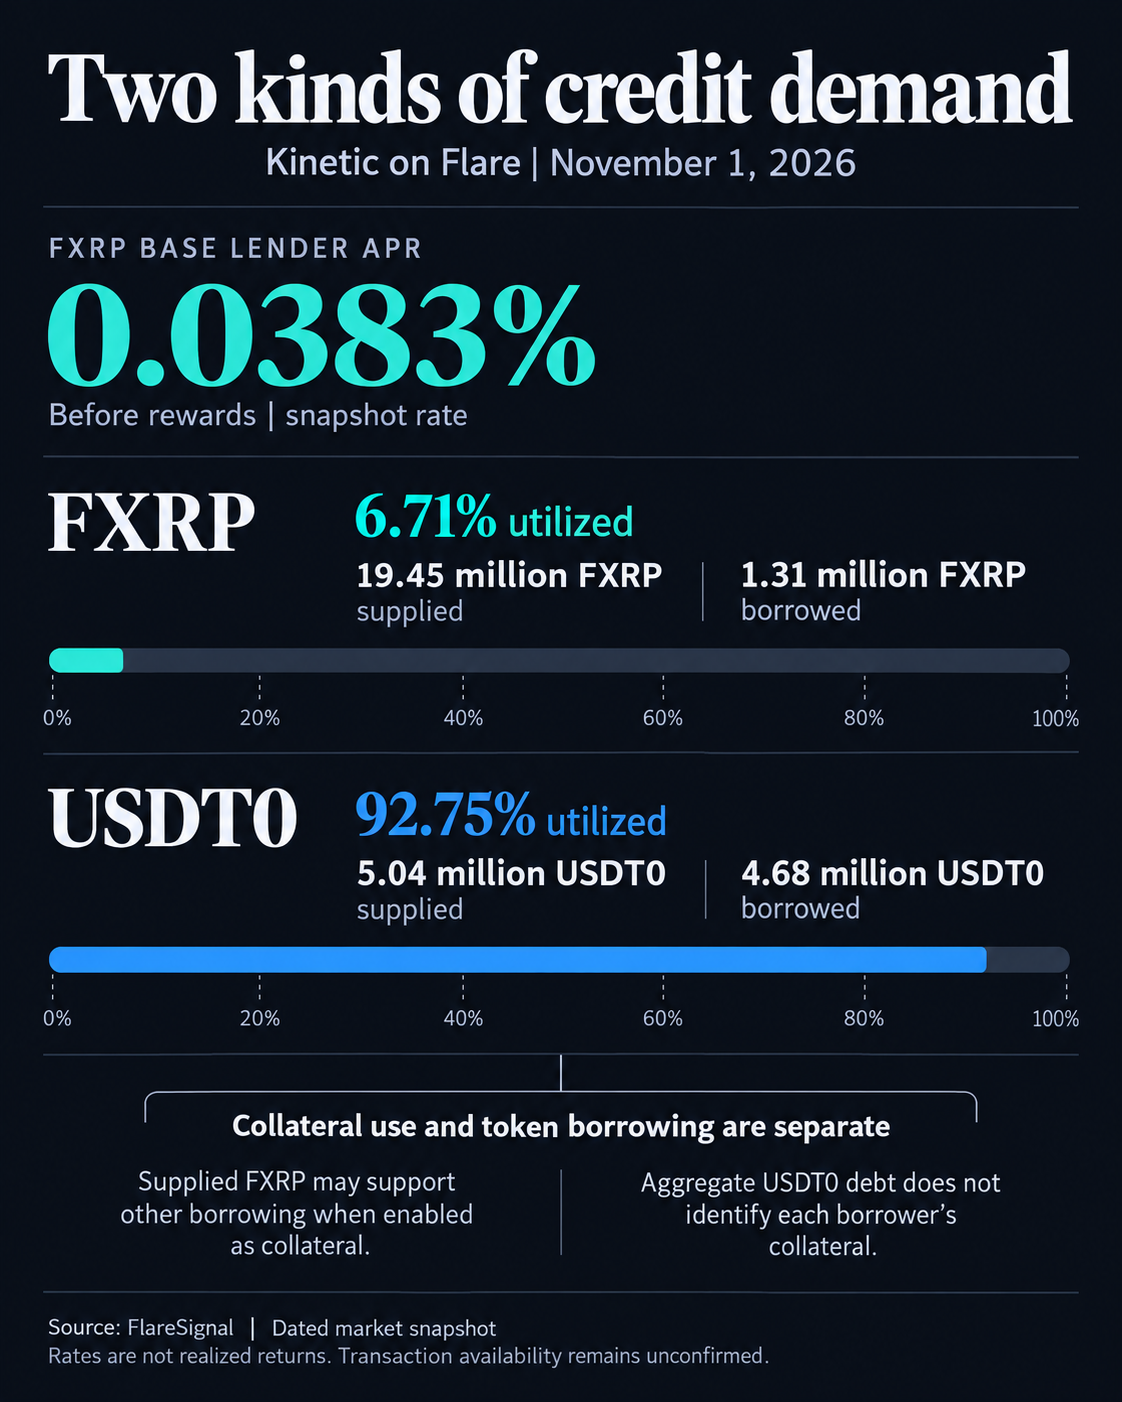
Supplied FXRP may also support borrowing when enabled as collateral and permitted by market rules. Kinetic’s lending documentation describes suppliers enabling assets as collateral to borrow other assets, with borrowers required to remain overcollateralized. Someone seeking stablecoin liquidity may value an $XRP-linked collateral position while having little use for an additional FXRP loan.
Collateral utility gives the holder access to borrowing. Any cash return to a supplier remains a separate benefit. A holder may value access to credit while receiving little base interest on the supplied asset.
The USDT0 figure reports aggregate market debt. Kinetic’s isolated-market contract directory identifies the market’s assets and infrastructure, but attributing that debt to FXRP collateral requires individual account data.
$XRP is the $XRP Ledger’s native asset, while the asset supplied to this Kinetic market is FXRP on Flare. That distinction places additional protocol steps between holding native $XRP and having a lending position.
Flare’s $XRP minting documentation describes sending underlying $XRP to the Core Vault on the $XRP Ledger, followed by an executor finalizing the FXRP mint on Flare using verified payment evidence. The FAssets system connects that representation to underlying assets and collateral arrangements.
The return journey has conditions too. Under the ordinary holder redemption process, FAssets are burned and underlying payment is initiated through the protocol. Fees and redemption-ticket limits can apply. If an agent fails to pay, compensation can involve collateral after proof of nonpayment.
Kinetic’s Nov. 1 observations show substantial FXRP supplied relative to FXRP loans, with a reward component much larger than base lender interest. For this lending market, the test for lasting demand is continued use of credit and the interest borrowers pay for it. The supplied balance establishes market size; those cash flows would establish a stronger foundation for lender income.
Leave a Reply